Good Debt vs Bad Debt: Understand the Difference (2026 Guide)

Posted on August 30, 2026 by admin

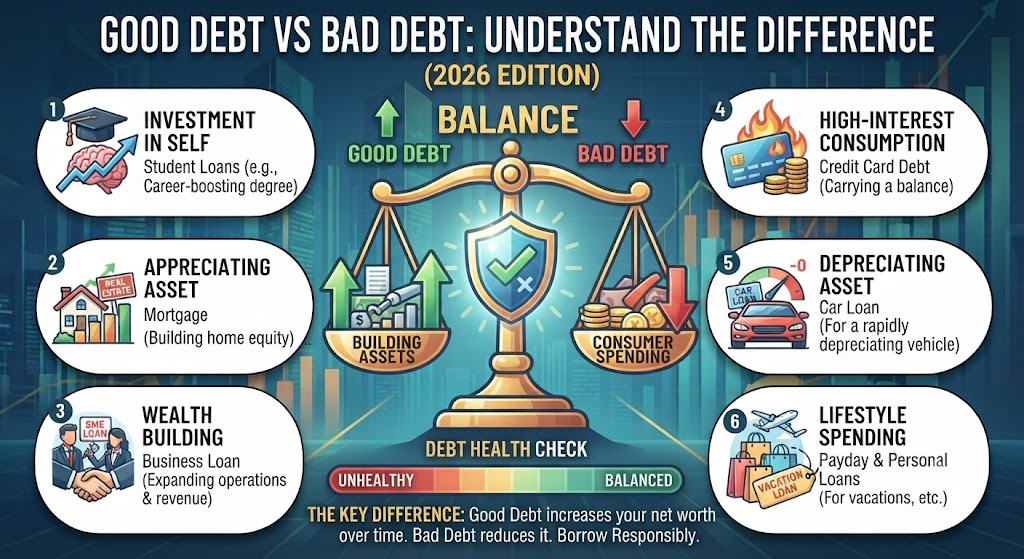
Infographic illustrating the differences between good and bad debt, featuring a central balance scale, building assets on the left, and consumer spending on the right, set against a financial cityscape background.

๐Ÿ’ณ Good Debt vs Bad Debt: Understand the Difference (2026 Guide)

Debt ko generally bad financial habit samjha jata hai, lekin har debt necessarily bad nahi hota. Kuch loans aapko productive asset ya long-term financial goal achieve karne mein help kar sakte hain, jabki kuch high-cost debt aapki financial progress ko negatively impact kar sakte hain.

Good Debt vs Bad Debt ko samajhna important hai, kyunki loan lene se pehle sirf EMI nahi, balki interest cost, purpose, repayment capacity aur overall financial impact ko bhi consider karna chahiye.

๐Ÿ“– Read Complete Good Debt vs Bad Debt Guide

What is Good Debt?

Good debt generally woh borrowing hoti hai jiska purpose long-term financial value create karna ya important productive goal ko finance karna ho. Lekin koi bhi loan automatically “good” nahi hota โ€” affordability aur terms bhi important hain.

  • ๐Ÿ  Home Loan โ€“ Suitable circumstances mein home purchase ko finance karne ke liye
  • ๐ŸŽ“ Education Loan โ€“ Career aur earning potential improve karne ke liye education finance karna
  • ๐Ÿ’ผ Business Loan โ€“ Productive business activity ya expansion ke liye
  • ๐Ÿ“ˆ Certain Asset-Financing Loans โ€“ Aise assets ke liye jo long-term value create kar sakte hain

๐Ÿ’ก Good Debt Ka Matlab “Free Money” Nahi Hai โ€” Repayment Capacity Aur Total Cost Hamesha Check Karein.


What is Bad Debt?

Bad debt generally woh borrowing hoti hai jo unnecessary consumption ko finance karti hai, high interest cost create karti hai ya repayment ke pressure ko unnecessarily increase karti hai.

  • ๐Ÿ’ณ High-interest credit card debt
  • ๐Ÿ›๏ธ Unnecessary shopping ke liye loans
  • ๐Ÿ“ฑ Lifestyle upgrades jo affordability se bahar hon
  • โœˆ๏ธ Unnecessary vacations ko debt se finance karna
  • ๐Ÿš— Unaffordable vehicle financing
  • ๐Ÿ”„ Ek loan repay karne ke liye repeatedly expensive debt lena

โš ๏ธ High Interest + Unnecessary Spending + Low Repayment Capacity = Debt Risk


Good Debt vs Bad Debt โ€“ Quick Comparison

Good Debt Bad Debt
Potentially productive purpose Primarily unnecessary consumption
May support long-term goals May delay financial goals
Terms and affordability are assessed Often expensive or poorly planned borrowing
Repayment is planned Repayment may create financial stress
Can be part of a broader financial plan Can reduce savings and investment capacity

Examples of Good Debt

๐Ÿ  1. Home Loan

Home loan ek long-term financial commitment hota hai. Agar property purchase financially affordable hai aur EMI comfortably manage ho sakti hai, toh home loan ek productive financial decision ho sakta hai.

Lekin sirf property kharidna hi loan ko “good debt” nahi banata. High EMI, excessive borrowing ya unaffordable property financial stress create kar sakti hai.

๐ŸŽ“ 2. Education Loan

Quality education ya professional qualification future earning potential improve kar sakti hai. Isliye suitable education financing ko long-term investment in earning capacity ke perspective se dekha ja sakta hai.

๐Ÿ’ผ 3. Business Loan

Business loan ka purpose agar productive expansion, equipment, working capital ya revenue-generating activity ko support karna hai, toh borrowing business growth mein useful ho sakti hai.


Examples of Bad Debt

๐Ÿ’ณ 1. High-Interest Credit Card Debt

Credit card ka convenience useful ho sakta hai, lekin outstanding balance par high interest financial burden create kar sakta hai. Minimum payment karte rehna debt ko long period tak carry kar sakta hai.

๐Ÿ›๏ธ 2. Unnecessary Shopping on EMI

Sirf isliye expensive product purchase karna ki EMI affordable dikh rahi hai, overall financial cost ko ignore kar sakta hai.

๐Ÿš— 3. Unaffordable Vehicle Loan

Vehicle loan tab financial pressure create kar sakta hai jab EMI ke saath fuel, insurance, maintenance aur depreciation ko bhi comfortably manage karna difficult ho.


Not All Debt Fits Into Only Two Categories

Debt ko sirf “good” ya “bad” label karna hamesha sufficient nahi hota. Ek hi type ka loan different individuals ke liye different financial impact create kar sakta hai.

Factor Why It Matters
Interest Rate Higher interest increases total borrowing cost
Loan Tenure Longer tenure can affect total interest cost
Purpose Productive and consumption borrowing have different outcomes
Repayment Capacity EMI should fit comfortably within the overall budget
Income Stability Unstable income can make fixed repayments more difficult

How to Decide Whether a Loan is Worth Taking?

  1. Purpose Check Karein: Loan kis purpose ke liye liya ja raha hai?
  2. Total Cost Calculate Karein: Sirf EMI nahi, total repayment aur interest cost dekhein.
  3. Repayment Capacity Check Karein: EMI aapke monthly budget mein comfortably fit hoti hai ya nahi?
  4. Emergency Fund Consider Karein: Loan lene ke baad bhi adequate emergency reserve maintain ho paayega ya nahi?
  5. Other Debts Review Karein: Existing loans aur credit card obligations ko bhi consider karein.
  6. Alternative Compare Karein: Purchase postpone karna, save karna ya lower-cost option choose karna better hai ya nahi?

๐ŸŽฏ Before Taking Debt: Purpose + Cost + EMI + Repayment Capacity + Financial Goals


How Bad Debt Can Affect Your Financial Goals

High-cost debt ka impact sirf interest payment tak limited nahi hota. Excessive debt aapki monthly cash flow aur future savings capacity ko bhi reduce kar sakta hai.

  • ๐Ÿ“‰ Monthly savings reduce ho sakti hain
  • ๐Ÿ’ฐ Investment capacity decrease ho sakti hai
  • ๐Ÿšจ Emergency fund build karna difficult ho sakta hai
  • ๐ŸŽ“ Children’s education goals delay ho sakte hain
  • ๐Ÿ–๏ธ Retirement planning impact ho sakti hai
  • ๐Ÿ˜Ÿ Financial stress increase ho sakta hai

How to Manage Existing Bad Debt?

  1. All Debts List Karein: Outstanding amount, interest rate aur EMI note karein.
  2. High-Cost Debt Identify Karein: Expensive debt ko priority se review karein.
  3. Unnecessary Borrowing Stop Karein: Jab tak existing debt manageable level par na aaye, unnecessary new borrowing avoid karein.
  4. Budget Tighten Karein: Temporary unnecessary expenses reduce karke repayment capacity improve karein.
  5. Extra Cash Flow Use Karein: Bonus ya additional income ko debt reduction ke liye consider kiya ja sakta hai.
  6. Debt Consolidation Carefully Evaluate Karein: Agar appropriate ho, lower-cost restructuring options ko compare karein.

Good Debt vs Bad Debt โ€“ Simple Rule

๐Ÿ’ก Good Debt: Borrowing That Supports a Meaningful Financial Goal

โš ๏ธ Bad Debt: Borrowing That Creates Unnecessary Cost and Financial Stress


Frequently Asked Questions

Q1. Kya har loan bad debt hota hai?

Nahi. Loan ka purpose, cost, repayment capacity aur overall financial impact determine karta hai ki borrowing financially suitable hai ya nahi.

Q2. Kya home loan good debt hai?

Home loan suitable circumstances mein productive borrowing ho sakta hai, lekin affordability, interest cost, tenure aur overall financial situation ko consider karna important hai.

Q3. Kya credit card bad debt hai?

Credit card khud automatically bad debt nahi hai. Lekin high-interest revolving balance ko carry karna expensive debt create kar sakta hai.

Q4. Kya education loan good debt hai?

Education loan potentially productive borrowing ho sakta hai agar education future career aur earning potential ko meaningfully support karti ho aur repayment financially manageable ho.

Q5. Kya personal loan good debt ho sakta hai?

Personal loan ka classification purpose aur cost par depend karta hai. Necessary financial need aur affordable repayment structure ka evaluation karna important hai.

Q6. Debt lene se pehle sabse important kya check karna chahiye?

Loan purpose, interest rate, total repayment cost, tenure, EMI, existing obligations aur repayment capacity ko carefully review karna chahiye.


Key Takeaway

๐Ÿ  Productive Debt + ๐Ÿ’ณ Controlled Borrowing + ๐Ÿ“Š Smart Repayment = Better Financial Management

Debt ko sirf good ya bad label se judge karne ke bajay uska purpose, total cost, repayment capacity aur impact on your financial goals ko evaluate karna chahiye.


Create Your Personal Debt Management Plan

Har person ki income, existing loans, EMIs, family responsibilities, savings aur financial goals different hote hain. Isliye debt repayment aur overall financial planning ke liye personalised strategy zyada useful ho sakti hai.

InvestSathi ke saath apni income, liabilities, savings aur financial goals ko review karke ek structured personal finance strategy par guidance lein.


Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial, investment, tax, loan, or insurance advice. Whether a debt is suitable depends on individual circumstances, loan terms, interest costs, repayment capacity, financial goals and other obligations. Please carefully review applicable loan terms and seek appropriate professional advice before taking financial decisions.
Emergency Fund Calculator Guide: How Much Emergency Fund Do You Need? (2026)

Posted on by admin

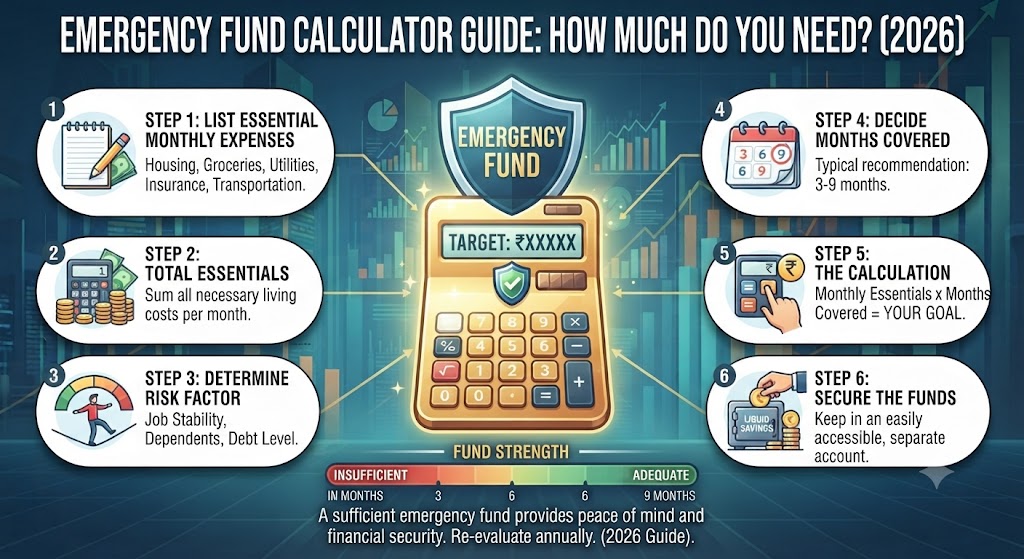
Infographic titled Debt-Free Journey: A Step-by-Step Guide with a central vault shield, progress bar, and step icons for tracking debt repayment.

๐Ÿšจ Emergency Fund Calculator Guide: How Much Emergency Fund Do You Need? (2026)

Emergency fund aapki financial planning ka ek important part hai. Unexpected medical expenses, job loss, business slowdown, urgent repairs ya other emergencies ke time par emergency fund aapko financial pressure manage karne mein help kar sakta hai.

Is guide mein hum simple formula ke through calculate karenge ki aapko kitna emergency fund maintain karna chahiye aur apne target tak kaise pahunch sakte hain.

๐Ÿ“– Read Complete Emergency Fund Calculator Guide

What is an Emergency Fund?

Emergency fund ek separate financial reserve hota hai jo unexpected aur urgent expenses ko manage karne ke liye rakha jata hai.

  • ๐Ÿšจ Unexpected medical expenses
  • ๐Ÿ’ผ Temporary loss of income
  • ๐Ÿ  Urgent home repairs
  • ๐Ÿš— Unexpected vehicle repairs
  • ๐Ÿ‘จโ€๐Ÿ‘ฉโ€๐Ÿ‘ง Family emergencies
  • ๐Ÿ“‰ Temporary income disruption

๐Ÿ’ก Emergency Fund Ka Purpose Return Kamana Nahi, Financial Emergency Mein Liquidity Provide Karna Hai.


How Much Emergency Fund Should You Have?

Emergency fund ka required amount har person ke liye same nahi hota. Ek practical starting point ke liye aap apne essential monthly expenses ko multiple months se multiply kar sakte hain.

๐Ÿงฎ Emergency Fund = Monthly Essential Expenses ร— Number of Months

Kitne months ka reserve appropriate hai, yeh income stability, dependents, debt, job/business nature aur personal circumstances par depend karta hai.


Step 1 โ€“ Calculate Your Essential Monthly Expenses

Emergency fund calculate karte waqt har expense ko include karna zaroori nahi hai. Sabse pehle essential expenses identify karein.

  • ๐Ÿ  Rent / Essential Home Expenses
  • ๐Ÿฒ Groceries & Basic Food
  • ๐Ÿ’ก Electricity, Water & Utilities
  • ๐Ÿš— Essential Transportation
  • ๐Ÿฅ Essential Healthcare Expenses
  • ๐Ÿฆ EMI / Necessary Loan Payments
  • ๐Ÿ“š Essential Education Expenses
  • ๐Ÿ“ฑ Basic Communication Expenses

Entertainment, luxury shopping, vacations aur other discretionary expenses ko emergency fund calculation mein generally priority nahi di jati.


Step 2 โ€“ Choose Your Emergency Fund Months

Aap apni financial situation ke according emergency fund ka target decide kar sakte hain.

Situation Possible Approach
Stable Income & Lower Responsibilities Lower end of the reserve range may be considered
Family with Regular Responsibilities Higher reserve may be appropriate
Variable Income / Business Larger emergency reserve may be useful
High Debt / EMI Obligations Consider stronger liquidity planning

Emergency Fund Calculator Example

Suppose aapke monthly essential expenses โ‚น40,000 hain.

Emergency Period Monthly Essential Expense Target Fund
3 Months โ‚น40,000 โ‚น1,20,000
6 Months โ‚น40,000 โ‚น2,40,000
9 Months โ‚น40,000 โ‚น3,60,000
12 Months โ‚น40,000 โ‚น4,80,000

Note: Yeh example sirf calculation samjhane ke liye hai. Actual emergency fund requirement individual circumstances par depend karegi.


Emergency Fund Calculator โ€“ Different Monthly Expenses

Monthly Essential Expenses 3 Months 6 Months 9 Months
โ‚น20,000 โ‚น60,000 โ‚น1,20,000 โ‚น1,80,000
โ‚น30,000 โ‚น90,000 โ‚น1,80,000 โ‚น2,70,000
โ‚น40,000 โ‚น1,20,000 โ‚น2,40,000 โ‚น3,60,000
โ‚น50,000 โ‚น1,50,000 โ‚น3,00,000 โ‚น4,50,000
โ‚น75,000 โ‚น2,25,000 โ‚น4,50,000 โ‚น6,75,000
โ‚น1,00,000 โ‚น3,00,000 โ‚น6,00,000 โ‚น9,00,000

Step 3 โ€“ Existing Emergency Savings Ko Subtract Karein

Agar aapke paas already emergency reserve available hai, toh target fund calculate karte waqt us amount ko consider karein.

๐Ÿงฎ Amount Still Needed = Target Emergency Fund โˆ’ Existing Emergency Savings

Example: Agar aapka target โ‚น2,40,000 hai aur existing emergency savings โ‚น1,00,000 hai, toh additional โ‚น1,40,000 build karna hoga.


Step 4 โ€“ Emergency Fund Build Karne Ka Monthly Plan

Agar aapko โ‚น2,40,000 ka emergency fund banana hai, toh monthly saving target ke according timeline plan ki ja sakti hai.

Monthly Contribution Approx. Time to Reach โ‚น2,40,000
โ‚น5,000 48 Months
โ‚น10,000 24 Months
โ‚น15,000 16 Months
โ‚น20,000 12 Months

Note: Figures are based on simple monthly contributions and do not assume investment returns.


Where Should You Keep Your Emergency Fund?

Emergency fund ka primary objective liquidity aur accessibility hona chahiye. Isliye emergency money ko aise place par rakhna important hai jahan zarurat padne par relatively quickly access kiya ja sake.

  • ๐Ÿฆ Savings Account
  • ๐Ÿ’ฐ Suitable liquid savings options
  • ๐Ÿ“Š Other low-volatility and accessible options, depending on individual circumstances

โš ๏ธ Emergency Fund Ko High-Risk Investments Mein Rakhna Appropriate Nahi Ho Sakta, Kyunki Emergency Ke Time Liquidity Important Hai.


Emergency Fund vs Investment

Emergency Fund Long-Term Investment
Primary goal: liquidity Primary goal: long-term wealth creation
Unexpected expenses Future financial goals
Lower focus on returns Returns may be an important consideration
High accessibility is important Time horizon can be longer

When Should You Increase Your Emergency Fund?

Emergency fund ek fixed amount nahi hota. Life circumstances change hone par target ko review karna useful ho sakta hai.

  • ๐Ÿ’ผ Job change ya income uncertainty
  • ๐Ÿ‘จโ€๐Ÿ‘ฉโ€๐Ÿ‘ง Family responsibilities increase hona
  • ๐Ÿฆ New loan / EMI obligations
  • ๐Ÿ  Home purchase ya major financial commitment
  • ๐Ÿ’ผ Business income becoming more variable
  • ๐Ÿ“ˆ Monthly essential expenses increase hona

Common Emergency Fund Mistakes

  • โŒ Emergency fund ko ignore karna
  • โŒ Sirf income ke basis par target calculate karna
  • โŒ Essential expenses ko accurately identify na karna
  • โŒ Emergency money ko highly volatile investments mein rakhna
  • โŒ Emergency fund use karne ke baad usse rebuild na karna
  • โŒ Family circumstances change hone ke baad target review na karna

Frequently Asked Questions

Q1. Emergency fund kitne months ka hona chahiye?

Iska answer individual circumstances par depend karta hai. Income stability, family responsibilities, debt aur other financial commitments ko consider karke suitable reserve decide kiya ja sakta hai.

Q2. Kya emergency fund salary ke basis par calculate karna chahiye?

Emergency fund calculate karte waqt monthly essential expenses ko base banana ek practical approach ho sakta hai.

Q3. Kya โ‚น1 lakh emergency fund enough hai?

Yeh aapke monthly essential expenses aur financial situation par depend karta hai. โ‚น1 lakh ek person ke liye sufficient ho sakta hai, jabki doosre person ke liye insufficient ho sakta hai.

Q4. Kya emergency fund ko Mutual Funds mein invest karna chahiye?

Emergency money ka primary objective liquidity aur accessibility hai. Isliye kisi bhi investment option ka selection karne se pehle liquidity, risk aur suitability ko carefully consider karna chahiye.

Q5. Emergency fund use karne ke baad kya karna chahiye?

Emergency expense ke baad remaining reserve ko review karein aur regular monthly savings ke through emergency fund ko dobara required level tak rebuild karein.


Key Takeaway

๐Ÿšจ Know Your Expenses + ๐Ÿงฎ Calculate Your Target + ๐Ÿ’ฐ Build Regularly + ๐Ÿ” Keep It Accessible

A well-planned emergency fund aapko unexpected financial situations ke time unnecessary financial stress aur forced borrowing se bachane mein help kar sakta hai.


Create Your Personal Emergency Fund Plan

Har individual ki income, monthly expenses, family responsibilities, debt aur financial goals different hote hain. Isliye ek personalised emergency fund target aur broader financial plan zyada useful ho sakta hai.

InvestSathi ke saath apne income, expenses aur financial goals ko review karke ek structured personal finance strategy par guidance lein.


Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial, investment, tax, or insurance advice. Emergency fund requirements vary based on individual income, expenses, liabilities, family responsibilities and financial circumstances. Investment products are subject to market risks. Please consider your financial goals, risk profile, liquidity needs and time horizon before making investment decisions.

How to Save โ‚น10,000 Every Month: A Simple Practical Guide (2026)

Posted on by admin

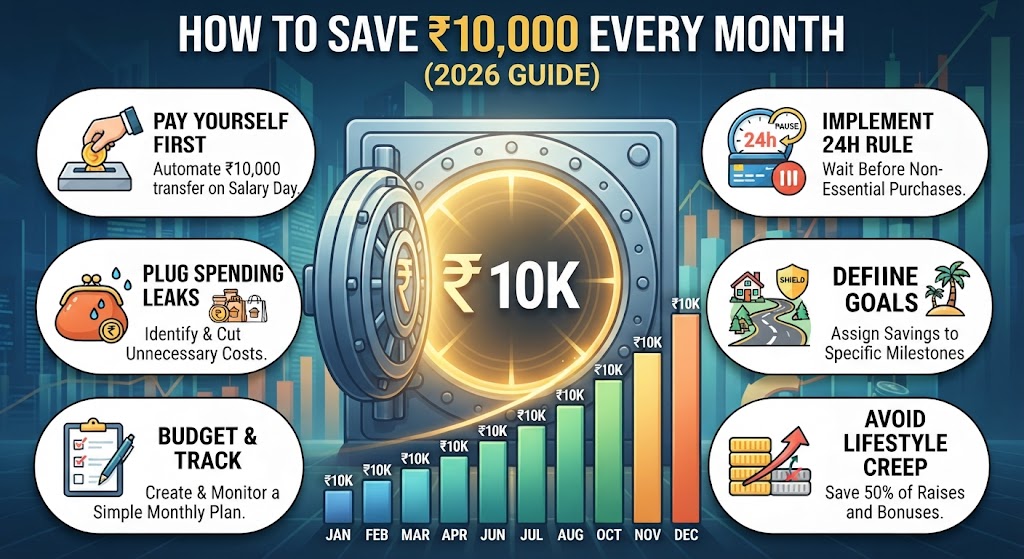
Infographic titled How to Save โ‚น10,000 Every Month featuring a central vault with a 10K sign, growth charts, and step icons for budgeting and saving.

๐Ÿ’ฐ How to Save โ‚น10,000 Every Month: A Simple Practical Guide (2026)

Har mahine โ‚น10,000 save karna mushkil lag sakta hai, lekin agar aap apni income aur expenses ko properly plan karein, toh yeh goal achievable ho sakta hai.
โ‚น10,000 monthly saving ka matlab hai โ‚น1,20,000 ki annual saving.

Is guide mein hum dekhenge ki unnecessary expenses ko identify karke, automatic savings aur disciplined budgeting ke through aap har month โ‚น10,000 save karne ka target kaise bana sakte hain.

๐Ÿ“– Read Complete Guide: How to Save โ‚น10,000 Every Month

Why Should You Save โ‚น10,000 Every Month?

Regular monthly saving financial discipline develop karne ka ek simple way hai. Agar aap โ‚น10,000 har month save karte hain, toh ek saal mein aapke paas:

๐Ÿ’ฐ โ‚น10,000 ร— 12 Months = โ‚น1,20,000 Per Year

Yeh amount emergency fund, future goals, education planning, retirement planning ya suitable investments ke liye use kiya ja sakta hai.


Step 1 โ€“ Apni Monthly Income Calculate Karein

Sabse pehle apni actual take-home income calculate karein. Budget banate waqt gross salary ke bajay woh amount consider karna practical hota hai jo aapke bank account mein available hota hai.

  • ๐Ÿ’ผ Salary
  • ๐Ÿ’ฐ Business income
  • ๐Ÿฆ Other regular income
  • ๐Ÿ“ˆ Regular investment income, where applicable

Income clear hone ke baad hi aap realistically โ‚น10,000 monthly saving ka target set kar sakte hain.


Step 2 โ€“ Apne Expenses Track Karein

Aksar problem income ki nahi, balki expenses ko track na karne ki hoti hai. Pichhle 2โ€“3 months ke expenses ko review karein aur dekhein ki paisa kis category mein ja raha hai.

  • ๐Ÿ  Rent / Home Expenses
  • ๐Ÿฒ Groceries
  • ๐Ÿ’ก Electricity & Utilities
  • ๐Ÿš— Transportation
  • ๐Ÿ“ฑ Mobile & Internet
  • ๐Ÿฝ๏ธ Dining Out
  • ๐Ÿ›๏ธ Shopping
  • ๐ŸŽฌ Entertainment
  • ๐Ÿ’ณ Credit Card Expenses
  • ๐Ÿฆ EMI / Loan Payments

๐Ÿ’ก Money Save Karne Ka First Step Hai: Pata Hona Ki Paisa Kahan Spend Ho Raha Hai.


Step 3 โ€“ โ‚น10,000 Saving Ko Chhote Targets Mein Divide Karein

Agar ek saath โ‚น10,000 save karna difficult lagta hai, toh target ko smaller categories mein divide karein.

Saving Area Monthly Target
๐Ÿฝ๏ธ Dining Out & Food Delivery โ‚น2,000
๐Ÿ›๏ธ Shopping โ‚น2,000
๐Ÿ“ฑ Subscriptions & Lifestyle โ‚น1,000
๐Ÿš— Transportation โ‚น1,500
๐Ÿ’ณ Unnecessary Credit Spending โ‚น1,500
๐Ÿ’ฐ Other Expense Reduction โ‚น2,000
Total Monthly Saving โ‚น10,000

Step 4 โ€“ Salary Aate Hi Pehle Save Karein

Ek common mistake hai ki log month ke end mein jo paisa bachta hai usse save karte hain. Iske bajay “Pay Yourself First” approach follow karein.

  1. Salary receive hone ke baad โ‚น10,000 alag account ya planned financial goal ke liye allocate karein.
  2. Remaining amount ko monthly expenses ke liye use karein.
  3. Automatic transfer ya investment setup karna discipline maintain karne mein helpful ho sakta hai.

๐ŸŽฏ Don’t Save What Is Left After Spending. Plan Your Savings Before You Spend.


Step 5 โ€“ Small Expenses Ko Control Karein

Chhote-chhote expenses monthly budget par significant impact daal sakte hain. Har expense ko completely stop karna zaroori nahi hai; bas unnecessary spending ko identify karein.

  • โ˜• Frequent cafe visits reduce karein
  • ๐Ÿ” Food delivery frequency control karein
  • ๐Ÿ›๏ธ Impulse shopping avoid karein
  • ๐Ÿ“ฑ Unused subscriptions cancel karein
  • ๐Ÿš— Short-distance unnecessary rides reduce karein
  • ๐Ÿ’ณ Credit card spending ko track karein

Step 6 โ€“ โ‚น10,000 Saving Ko Goal-Based Banayein

Saving ka purpose clear hone par discipline maintain karna easier ho sakta hai. โ‚น10,000 monthly saving ko different financial goals ke according allocate kiya ja sakta hai.

Financial Goal Possible Use
๐Ÿšจ Emergency Fund Unexpected expenses
๐ŸŽ“ Children’s Education Future education goal
๐Ÿ–๏ธ Retirement Long-term retirement corpus
๐Ÿ  Home Goal Down payment / future home goal
๐Ÿ“ˆ Investments Long-term financial goals

How Much Can You Save in 1, 3 & 5 Years?

Period Monthly Saving Total Contribution
1 Year โ‚น10,000 โ‚น1,20,000
3 Years โ‚น10,000 โ‚น3,60,000
5 Years โ‚น10,000 โ‚น6,00,000

Note: Above figures are simple contributions and do not include any investment returns.


What If Your Income Is Not High Enough?

Har person ke liye โ‚น10,000 monthly saving immediately possible nahi hoti. Agar aapki income aur essential expenses ke baad โ‚น10,000 save karna difficult hai, toh smaller target se start karein.

  • ๐Ÿ’ฐ โ‚น2,000 per month se start karein
  • ๐Ÿ“ˆ Income increase hone par saving amount badhayein
  • ๐ŸŽฏ Bonus ya additional income ka portion save karein
  • ๐Ÿ’ผ Side income opportunities consider karein
  • ๐Ÿ“Š Har 3โ€“6 months mein budget review karein

๐ŸŒฑ Small Savings + Consistency = Stronger Financial Discipline


Common Mistakes While Trying to Save โ‚น10,000

  • โŒ Savings ko month ke end tak postpone karna
  • โŒ Unnecessary shopping ko ignore karna
  • โŒ Credit card spending ko track na karna
  • โŒ Emergency fund ko ignore karna
  • โŒ Short-term savings ko long-term investment samajhna
  • โŒ Income increase hone par lifestyle expenses bahut zyada badha dena
  • โŒ Apne financial goals ko clearly define na karna

Frequently Asked Questions

Q1. Kya โ‚น10,000 har month save karna possible hai?

Haan, lekin yeh aapki income, essential expenses, debt aur financial responsibilities par depend karta hai. Har person ka suitable savings target different ho sakta hai.

Q2. โ‚น10,000 monthly save karne ka easiest way kya hai?

Salary receive hote hi โ‚น10,000 ko automatically separate account ya planned financial goal ke liye allocate karna ek practical approach ho sakta hai.

Q3. Agar main โ‚น10,000 save nahi kar sakta toh kya karun?

Smaller amount se start karein. โ‚น2,000, โ‚น5,000 ya jo amount realistically maintain ho sake, usse start karke gradually increase kiya ja sakta hai.

Q4. Kya โ‚น10,000 monthly saving ko invest karna chahiye?

Investment ka decision financial goal, time horizon, risk profile, liquidity needs aur overall financial situation par depend karta hai. Har saved amount ko automatically ek hi investment product mein invest karna zaroori nahi hai.

Q5. โ‚น10,000 monthly saving se 5 saal mein kitna paisa jama hoga?

Without considering investment returns, โ‚น10,000 per month save karne par 5 years mein total contribution โ‚น6,00,000 hoga.


Key Takeaway

๐Ÿ’ฐ Track Expenses + ๐ŸŽฏ Set a Target + ๐Ÿ“Š Control Spending + ๐Ÿ“ˆ Save Regularly

โ‚น10,000 monthly saving ka goal ek baar ka challenge nahi, balki consistent financial habit banane ka process hai.


Create Your Personal Savings Plan

Har individual ki income, expenses, EMIs, family responsibilities, existing savings aur financial goals different hote hain. Isliye ek customised savings aur financial planning strategy zyada useful ho sakti hai.

InvestSathi ke saath apne income aur financial goals ko review karke ek structured personal finance strategy par guidance lein.


Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial, investment, tax, or insurance advice. Savings and investment decisions should be based on individual financial goals, risk profile, liquidity requirements and time horizon. Investment products are subject to market risks. Please read all related documents carefully before investing.

Zero-Based Budgeting: Give Every Rupee a Purpose (2026 Guide)

Posted on August 24, 2026 by admin

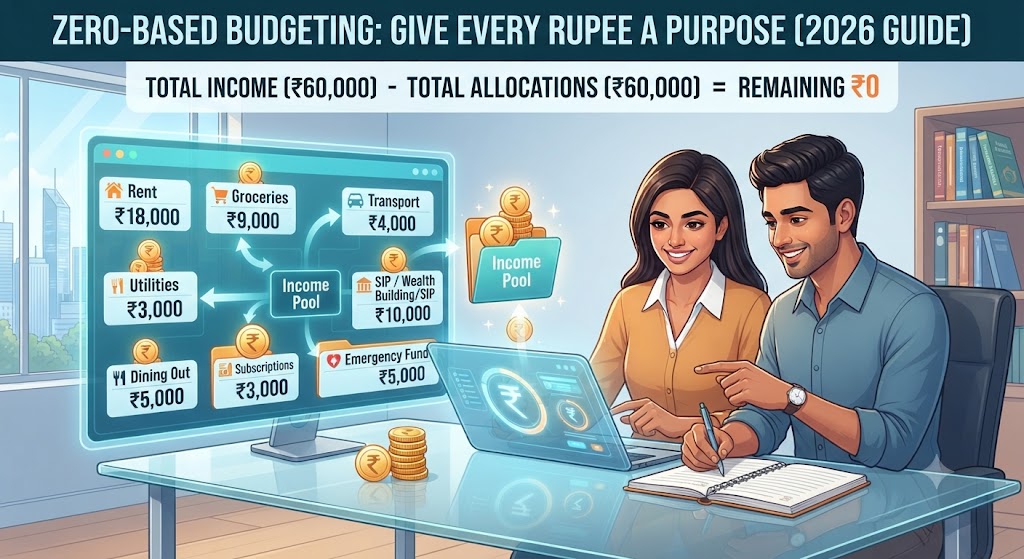
An illustration of a man and a woman sitting at a desk reviewing zero-based budgeting calculations on a laptop and a notebook, with a digital overlay showing income allocation categories and expenses.

“`html

๐Ÿ“Š Zero-Based Budgeting: Give Every Rupee a Purpose (2026 Guide)

Kya aapki salary har month aa jaati hai, lekin month ke end mein samajh nahi aata ki paisa kahan chala gaya? Zero-Based Budgeting ek aisa budgeting method hai jisme aap apni poori income ko pehle se different expenses, savings, investments aur financial goals ke liye allocate kar dete hain.

Iska simple principle hai โ€” Income โˆ’ Planned Expenses โˆ’ Savings โˆ’ Investments = โ‚น0. Yahan โ‚น0 ka matlab paisa khatam karna nahi hai, balki income ke har rupee ko ek specific purpose assign karna hai.

๐Ÿ“– Read Complete Zero-Based Budgeting Guide

Zero-Based Budgeting Kya Hai?

Zero-Based Budgeting, ya ZBB, ek budgeting approach hai jisme monthly income ko completely allocate kiya jata hai. Har rupee ko kisi na kisi category mein assign kiya jata hai.

Ismein sirf monthly expenses hi nahi, balki Emergency Fund, Investments, Insurance Premiums, Debt Repayment aur Future Goals ko bhi budget ka part banaya ja sakta hai.

๐Ÿ’ก Golden Rule: Zero-Based Budget ka matlab โ‚น0 balance rakhna nahi, balki โ‚น0 unassigned money rakhna hai.


Zero-Based Budgeting Formula

Monthly Income โˆ’ All Planned Allocations = โ‚น0

Example: โ‚น75,000 Income โˆ’ โ‚น75,000 Allocated = โ‚น0 Unassigned

Agar โ‚น75,000 income mein se โ‚น60,000 expenses aur savings ke liye allocate kiye gaye hain, toh remaining โ‚น15,000 ko bhi kisi purpose โ€” jaise investment, emergency fund, debt repayment ya future purchase โ€” ke liye assign karna hoga.


Zero-Based Budget Kaise Banayein?

  1. Monthly Income Calculate Karein:
    Apni actual take-home income identify karein. Agar income variable hai toh conservative estimate use karna practical ho sakta hai.
  2. Fixed Expenses List Karein:
    Rent, EMI, school fees, insurance premiums aur other recurring expenses ko note karein.
  3. Variable Expenses Estimate Karein:
    Groceries, electricity, transportation, medical aur other monthly expenses ka realistic estimate banayein.
  4. Savings & Investments Allocate Karein:
    Emergency Fund, SIP, retirement planning aur other financial goals ke liye amount assign karein.
  5. Debt Repayment Plan Karein:
    High-interest debt ya outstanding dues ke repayment ke liye specific amount allocate karein.
  6. Remaining Money Ko Assign Karein:
    Jo amount bach raha hai usse bhi kisi financial goal ya expense category ko assign karein.
  7. Month-End Review Karein:
    Actual spending ko planned budget ke saath compare karein aur next month budget adjust karein.

Example: โ‚น75,000 Monthly Income

Maan lijiye kisi individual ki monthly take-home income โ‚น75,000 hai. Zero-Based Budget ka ek illustrative example:

Category Monthly Allocation
๐Ÿ  Rent / Home Expenses โ‚น18,000
๐Ÿฒ Food & Groceries โ‚น8,000
๐Ÿš— Transport & Utilities โ‚น6,000
๐ŸŽฏ Lifestyle / Wants โ‚น7,000
๐Ÿ›ก๏ธ Insurance โ‚น4,000
๐Ÿšจ Emergency Fund โ‚น7,000
๐Ÿ“ˆ Investments / SIP โ‚น15,000
๐Ÿ’ณ Debt Repayment / Other Goals โ‚น10,000
Total Allocation โ‚น75,000

Note: Yeh sirf illustrative example hai. Actual allocation individual income, expenses, liabilities, family responsibilities aur financial goals ke according different ho sakta hai.


Zero-Based Budgeting vs Traditional Budgeting

Traditional Budget Zero-Based Budget
Previous spending ko base bana sakta hai Har category ko consciously allocate kiya jata hai
Unallocated money bach sakta hai Har rupee ko purpose diya jata hai
Less detailed ho sakta hai More detailed planning require karta hai
Simple to maintain Regular tracking aur review important hai

Zero-Based Budgeting Ke Benefits

  • ๐Ÿ’ฐ Better Money Control: Aapko pata hota hai paisa kis purpose ke liye allocate hai.
  • ๐Ÿ“‰ Unnecessary Spending Reduce: Random spending ko identify karna easier ho sakta hai.
  • ๐ŸŽฏ Goal-Based Saving: Financial goals ko monthly budget mein include kiya ja sakta hai.
  • ๐Ÿ“ˆ Investment Discipline: Investment amount ko pehle se allocate kiya ja sakta hai.
  • ๐Ÿ’ณ Debt Management: Loan aur credit card repayment ke liye dedicated amount set kiya ja sakta hai.
  • ๐Ÿšจ Emergency Preparedness: Emergency Fund ko regular budget ka part banaya ja sakta hai.

Common Mistakes in Zero-Based Budgeting

  • โŒ Unrealistic expense estimates banana.
  • โŒ Annual expenses ko monthly budget mein include na karna.
  • โŒ Emergency expenses ke liye buffer na rakhna.
  • โŒ Har month budget review na karna.
  • โŒ Wants aur needs ko properly separate na karna.
  • โŒ Income badhne par budget update na karna.

Zero-Based Budgeting Mein Annual Expenses Kaise Manage Karein?

Kuch expenses monthly nahi aate, jaise annual insurance premium, school fees, vehicle insurance, festival expenses ya yearly subscriptions. In expenses ko ignore karne ke bajay unka monthly provision budget mein include kiya ja sakta hai.

Example: Agar kisi annual expense ka estimated amount โ‚น24,000 hai, toh approximately โ‚น2,000 per month side mein allocate karke us future expense ke liye provision banaya ja sakta hai.

๐Ÿ“… Annual expenses ko monthly budget mein divide karna financial surprises ko reduce karne mein help kar sakta hai.


Frequently Asked Questions

Q1. Zero-Based Budgeting ka matlab kya hai?
Iska matlab hai monthly income ke har rupee ko kisi specific expense, saving, investment, debt repayment ya financial goal ke liye allocate karna.

Q2. Kya Zero-Based Budget mein bank account balance โ‚น0 hona chahiye?
Nahi. โ‚น0 ka matlab unassigned money hai. Aapke bank accounts mein savings aur emergency reserves available reh sakte hain.

Q3. Kya Zero-Based Budgeting salary wale logon ke liye useful hai?
Haan. Fixed salary wale individuals ke liye monthly allocation relatively simple ho sakta hai. Variable income wale log conservative income estimate ke saath budgeting kar sakte hain.

Q4. Kya investments ko Zero-Based Budget mein include karna chahiye?
Haan. Long-term financial goals ke liye planned investments ko monthly budget ka part banaya ja sakta hai.

Q5. Kya Zero-Based Budgeting aur 50/30/20 Rule same hain?
Nahi. 50/30/20 ek broad budgeting framework hai, jabki Zero-Based Budgeting mein income ke har rupee ko specific purpose ke liye allocate kiya jata hai.


Key Takeaway

๐Ÿ’ฐ Give Every Rupee a Purpose

Income โˆ’ Expenses โˆ’ Savings โˆ’ Investments โˆ’ Goals = โ‚น0 Unassigned Money

Zero-Based Budgeting aapko apne paison par better control, disciplined saving aur goal-based financial planning develop karne mein help kar sakta hai.


Create Your Personal Budget Plan

Aapki income, monthly expenses, EMIs, insurance, existing investments aur future goals ke according ek personalised budget plan zyada effective ho sakta hai.

InvestSathi ke saath apni personal finance strategy ko review karein aur savings, investments, insurance aur financial goals ko systematically plan karne ke liye guidance lein.


Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial, investment, tax, or insurance advice. Investment products are subject to market risks. Please consider your financial goals, risk profile and time horizon and review relevant product documents before making investment decisions.

“`

50/30/20 Budget Rule: A Simple Way to Manage Your Money (2026 Guide)

Posted on by admin

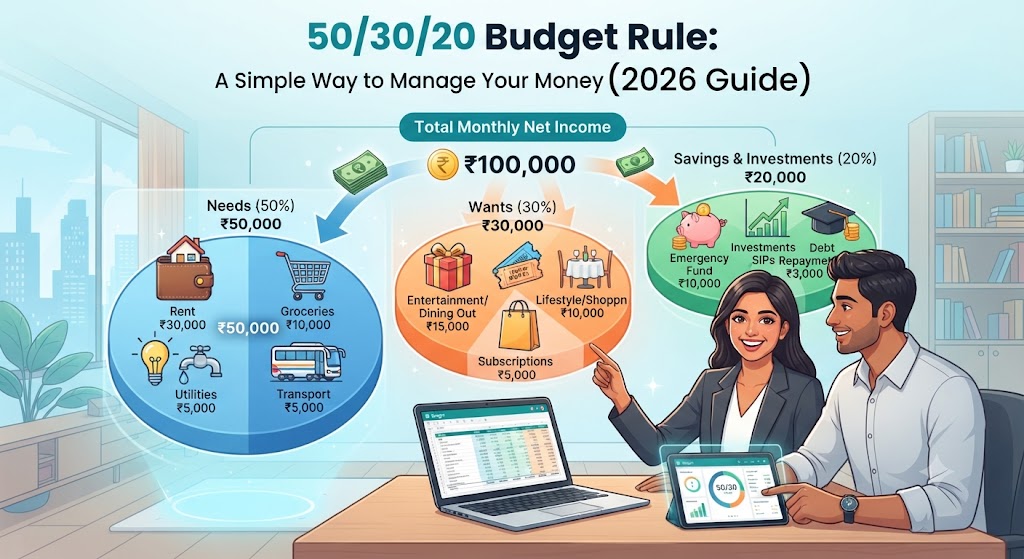
An infographic titled "50/30/20 Budget Rule: A Simple Way to Manage Your Money (2026 Guide)" depicting a flow of โ‚น100,000 into Needs (50%), Wants (30%), and Savings/Investments (20%) categories, with a man and woman using a laptop and tablet at a desk.

“`html

๐Ÿ’ฐ 50/30/20 Budget Rule: A Simple Way to Manage Your Money (2026 Guide)

Har mahine salary aati hai, lekin month ke end tak pata hi nahi chalta ki paisa kahan chala gaya? Agar aap bhi apni income ko better tarike se manage karna chahte hain, toh 50/30/20 Budget Rule ek simple aur practical budgeting framework ho sakta hai.

Is rule ke according aap apni after-tax income ko teen major categories mein divide karte hain โ€” 50% Needs, 30% Wants aur 20% Savings & Investments. Isse aapko spending aur saving ke beech balance banane mein help mil sakti hai.

๐Ÿ“– Read Complete 50/30/20 Budget Rule Guide

What is the 50/30/20 Budget Rule?

50/30/20 Rule ek budgeting method hai jisme monthly take-home income ko broadly teen parts mein divide kiya jata hai:

  • ๐Ÿ  50% โ€“ Needs: Essential aur necessary expenses.
  • ๐ŸŽฏ 30% โ€“ Wants: Lifestyle aur discretionary expenses.
  • ๐Ÿ’ฐ 20% โ€“ Savings & Financial Goals: Savings, investments aur debt repayment.

๐Ÿ’ก Golden Rule: Budget ka purpose har rupee ko restrict karna nahi, balki har rupee ko ek clear purpose dena hai.


50% โ€“ Needs: Zaroori Expenses

Needs woh expenses hain jo aapki basic lifestyle aur essential responsibilities ke liye zaroori hote hain. In expenses ko avoid karna ya bahut zyada reduce karna practical nahi hota.

  • ๐Ÿ  Rent ya essential home expenses
  • ๐Ÿฒ Groceries aur basic food expenses
  • ๐Ÿ’ก Electricity, water aur basic utilities
  • ๐Ÿš— Essential transportation expenses
  • ๐Ÿฅ Essential healthcare expenses
  • ๐Ÿ“š Basic education-related expenses
  • ๐Ÿฆ Necessary loan/EMI payments

Agar aapke essential expenses income ke 50% se kaafi zyada hain, toh expenses review karna, income increase karna ya budgeting percentage ko temporarily adjust karna useful ho sakta hai.


30% โ€“ Wants: Lifestyle Expenses

Wants woh expenses hain jo life ko comfortable aur enjoyable banate hain, lekin survival ke liye essential nahi hote.

  • ๐Ÿฝ๏ธ Restaurant aur dining out
  • ๐ŸŽฌ Movies aur entertainment
  • โœˆ๏ธ Travel aur vacations
  • ๐Ÿ›๏ธ Shopping
  • ๐Ÿ“ฑ Premium subscriptions
  • โ˜• Cafes aur lifestyle expenses
  • ๐ŸŽฎ Hobbies aur recreational activities

๐Ÿ˜Š Budgeting ka matlab enjoyment completely stop karna nahi hai. Goal hai ki lifestyle expenses aapke financial goals ko damage na karein.


20% โ€“ Savings, Investments & Financial Goals

20% category ka purpose future financial security build karna hai. Is amount ko aap apne goals aur financial situation ke according allocate kar sakte hain.

  • ๐Ÿšจ Emergency Fund: Unexpected expenses ke liye reserve build karna.
  • ๐Ÿ“ˆ Investments: Long-term financial goals ke liye suitable investments.
  • ๐Ÿฆ Debt Repayment: High-interest debt ko reduce karna.
  • ๐ŸŽ“ Goal Planning: Children’s education jaise future goals ke liye corpus banana.
  • ๐Ÿ–๏ธ Retirement Planning: Long-term retirement corpus ke liye investing.

Example: โ‚น50,000 Monthly Take-Home Income

Agar aapki monthly take-home income โ‚น50,000 hai, toh 50/30/20 framework ka basic example kuch is tarah ho sakta hai:

Category Percentage Amount Examples
Needs 50% โ‚น25,000 Rent, food, utilities, EMI
Wants 30% โ‚น15,000 Shopping, travel, entertainment
Savings & Goals 20% โ‚น10,000 Emergency fund, investments, debt repayment

50/30/20 Rule: Different Income Examples

Monthly Income 50% Needs 30% Wants 20% Savings
โ‚น30,000 โ‚น15,000 โ‚น9,000 โ‚น6,000
โ‚น50,000 โ‚น25,000 โ‚น15,000 โ‚น10,000
โ‚น75,000 โ‚น37,500 โ‚น22,500 โ‚น15,000
โ‚น1,00,000 โ‚น50,000 โ‚น30,000 โ‚น20,000

Kya 50/30/20 Rule Har Kisi Ke Liye Same Hona Chahiye?

Nahi. 50/30/20 ek guideline hai, strict financial law nahi. Har family ki income, city, rent/EMI, family responsibilities, age, debt aur financial goals alag hote hain.

For example, agar kisi person ke essential expenses high hain, toh woh temporarily 60/20/20 ya 60/25/15 jaisa customised budget use kar sakta hai. High income aur low liabilities wale individuals savings/investments ka percentage aur zyada rakh sakte hain.

๐ŸŽฏ Best Budget Rule = Jo aapki income, responsibilities aur financial goals ke according realistically follow ho sake.


50/30/20 Budget Rule Ko Follow Kaise Karein?

  1. Monthly Take-Home Income Calculate Karein: Budgeting ke liye actual available income ko identify karein.
  2. Expenses Track Karein: Pichhle 2โ€“3 months ke expenses review karein.
  3. Needs Aur Wants Separate Karein: Essential aur discretionary expenses ko alag categories mein rakhein.
  4. 20% Financial Goals Ke Liye Allocate Karein: Emergency fund, debt repayment aur investments ko priority dein.
  5. Automatic Savings Setup Karein: Salary aate hi savings/investment amount allocate karna useful ho sakta hai.
  6. Monthly Review Karein: Har month budget compare karke unnecessary expenses identify karein.

Common Budgeting Mistakes

  • โŒ Salary badhte hi lifestyle expenses ko unnecessarily increase kar dena.
  • โŒ Credit card spending ko income ka part samajhna.
  • โŒ Emergency Fund ko ignore karna.
  • โŒ Savings ko month ke end mein karna.
  • โŒ Long-term goals ke liye investing delay karna.
  • โŒ Budget ko family circumstances ke according review na karna.

Frequently Asked Questions

Q1. 50/30/20 Rule kya hai?
Yeh ek budgeting framework hai jisme take-home income ko approximately 50% needs, 30% wants aur 20% savings/financial goals mein divide kiya jata hai.

Q2. Kya 50/30/20 Rule salary ke gross income par apply hota hai?
Generally budgeting ke liye take-home income ya after-tax income ko base banana zyada practical hota hai.

Q3. Agar meri needs 50% se zyada hain toh kya karun?
Pehle essential expenses ko identify karein. Jahan possible ho, unnecessary costs reduce karein, debt ko review karein aur income badhane ke opportunities dekhein. Zarurat ke according budget percentages customise kiye ja sakte hain.

Q4. Kya 20% amount Mutual Funds mein invest karna chahiye?
Investment product ka selection aapke goal, time horizon, risk profile aur overall financial situation par depend karta hai. Puri 20% amount ko automatically ek hi investment product mein invest karna zaroori nahi hai.

Q5. Kya Emergency Fund bhi 20% category mein aa sakta hai?
Haan. Jab tak required emergency reserve build nahi ho jata, savings allocation ka ek portion emergency fund ke liye use kiya ja sakta hai.


Key Takeaway

๐Ÿ’ฐ 50% Needs + ๐ŸŽฏ 30% Wants + ๐Ÿ“ˆ 20% Savings & Financial Goals

50/30/20 Rule ek simple starting framework hai jo aapko spending, saving aur investing ke beech better balance banane mein help kar sakta hai.


Create Your Personal Budget Plan

Har person ka ideal budget alag hota hai. Aapki income, family expenses, EMIs, existing savings, investments aur future goals ke according ek customised financial plan zyada useful ho sakta hai.

InvestSathi ke saath apne income aur financial goals ko review karke ek structured personal finance strategy par guidance lein.


Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial, investment, tax, or insurance advice. The 50/30/20 framework is a general budgeting guideline and may not be suitable for every individual. Investment products are subject to market risks. Please consider your financial goals, risk profile and time horizon before making investment decisions.

“`