🏠 Smart Budgeting for Families: A Practical Guide to Managing Family Money (2026)
Managing money as a family is not only about reducing expenses. Smart budgeting means knowing where your money goes, planning for important family goals, saving regularly, and investing wisely for the future.
Whether you have a single income or multiple sources of income, a well-planned family budget can help reduce financial stress and create a stronger financial foundation for education, home ownership, retirement and other long-term goals.
📖 Read Complete Smart Family Budgeting Guide
What Is Family Budgeting?
Family budgeting is the process of planning how your household income will be used for expenses, savings, investments, debt repayment and future financial goals.
A good family budget should be simple, realistic and flexible. The objective is not to stop spending, but to make sure your money is being used according to your priorities.
1️⃣ Know Your Total Family Income
Start by calculating your total monthly household income. Include salary, business income, rental income and other regular sources of income.
- Monthly salary
- Business income
- Rental income
- Regular side income
- Other predictable income
2️⃣ Separate Needs From Wants
One of the most important budgeting habits is understanding the difference between essential expenses and discretionary spending.
| Needs | Wants |
|---|---|
| Rent / Home Loan | Luxury Shopping |
| Groceries | Frequent Dining Out |
| School Fees | Entertainment |
| Insurance | Unplanned Purchases |
3️⃣ Create a Monthly Family Budget
Create categories for all major household expenses. A simple structure can include:
- 🏠 Housing
- 🍎 Food & Groceries
- 🎓 Education
- 🚗 Transportation
- 💡 Utilities
- 🛡️ Insurance
- 💳 Debt Repayment
- 💰 Savings
- 📈 Investments
- 🎯 Lifestyle & Entertainment
4️⃣ Follow the “Save First” Rule
Instead of spending first and saving whatever remains, make savings and investments a priority from the beginning of the month.
Automating SIPs, recurring deposits or other planned savings can make this process easier and more consistent.
5️⃣ Build an Emergency Fund
Every family should have money available for unexpected situations such as job loss, major repairs, medical emergencies or sudden financial commitments.
A commonly used approach is to gradually build an emergency reserve covering several months of essential household expenses. The right amount depends on your income stability, family responsibilities and financial situation.
6️⃣ Plan for Children’s Education
Education is one of the biggest long-term financial goals for many families. Instead of waiting until the expense is close, start planning early.
- Estimate the future education cost.
- Consider inflation.
- Determine the investment horizon.
- Invest according to your risk profile and goal.
- Review the plan regularly.
7️⃣ Budget for Insurance
Insurance should be considered a part of financial planning rather than an optional expense.
Families should review appropriate health insurance and life insurance needs based on income, dependants, liabilities and overall financial responsibilities.
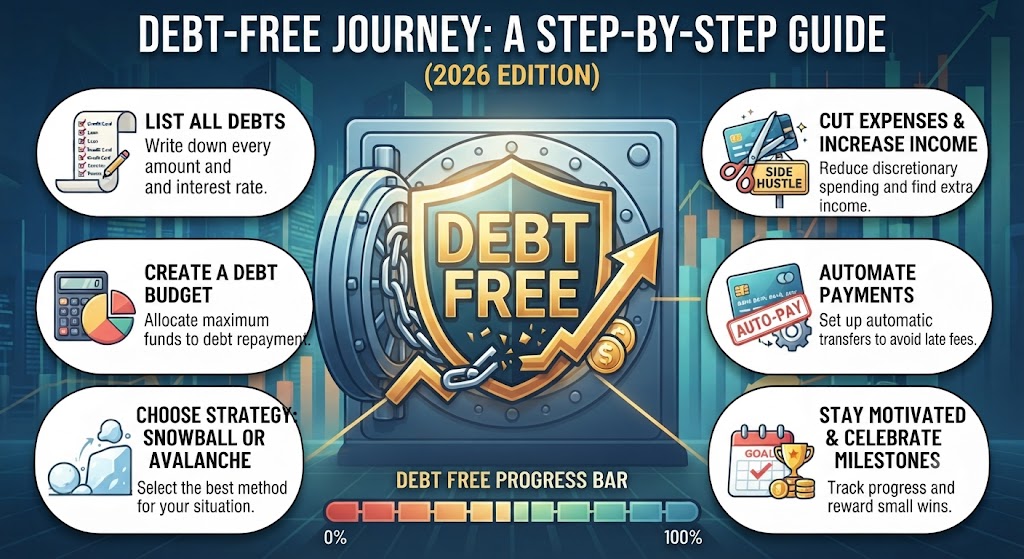
8️⃣ Manage Family Debt Carefully
EMIs can significantly affect a family’s monthly cash flow. Keep track of all loans, interest rates, outstanding balances and repayment dates.
- Avoid unnecessary high-cost debt.
- Pay EMIs on time.
- Prioritize expensive debt where appropriate.
- Avoid taking new debt simply to fund lifestyle spending.
9️⃣ Set Family Financial Goals
A budget becomes more meaningful when it is connected to specific goals.
| Goal | Suggested Approach |
|---|---|
| Emergency Fund | Build accessible savings |
| Child Education | Long-term goal-based investing |
| Home | Down-payment planning |
| Retirement | Long-term retirement planning |
🔟 Use a Simple Budgeting Framework
A simple starting point is the 50-30-20 framework:
- 50% – Needs: Essential household expenses
- 30% – Wants: Lifestyle and discretionary spending
- 20% – Savings & Investments: Future goals and wealth creation
However, this is only a general framework. Every family has different income levels, responsibilities, debt and financial goals, so the percentages should be customized.
💰 Example: ₹1,00,000 Monthly Family Income
| Category | Example Allocation |
|---|---|
| Essential Expenses | ₹50,000 |
| Lifestyle / Wants | ₹20,000 |
| Savings | ₹10,000 |
| Investments | ₹15,000 |
| Buffer / Miscellaneous | ₹5,000 |
This is only an illustration. Your actual allocation should depend on your family’s financial goals, liabilities, emergency fund, insurance coverage and investment horizon.
📋 Monthly Family Budget Checklist
- ☐ Calculate total monthly income
- ☐ Track major expenses
- ☐ Review EMIs and debt
- ☐ Set aside savings
- ☐ Invest according to financial goals
- ☐ Review insurance coverage
- ☐ Check emergency fund progress
- ☐ Review children’s education planning
- ☐ Review retirement planning
- ☐ Discuss major financial decisions as a family
⚠️ Common Family Budgeting Mistakes
- Spending without tracking
- Ignoring small recurring expenses
- Saving only what is left at month-end
- Taking unnecessary loans
- Ignoring emergency funds
- Delaying retirement planning
- Underestimating education costs
- Investing without considering goals and risk
- Not reviewing the family budget regularly
❓ Frequently Asked Questions
Q. How much should a family save every month?
There is no single percentage that works for every family. A practical target should be based on income, expenses, debt, emergency fund requirements and long-term goals.
Q. Should we save or invest first?
Build an appropriate emergency reserve and address important financial protection needs first. Long-term money can then be invested according to the goal, time horizon and risk profile.
Q. How often should we review our family budget?
A monthly review is a good habit. A detailed review can also be done whenever there is a major change in income, expenses, family responsibilities or financial goals.
Q. Is the 50-30-20 rule suitable for every family?
No. It is only a general budgeting framework. Families with high EMIs, young children, irregular income or aggressive financial goals may need a different allocation.
🎯 Key Takeaway
When income, expenses, savings, insurance and investments are planned together, your family can move towards greater financial confidence and long-term financial independence.
🚀 Build a Stronger Financial Future With InvestSathi
Every family has different financial goals. Whether your priority is children’s education, retirement, wealth creation, insurance or investment planning, a structured financial plan can help you make better-informed decisions.
Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial, investment, tax, insurance or legal advice. Investment decisions should be made based on individual financial circumstances, goals, time horizon and risk profile. Market-linked investments are subject to market risks. Past performance does not guarantee future results.