Personal Finance: Complete Guide to Managing Your Money (2026)

Posted on August 24, 2026 by admin

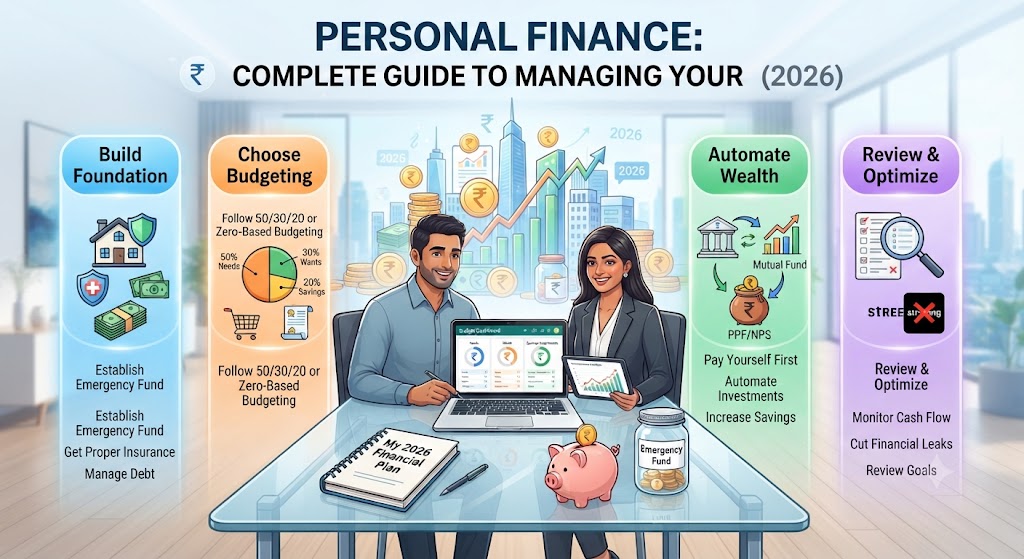
An infographic titled "Personal Finance: Complete Guide to Managing Your (2026)" showing financial pillars like building a foundation, budgeting, automating wealth, and reviewing goals, alongside a man and woman working at a desk.

“`html

πŸ’³ Personal Finance: Complete Guide to Managing Your Money (2026)

Personal Finance ka matlab sirf paisa kamana nahi hai, balki income ko smartly manage karna, expenses control karna, savings banana, debt manage karna aur future financial goals ke liye invest karna bhi hai.

Agar aap apne paison ko proper planning ke saath manage karte hain, toh financial stress kam kiya ja sakta hai aur future ke goals jaise ghar, children’s education, retirement aur wealth creation ko systematically achieve karne mein madad mil sakti hai.

πŸ“– Read Complete Personal Finance Guide

Personal Finance Kya Hai?

Personal Finance ek complete process hai jisme aap apni income, expenses, savings, investments, insurance, loans aur financial goals ko plan aur manage karte hain.

Simple words mein, Personal Finance ka goal hai:
Aaj ki zarooratein poori karna + Kal ke goals ke liye paisa banana + Unexpected risks se protection.

πŸ’‘ Golden Rule: Income badhana important hai, lekin income ko sahi direction mein manage karna usse bhi zyada important hai.


5 Important Pillars of Personal Finance

  • πŸ’° Income Management: Apni income ko properly allocate karein aur unnecessary expenses identify karein.
  • πŸ“Š Budgeting: Har month income aur expenses ka clear plan banayein.
  • πŸ›‘οΈ Risk Protection: Life aur health insurance ke through major financial risks ko manage karein.
  • 🏦 Saving & Investing: Short-term needs ke liye savings aur long-term goals ke liye suitable investments karein.
  • 🎯 Goal Planning: Children’s education, home, retirement aur other financial goals ke liye dedicated planning karein.

Monthly Income Ko Kaise Divide Karein?

Personal finance mein ek fixed formula sabke liye suitable nahi hota. Phir bhi budgeting ke liye ek simple starting framework use kiya ja sakta hai.

Category Indicative Allocation Purpose
Essential Expenses 50–60% Home, food, utilities, EMI etc.
Savings & Emergency Fund 10–20% Financial safety
Investments 15–25% Long-term wealth creation
Discretionary Expenses 10–15% Lifestyle & entertainment

Note: Yeh percentages indicative hain. Actual allocation aapki income, family size, liabilities aur financial goals ke according alag ho sakti hai.


Emergency Fund Kyun Zaroori Hai?

Unexpected situations jaise job loss, medical emergency, urgent repair ya income interruption kabhi bhi aa sakti hain. Isliye ek separate emergency reserve maintain karna important hai.

Aam taur par 3–6 months ke essential expenses ke barabar emergency fund ka target rakha ja sakta hai. Irregular income ya self-employed individuals apni situation ke according larger reserve consider kar sakte hain.

🚨 Emergency Fund ka purpose high returns nahi, balki emergency ke waqt paisa available rakhna hai.


Insurance: Financial Protection Ka First Layer

Savings aur investments important hain, lekin major financial risks ke against protection bhi zaroori hai.

  • ❀️ Term Life Insurance: Earning member ki death ki situation mein family ke financial future ko protect karne mein help kar sakta hai.
  • πŸ₯ Health Insurance: Hospitalisation aur covered medical expenses ke financial impact ko manage karne mein help karta hai.
  • 🏒 Other Insurance: Individual circumstances ke according motor, property, business ya other suitable covers consider kiye ja sakte hain.

Debt Management Kaise Karein?

High-cost debt personal finance ko significantly impact kar sakta hai. Isliye loans aur credit card dues ko systematically manage karna important hai.

  • πŸ’³ Credit card dues ko unnecessarily carry forward na karein.
  • πŸ“‰ High-interest debt ko priority se reduce karne ka plan banayein.
  • 🏠 Home loan jaise long-term loans ko overall financial plan ke saath manage karein.
  • 🚫 Sirf lifestyle expenses ke liye unnecessary loans lene se bachein.

Saving vs Investing

Saving Investing
Short-term needs ke liye useful Long-term wealth creation ke liye useful
Liquidity important hoti hai Risk aur return ko consider karna hota hai
Emergency Fund ka part ho sakta hai Goals aur time horizon ke according choose kiya jata hai
Capital safety priority ho sakti hai Growth potential important hota hai

Financial Goals Kaise Set Karein?

Har financial goal ko clear amount aur time frame ke saath define karna chahiye.

  • πŸŽ“ Child Education: Future education expenses ke liye long-term corpus plan karein.
  • 🏠 Home Purchase: Down payment aur future EMI ko consider karein.
  • πŸš— Major Purchases: Car ya other large purchases ke liye advance planning karein.
  • πŸ–οΈ Retirement: Retirement ke baad expected expenses aur inflation ko consider karke corpus plan karein.
  • πŸ’° Wealth Creation: Long-term goals ke according diversified investment strategy develop karein.

Personal Finance Checklist

  • βœ… Monthly budget ready hai
  • βœ… Emergency Fund build kiya hai
  • βœ… Adequate Life Insurance hai
  • βœ… Health Insurance hai
  • βœ… High-interest debt controlled hai
  • βœ… Regular investments ho rahe hain
  • βœ… Children’s Education ka plan hai
  • βœ… Retirement planning start ki hai
  • βœ… Financial goals regularly review hote hain

Frequently Asked Questions

Q1. Personal Finance planning kab start karni chahiye?
Jitni jaldi aap income, expenses, protection, savings aur investments ko systematically manage karna start karenge, utna zyada time aapko long-term financial goals ke liye mil sakta hai.

Q2. Kya pehle saving karni chahiye ya investing?
Short-term emergencies aur essential reserves ko priority dene ke baad, aap apne goals aur risk profile ke according investing start kar sakte hain. Dono ka role alag hai.

Q3. Salary ka kitna hissa invest karna chahiye?
Iska koi single percentage sabke liye suitable nahi hai. Income, expenses, age, liabilities, family responsibilities aur financial goals ko dekhkar investment amount decide karna chahiye.

Q4. Kya Personal Finance sirf high-income people ke liye hai?
Nahi. Personal Finance har income level ke liye important hai. Limited income mein bhi budgeting, emergency savings, insurance aur disciplined investing financial stability improve karne mein help kar sakte hain.


Key Takeaway

πŸ’° Earn β†’ Budget β†’ Protect β†’ Save β†’ Invest β†’ Grow

Strong Personal Finance ka goal sirf paisa banana nahi, balki paison ko right direction mein use karke financial freedom ki taraf badhna hai.


Get Your Personal Finance Plan Reviewed

Aapki income, expenses, family responsibilities, existing investments, liabilities aur future goals ke according ek personalized financial plan develop kiya ja sakta hai.

InvestSathi ke saath apni financial planning ko review karein aur apne short-term aur long-term goals ke liye suitable strategy par guidance lein.


Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial, investment, tax, or insurance advice. Investment products are subject to market risks. Please consider your financial goals, risk profile and time horizon and review relevant product documents before making investment decisions.

“`
Emergency Fund vs Insurance: What Do You Need First? (2026 Guide)

Posted on by admin

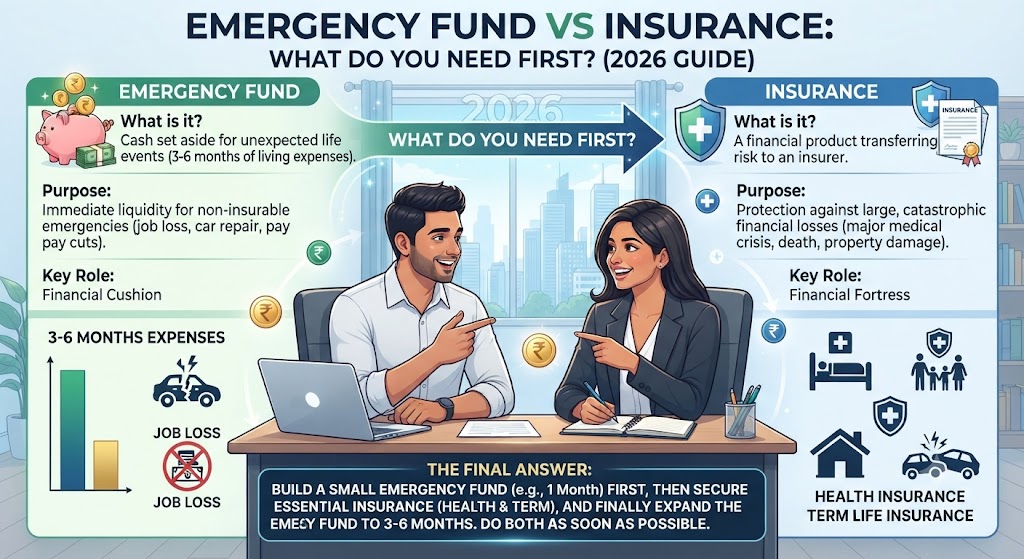
An infographic titled "Emergency Fund vs Insurance: What Do You Need First? (2026 Guide)" comparing the definitions, purposes, and roles of emergency funds versus insurance, with a man and woman discussing at a desk.

“`html

πŸ›‘οΈ Emergency Fund vs Insurance: What Do You Need First? (2026 Guide)

Financial planning mein Emergency Fund aur Insurance dono bahut important hain, lekin dono ka purpose alag hota hai. Emergency Fund aapko achanak aane wale chhote-bade financial emergencies se bachata hai, jabki Insurance bade financial risks se aapke parivar ko protect karta hai.

Lekin sawal yeh hai β€” pehle Emergency Fund banana chahiye ya Insurance lena chahiye? Is guide mein hum samjhenge ki Emergency Fund aur Insurance mein kya difference hai, kitna fund rakhna chahiye aur kis situation mein kiski priority honi chahiye.

πŸ“– Read Complete Emergency Fund vs Insurance Guide

Emergency Fund Kya Hota Hai?

Emergency Fund ek aisa easily accessible financial reserve hota hai jo unexpected situations mein kaam aata hai. Jaise job loss, sudden medical expenses, urgent home repair ya income interruption.

Aam taur par emergency fund mein 3 se 6 months ke essential household expenses ke barabar amount rakhna useful maana jata hai. Self-employed individuals ya irregular income wale logon ko apni situation ke hisaab se isse zyada reserve rakhne ki zarurat ho sakti hai.

πŸ’‘ Golden Rule: Emergency Fund ka purpose investment return kamana nahi, balki zarurat ke waqt paisa available rakhna hai.


Insurance Kya Karta Hai?

Insurance ka primary purpose aise financial risks ko transfer karna hai jo aapki savings ko bahut bada financial loss pahucha sakte hain.

  • ❀️ Life Insurance: Policyholder ki death ki situation mein family ko financial protection provide kar sakta hai.
  • πŸ₯ Health Insurance: Hospitalisation aur covered medical expenses ke financial impact ko reduce kar sakta hai.
  • πŸš— Motor Insurance: Vehicle-related covered risks ke against protection provide karta hai.
  • 🏒 Business Insurance: Business se jude selected risks ko manage karne mein help karta hai.

Emergency Fund vs Insurance

Feature Emergency Fund Insurance
Main Purpose Unexpected expenses ko manage karna Large financial risks se protection
Example Job loss, urgent repair, short-term expense Death, hospitalisation, covered major risks
Money Access Generally easily accessible hona chahiye Policy terms aur claim conditions ke according
Recommended Approach 3–6 months essential expenses ka reserve Risk aur financial responsibilities ke according adequate cover

Emergency Fund Kitna Hona Chahiye?

Emergency Fund calculate karne ke liye sabse pehle apne essential monthly expenses identify karein. Ismein rent/EMI, food, utilities, school fees, insurance premiums aur other essential commitments ko include kiya ja sakta hai.

Monthly Essential Expenses 3 Months 6 Months
β‚Ή30,000 β‚Ή90,000 β‚Ή1.80 Lakhs
β‚Ή50,000 β‚Ή1.50 Lakhs β‚Ή3 Lakhs
β‚Ή75,000 β‚Ή2.25 Lakhs β‚Ή4.50 Lakhs
β‚Ή1,00,000 β‚Ή3 Lakhs β‚Ή6 Lakhs

Pehle Emergency Fund Ya Insurance?

Aksar log sochte hain ki pehle emergency fund complete karne ke baad insurance lena chahiye. Lekin life aur health risks ka wait nahi kiya ja sakta.

βœ… Practical Approach:

  • Sabse pehle essential insurance protection ko ignore na karein.
  • Life insurance ki zarurat hai toh adequate term cover consider karein.
  • Health insurance ko bhi financial protection ka important part samjhein.
  • Saath hi gradually 3–6 months ka Emergency Fund build karein.
  • Emergency Fund ko gradually increase karein jaise income aur family responsibilities badhti hain.

Example: β‚Ή60,000 Monthly Expenses Wala Family

Maan lijiye kisi family ke essential monthly expenses β‚Ή60,000 hain. 6 months ka emergency reserve approximately β‚Ή3.60 Lakhs ho sakta hai.

Lekin agar family ke earning member ke saath koi major life event ho jaye, toh β‚Ή3.60 lakh ka emergency fund long-term family income replacement ke liye sufficient nahi hoga. Isi wajah se Emergency Fund aur Insurance ek-doosre ke alternatives nahi hain.

πŸ›‘οΈ Emergency Fund handles short-term financial shocks.
❀️ Insurance protects against major financial risks.


Common Mistakes to Avoid

  • ❌ Sirf savings ko insurance ka replacement samajhna.
  • ❌ Sirf insurance hone ki wajah se emergency fund ignore karna.
  • ❌ Emergency Fund ko high-risk investments mein rakhna.
  • ❌ Life insurance ka cover sirf premium affordability ke basis par decide karna.
  • ❌ Health insurance ke importance ko ignore karna.
  • ❌ Family responsibilities badhne ke baad financial protection review na karna.

Frequently Asked Questions

Q1. Kya Emergency Fund aur Insurance same cheez hain?
Nahi. Emergency Fund aapke paas available financial reserve hota hai, jabki Insurance specified risks ke against financial protection provide karta hai.

Q2. Emergency Fund kahan rakhna chahiye?
Emergency Fund ka focus liquidity aur capital safety par hona chahiye. Aise options choose karein jahan zarurat ke waqt paisa relatively easily available ho.

Q3. Kya Emergency Fund hone ke baad Life Insurance ki zarurat nahi hai?
Aisa nahi hai. Emergency Fund short-term financial needs ko manage karta hai, jabki adequate life insurance family ke long-term financial protection mein help karta hai.

Q4. Kya Health Insurance bhi zaroori hai?
Health-related expenses family finances par significant impact daal sakte hain. Isliye suitable health insurance ko overall financial protection planning ka important part consider kiya ja sakta hai.


Key Takeaway

πŸ’° Emergency Fund + πŸ›‘οΈ Insurance = Strong Financial Protection

Emergency Fund short-term emergencies ke liye aur Insurance major financial risks ke liye.


Get Your Financial Protection Plan Reviewed

Aapki income, monthly expenses, family responsibilities, loans aur financial goals ke according Emergency Fund aur Insurance ki requirement alag ho sakti hai.

InvestSathi ke saath apni financial protection needs ko review karein aur apne family goals ke according suitable planning par guidance lein.


Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial, investment, or insurance advice. Insurance products are subject to terms, conditions, exclusions, and underwriting guidelines. Please read the relevant policy documents carefully before purchasing any insurance product.

“`

How Much Life Insurance Do You Need? (2026 Guide)

Posted on August 20, 2026 by admin

Family Floater Health Insurance infographic guide 2026 showing benefits, coverage, and comparison with individual plans.

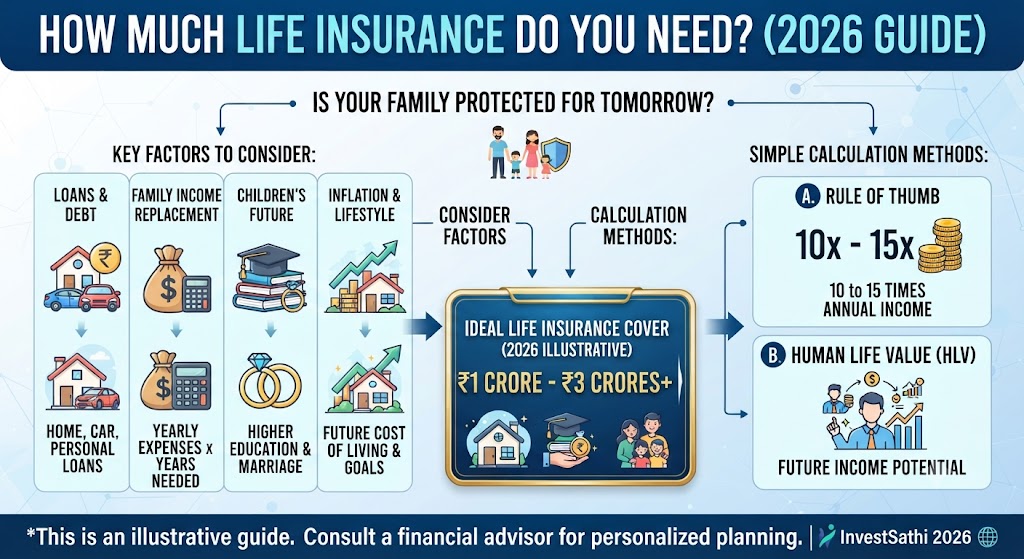
πŸ“Š How Much Life Insurance Do You Need? (2026 Guide)

Term insurance lena toh zaroori hai, lekin sabse bada sawal yeh hota hai ki aakhir kitne ka cover (sum insured) liya jaye? Agar cover kam hoga toh parivar ki zarooratein poori nahi hongi, aur agar zyadatar log andaze se galat amount chun lete hain toh unnecessary high premium bharna padta hai.

Sahi financial planning ke liye yeh samajhna behad zaroori hai ki aapke parivar ke liye ideal life insurance coverage calculate karne ke kaun-kaun se tarike hain aur aapko kin factors ka dhyan rakhna chahiye.

πŸ“– Read Complete Life Insurance Calculation Guide

Methods to Calculate Life Insurance Coverage

Sahi term insurance amount nikalne ke liye mukhyata teen popular methods ka use kiya jata hai:

  • πŸ“ˆ Income Replacement Method: Isme aapki current annual income ko retirement age tak ke bache hue saalo se multiply kiya jata hai, taaki family ko regular income milti rahe.
  • πŸ”’ Human Life Value (HLV) Calculator: Ismein aapki current income, future earning growth, expenses, aur existing savings/investments sabhi ko mathematically calculate kiya jata hai.
  • πŸ’΅ Rule of Thumb (10x to 15x Income): Ek aam formula ke roop mein apni annual income ka 10 se 15 guna (times) tak ka cover liya jata hai. (Jaise agar income 10 Lakh hai, toh 1 Crore ka cover).

πŸ’‘ Golden Rule: Ideal insurance cover wahi hai jo aapke jane ke baad aapke poore parivar ki lifestyle maintain rakhe aur sare loans/liabilities ko zero kar de.


Key Factors to Consider While Deciding Cover

  • 🏠 Outstanding Loans & Liabilities: Ghar ka home loan, car loan ya personal loan hai toh cover amount mein unhe zaroor add karein taaki parivar par loan ka bojh na aaye.
  • πŸ‘Ά Children’s Education & Marriage: Bachon ki higher studies aur future marriages ke liye aane wale kharchon ka anuman lagakar fund plan karein.
  • πŸ“‰ Inflation Rate: Future mein mehangai (inflation) badhegi, isliye aaj ke kharchon ke hisaab se nahi balki future value ke hisaab se cover chunein.
  • πŸ’° Existing Savings & Assets: Aapke paas pehle se kitna mutual fund, FD ya property hai, jise parivar emergency mein use kar sakta hai, use minus karke final cover decide karein.

Comparison: Different Income Brackets & Ideal Cover

Annual Income Rule of Thumb (15x) Recommended Ideal Term Cover
β‚Ή6 Lakhs / Year β‚Ή90 Lakhs β‚Ή1 Crore Cover
β‚Ή10 Lakhs / Year β‚Ή1.5 Crores β‚Ή1.5 to β‚Ή2 Crores Cover
β‚Ή15 Lakhs / Year β‚Ή2.25 Crores β‚Ή2.5 Crores Cover
β‚Ή20 Lakhs+ / Year β‚Ή3 Crores+ β‚Ή3 Crores to β‚Ή5 Crores Cover

Frequently Asked Questions

Q1. Kya housewives ke liye bhi term insurance lena chahiye?
Agar ghar par working member nahi hai toh homemakers ka direct income replacement nahi hota, lekin unke ghar mein diye jaane wale contributions (jaise childcare, management) ki value ko dekhte hue kuch companies ab cover deti hain.

Q2. Kya umar badhne ke sath insurance cover badhana padta hai?
Haan, jaise-jaise shadi hoti hai, bache hote hain aur liabilities (loans) badhte hain, waise-waise apna term insurance cover bhi badhana behtar hota hai. Isliye shuruat mein hi thoda bada cover lena smart choice hai.

Q3. Term insurance kis umar tak ke liye lena chahiye?
Aamtaur par jab tak aapki retirement age (jaise 60 ya 65 years) hoti hai aur jab tak bach financially independent nahi ho jate, tab tak ka term plan lena chahiye.


Key Takeaway

πŸ›‘οΈ Sahi life insurance cover aapke parivar ko kisi bhi unΰ€Ήΰ₯‹oni ke baad financial struggle se bachakar unke sapno ko surakshit rakhta hai.

Accurate Calculation + Adequate Sum Insured = Complete Family Financial Security


Get Your Life Insurance Coverage Calculated

Aapki income, liabilities aur family goals ke hisaab se bilkul sahi term insurance amount nikalne ke liye expert guidance lein.

InvestSathi ke sath apne ideal protection cover ko calculate karke sahi policy select karein.


Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial or insurance advice. Insurance products are subject to terms, conditions, and underwriting guidelines. Please read policy documents thoroughly before purchasing.

Health Insurance Claim Process (2026): Complete Guide

Posted on by admin

Critical Illness Insurance comparison and guide 2026 highlighting lump sum payout, waiting periods, and benefits.

πŸ₯ Health Insurance Claim Process (2026): Complete Guide

Medical emergency ke waqt health insurance policy hona toh zaroori hai hi, lekin us policy ka claim sahi tarike se settle karwana bhi utna hi mahatvapurna hai. Kai baar log sahi process na pata hone ki wajah se cashless ya reimbursement claim ke dauran pareshani mein pad jaate hain.

Sahi financial planning ke liye yeh samajhna behad zaroori hai ki Cashless Claim aur Reimbursement Claim dono kaise kaam karte hain aur emergency mein aapko kya steps lene chahiye.

πŸ“– Read Complete Claim Process Guide

Types of Health Insurance Claims

Health insurance mein mukhyata do tarike se claim settle kiye jaate hain:

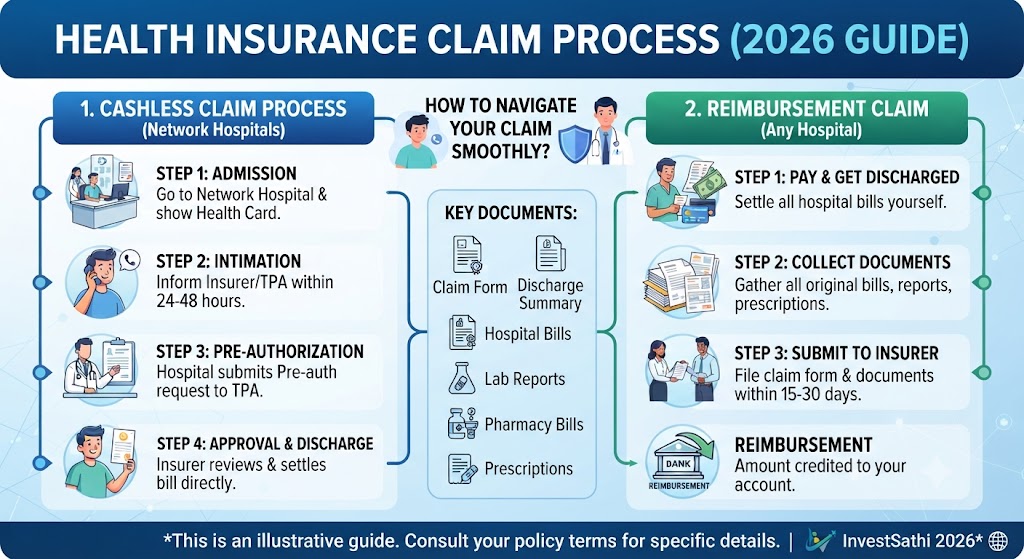
  • πŸ₯ Cashless Claim: Isme aapko hospital mein cash pay nahi karna padta. Insurer sidhe hospital ke bill ka bhugtaan karta hai. Yeh tabhi milta hai jab aap insurance company ke network hospital mein ilaj karwate hain.
  • 🧾 Reimbursement Claim: Agar aap non-network hospital mein ilaj karwate hain ya emergency mein pehle kharcha khud uthate hain, toh bills aur documents submit karke paisa apne bank account mein wapas (reimburse) paate hain.

πŸ’‘ Golden Rule: Cashless claim ke liye hamesha insurer ke network hospital ka chunav karein aur emergency mein TPA desk ko samay par inform karein.


Step-by-Step: Cashless Claim Process

  1. Select Network Hospital:
    Ilaj ke liye hamesha apni insurance company ke list mein shamil network hospital ko hi chunne ki koshish karein.
  2. Inform TPA/Insurer:
    Planned hospitalization hai toh 2-3 din pehle aur emergency hai toh 24 se 48 ghanto ke andar insurance company ya TPA (Third Party Administrator) ko inform karein.
  3. Submit Pre-Authorization Form:
    Hospital ke insurance desk par ID card dikhakar cashless pre-auth form bharein, jise hospital TPA ko bhejta hai.
  4. Approval & Discharge:
    Insurer/TPA dwara documents verify hone ke baad approval mil jata hai, aur discharge ke waqt bill ka direct settlement ho jata hai.

Cashless vs Reimbursement Claim

Feature Cashless Claim Reimbursement Claim
Where Applicable Only at Network Hospitals At any hospital (Network or Non-Network)
Out-of-Pocket Expense Nil (except non-payable items) High initially, paid back later
Paperwork Handled by hospital desk & TPA Gathered and submitted by you
Convenience Highly convenient and stress-free Requires careful tracking of bills & reports

What Documents Are Required for Claims?

  • Claim Form: Dhyan se bhara hua aur signed claim request form.
  • Identity Proof: Patient ka Aadhaar card, PAN card, ya Voter ID.
  • Medical Records: Doctor prescription, admission notes, discharge summary, aur lab test/diagnostic reports.
  • Financial Bills: Original hospital bills, itemized breakup bills, pharmacy cash memos, aur payment receipts.

Frequently Asked Questions

Q1. Agar emergency mein non-network hospital chale jayein toh kya hoga?
Aap emergency mein kisi bhi hospital mein ilaj karwa sakte hain, lekin baad mein sare bills aur documents submit karke reimbursement claim karna hoga.

Q2. Claim reject hone ke kya mukhya karan ho sakte hain?
Pre-existing disease ko chupana, waiting period rules ka poora na hona, ya zaroori documents / bills ki kami hona claim rejection ka karan ban sakta hai.

Q3. Discharge ke kitne din ke andar reimbursement claim karna hota hai?
Aamtaur par discharge hone ke 15 se 30 din ke andar saare original documents ke sath insurance company ko reimbursement ke liye apply karna padta hai.


Key Takeaway

πŸ›‘οΈ Sahi process ki jankari aur waqt par document submission aapke health insurance claim ko 100% successful aur hassle-free banata hai.

Right Hospital + Proper Documentation = Stress-Free Claim Settlement


Need Help with Your Insurance Claims?

Apni policy ke claim process, network hospitals ya best health cover chunne ke liye expert guidance lein.

InvestSathi ke sath apne policy support aur claim assistance ki jankari prapt karein.


Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial or insurance advice. Insurance products are subject to terms, conditions, and underwriting guidelines. Please read policy documents thoroughly before purchasing.

Critical Illness Insurance (2026): Complete Guide

Posted on by admin

Health insurance claim process infographic 2026 showing cashless and reimbursement steps and required documents.

πŸ›‘οΈ Critical Illness Insurance (2026): Complete Guide

Cancer, heart attack, aur kidney failure jaisi gambhir bimariyan achanak aakar na sirf physical health ko balki poori financial savings ko bhi hila kar rakh deti hain. Ek aam health insurance policy hospital ke bills toh cover kar deti hai, lekin ilaj ke dauran income band hone ya expensive medicines ka kharcha uthane ke liye ek Critical Illness Insurance plan ki behad zaroorat hoti hai.

Sahi financial planning ke liye yeh samajhna behad zaroori hai ki critical illness cover kaise kaam karta hai, yeh normal health insurance se kaise alag hai aur aapke liye kyu zaroori hai.

πŸ“– Read Complete Critical Illness Guide

What is Critical Illness Insurance?

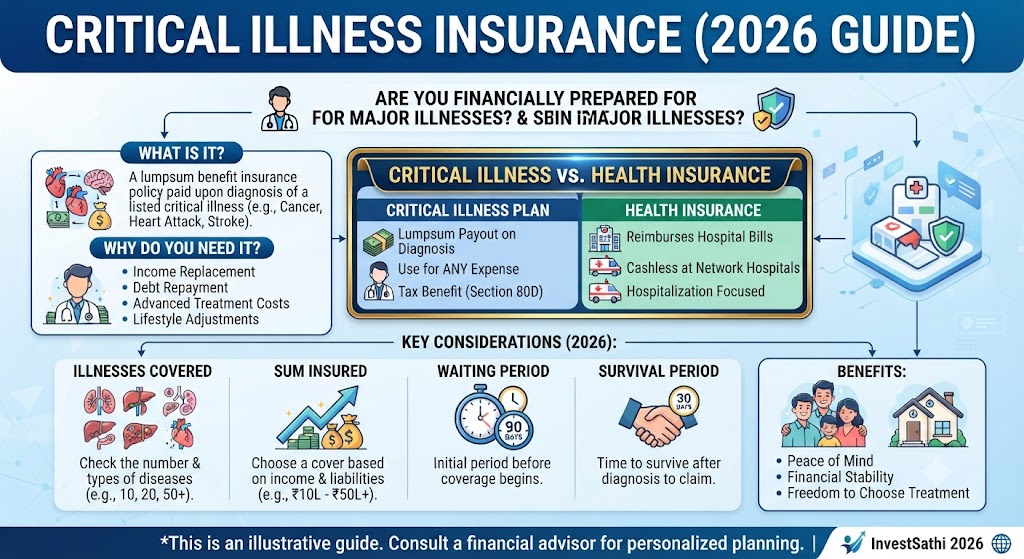
Critical illness insurance ek aisi benefit-based policy hai jo cancer, stroke, major organ transplant, aur paralytic stroke jaisi badi bimariyon ke diagnose hone par lump sum (ek mukt) payout deti hai.

Normal health insurance ke ulat, jisme hospital bills ka reimbursement hota hai, is policy mein diagnosis hote hi poora sum insured sidhe aapke bank account mein bhej diya jata hai, chahe hospital ka kharcha kitna bhi aaye.

πŸ’‘ Golden Rule: Critical Illness cover aapko hospital ke bills se nahi, balki bimari ke dauran income loss aur expensive medical treatments se bachata hai.


Key Benefits of Critical Illness Plans

  • πŸ’° Lump Sum Payout: Bimari diagnose hone par bina kisi bill verification ke poora cash amount ek sath mil jata hai.
  • πŸ’Ό Income Replacement: Ilaj ke dauran agar kaam par nahi jaa paate, toh yeh paisa ghar ke monthly kharche aur EMI chalane mein madad karta hai.
  • πŸ₯ Freedom of Treatment: Aap is paise ko kisi bhi acche hospital, expert doctor ki fees, ya abroad treatment ke liye use kar sakte hain.
  • πŸ’Έ Debt Management: Badi bimari ke waqt existing loans ya personal debts ko chukane ke liye financial stress kam hota hai.
  • πŸ›‘οΈ Tax Savings: Is policy ke premium payment par bhi Income Tax Act ke Section 80D ke tahat tax benefits milte hain.

How Does It Work?

  1. Select a Fixed Sum Insured:
    Aap apni financial liabilities ke hisaab se ek fixed cover chunne hain (jaise 10 Lakhs, 20 Lakhs ya zyada).
  2. Diagnosis of Covered Illness:
    Agar policy term ke dauran list mein shamil koi bhi major critical illness pehli baar diagnose hoti hai.
  3. Claim Settlement & Payout:
    Medical reports submit karne ke baad, insurer bina kisi hospital bill ke poora lump sum amount pay kar deta hai.

Critical Illness Insurance vs Normal Health Insurance

Feature Critical Illness Plan Normal Health Insurance
Payout Type Lump sum cash payout on diagnosis Hospitalisation bill reimbursement/cashless
Primary Focus Income loss & specialized treatment costs Room rent, surgeries & medical bills
Condition Valid only for listed critical illnesses Valid for most general illnesses & accidents
Survival Period Usually requires surviving 30 days post diagnosis No specific survival period clause for bills
Tax Saving Section Section 80D Section 80D

What Should You Check Before Buying?

  • Number of Illnesses Covered: Check karein ki plan mein kitni critical illnesses (jaise 10, 20 ya 64+) cover ho rahi hain.
  • Waiting & Survival Period: Policy shuru hone ke baad initial waiting period (jaise 90 days) aur diagnosis ke baad survival period ke rules kya hain?
  • Policy Exclusions: Pre-existing conditions ya specific exclusions ko dhyan se padhein.
  • >Standalone vs Rider: Kya ise alag se standalone policy ke roop mein lena behtar hai ya existing health/term plan ke sath rider ke taur par?

Frequently Asked Questions

Q1. Kya normal health insurance ke hote hue bhi critical illness lena zaroori hai?
Haan, normal health insurance sirf hospital bills deta hai jabki critical illness plan aapko treatment ke dauran income loss aur ghar ke kharchon ke liye cash deta hai.

Q2. Payout milne ke baad kya policy band ho jati hai?
Aamtaur par ek baar critical illness ka lump sum claim milne ke baad policy terminate ho jati hai, halanki kuch advance plans mein multi-stage claims ki suvidha bhi hoti hai.

Q3. Isme kitne din tak survive karna zaroori hota hai?
Zyadatar policies mein diagnosis ke baad 28 se 30 din tak patient ka survive karna zaroori hota hai tabhi claim payout hota hai.


Key Takeaway

πŸ›‘οΈ Critical Illness Insurance aapko gambhir bimariyon ke financial bojh aur income loss se poori tarah surakshit rakhta hai.

Smart Financial Planning + Critical Cover = Absolute Peace of Mind


Get Your Critical Illness Coverage Review

Aapki family medical history aur financial liabilities ke mutabiq sahi critical illness cover chunne ke liye expert guidance lein.

InvestSathi ke saath apne protection cover ko review karke sahi policy select karein.


Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial or insurance advice. Insurance products are subject to terms, conditions, and underwriting guidelines. Please read policy documents thoroughly before purchasing.