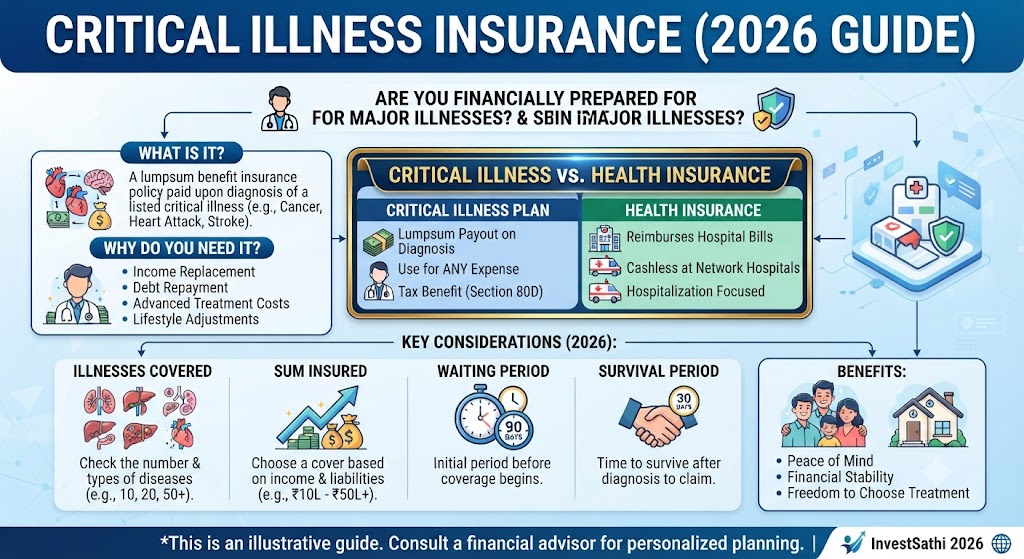
🛡️ Critical Illness Insurance (2026): Complete Guide
Cancer, heart attack, aur kidney failure jaisi gambhir bimariyan achanak aakar na sirf physical health ko balki poori financial savings ko bhi hila kar rakh deti hain. Ek aam health insurance policy hospital ke bills toh cover kar deti hai, lekin ilaj ke dauran income band hone ya expensive medicines ka kharcha uthane ke liye ek Critical Illness Insurance plan ki behad zaroorat hoti hai.
Sahi financial planning ke liye yeh samajhna behad zaroori hai ki critical illness cover kaise kaam karta hai, yeh normal health insurance se kaise alag hai aur aapke liye kyu zaroori hai.
📖 Read Complete Critical Illness Guide
What is Critical Illness Insurance?
Critical illness insurance ek aisi benefit-based policy hai jo cancer, stroke, major organ transplant, aur paralytic stroke jaisi badi bimariyon ke diagnose hone par lump sum (ek mukt) payout deti hai.
Normal health insurance ke ulat, jisme hospital bills ka reimbursement hota hai, is policy mein diagnosis hote hi poora sum insured sidhe aapke bank account mein bhej diya jata hai, chahe hospital ka kharcha kitna bhi aaye.
💡 Golden Rule: Critical Illness cover aapko hospital ke bills se nahi, balki bimari ke dauran income loss aur expensive medical treatments se bachata hai.
Key Benefits of Critical Illness Plans
- 💰 Lump Sum Payout: Bimari diagnose hone par bina kisi bill verification ke poora cash amount ek sath mil jata hai.
- 💼 Income Replacement: Ilaj ke dauran agar kaam par nahi jaa paate, toh yeh paisa ghar ke monthly kharche aur EMI chalane mein madad karta hai.
- 🏥 Freedom of Treatment: Aap is paise ko kisi bhi acche hospital, expert doctor ki fees, ya abroad treatment ke liye use kar sakte hain.
- 💸 Debt Management: Badi bimari ke waqt existing loans ya personal debts ko chukane ke liye financial stress kam hota hai.
- 🛡️ Tax Savings: Is policy ke premium payment par bhi Income Tax Act ke Section 80D ke tahat tax benefits milte hain.
How Does It Work?
-
Select a Fixed Sum Insured:
Aap apni financial liabilities ke hisaab se ek fixed cover chunne hain (jaise 10 Lakhs, 20 Lakhs ya zyada). -
Diagnosis of Covered Illness:
Agar policy term ke dauran list mein shamil koi bhi major critical illness pehli baar diagnose hoti hai. -
Claim Settlement & Payout:
Medical reports submit karne ke baad, insurer bina kisi hospital bill ke poora lump sum amount pay kar deta hai.
Critical Illness Insurance vs Normal Health Insurance
| Feature | Critical Illness Plan | Normal Health Insurance |
|---|---|---|
| Payout Type | Lump sum cash payout on diagnosis | Hospitalisation bill reimbursement/cashless |
| Primary Focus | Income loss & specialized treatment costs | Room rent, surgeries & medical bills |
| Condition | Valid only for listed critical illnesses | Valid for most general illnesses & accidents |
| Survival Period | Usually requires surviving 30 days post diagnosis | No specific survival period clause for bills |
| Tax Saving Section | Section 80D | Section 80D |
What Should You Check Before Buying?
- Number of Illnesses Covered: Check karein ki plan mein kitni critical illnesses (jaise 10, 20 ya 64+) cover ho rahi hain.
- Waiting & Survival Period: Policy shuru hone ke baad initial waiting period (jaise 90 days) aur diagnosis ke baad survival period ke rules kya hain?
- Policy Exclusions: Pre-existing conditions ya specific exclusions ko dhyan se padhein.
- >Standalone vs Rider: Kya ise alag se standalone policy ke roop mein lena behtar hai ya existing health/term plan ke sath rider ke taur par?
Frequently Asked Questions
Q1. Kya normal health insurance ke hote hue bhi critical illness lena zaroori hai?
Haan, normal health insurance sirf hospital bills deta hai jabki critical illness plan aapko treatment ke dauran income loss aur ghar ke kharchon ke liye cash deta hai.
Q2. Payout milne ke baad kya policy band ho jati hai?
Aamtaur par ek baar critical illness ka lump sum claim milne ke baad policy terminate ho jati hai, halanki kuch advance plans mein multi-stage claims ki suvidha bhi hoti hai.
Q3. Isme kitne din tak survive karna zaroori hota hai?
Zyadatar policies mein diagnosis ke baad 28 se 30 din tak patient ka survive karna zaroori hota hai tabhi claim payout hota hai.
Key Takeaway
🛡️ Critical Illness Insurance aapko gambhir bimariyon ke financial bojh aur income loss se poori tarah surakshit rakhta hai.
Smart Financial Planning + Critical Cover = Absolute Peace of Mind
Get Your Critical Illness Coverage Review
Aapki family medical history aur financial liabilities ke mutabiq sahi critical illness cover chunne ke liye expert guidance lein.
InvestSathi ke saath apne protection cover ko review karke sahi policy select karein.
Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial or insurance advice. Insurance products are subject to terms, conditions, and underwriting guidelines. Please read policy documents thoroughly before purchasing.