Financial Freedom Roadmap: A Practical Guide to Financial Independence

Posted on October 27, 2026 by admin

πŸ—ΊοΈ Financial Freedom Roadmap: A Practical Guide to Financial Independence

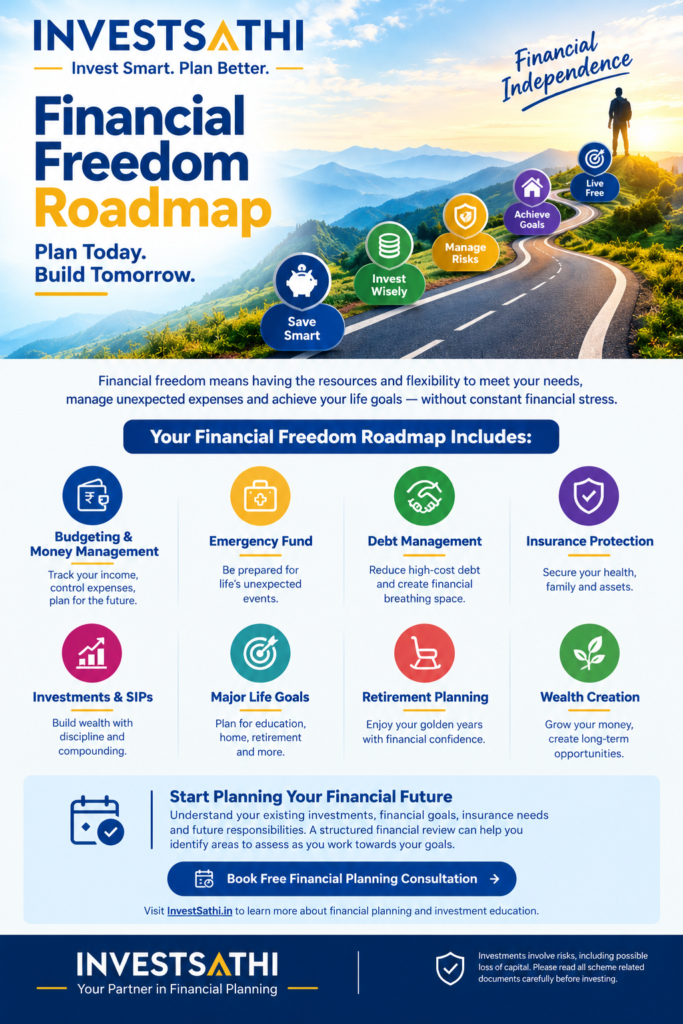
Financial freedom means having the financial resources and flexibility to meet your needs, manage unexpected expenses and work towards your life goals without constant financial stress. It is not necessarily about becoming extremely wealthy. It is about building a financial system that supports your lifestyle, responsibilities and future aspirations.

Whether you are a salaried professional, business owner, young investor or planning for retirement, a structured financial freedom roadmap can help you organise your money, manage risks and make informed financial decisions. The journey begins with understanding your current financial position and creating a realistic plan for the future.

πŸ“š Read the Complete Guide: Your Financial Freedom Roadmap

1. What Is Financial Freedom?

Financial freedom is the ability to manage your money in a way that supports your financial responsibilities and personal goals. It may include being debt-conscious, having emergency savings, maintaining suitable insurance and building investments for future needs.

For some people, financial freedom means buying a home without financial pressure. For others, it means funding their children’s education, becoming financially independent before retirement or having enough resources to make career and lifestyle choices.

Key Principle:

Financial freedom is not just about how much you earn. It also depends on how much you save, how you manage debt, how you protect your family and how consistently you plan for the future.

2. Know Your Current Financial Position

Before creating a roadmap, understand where you stand financially. A clear financial picture helps you identify gaps and decide which priorities need attention first.

  • Income: Calculate your salary, business income and other regular sources of earnings.
  • Expenses: Track household spending, EMIs, bills and discretionary expenses.
  • Assets: List savings, investments, property and other financial assets.
  • Liabilities: Record outstanding loans, credit card balances and other obligations.
  • Protection: Review health insurance, life insurance needs and emergency savings.

Your net worth is calculated by subtracting total liabilities from total assets. Reviewing it periodically can help you understand whether your overall financial position is improving.

3. Create a Monthly Money Management System

A financial plan becomes more practical when you know where your money goes every month. Instead of saving only what remains at the end of the month, consider allocating money towards important priorities as soon as income arrives.

Illustrative Monthly Budget:

Monthly take-home income: β‚Ή80,000
Essential expenses: β‚Ή35,000
Lifestyle and personal expenses: β‚Ή15,000
Savings and investments: β‚Ή20,000
Debt repayment or other financial goals: β‚Ή10,000

Total allocation: β‚Ή80,000

This is only an example, not a recommended allocation for everyone. Your budget should reflect your household responsibilities, debt, income stability and personal goals.

4. Build an Emergency Fund

Unexpected medical expenses, job changes, business interruptions or urgent repairs can disturb even a well-planned financial strategy. An emergency fund provides accessible money for such situations.

Many households use three to six months of essential expenses as an initial reference point. People with irregular business income, dependants or uncertain employment may need a different amount.

  • Estimate your essential monthly expenses.
  • Set a realistic emergency savings target.
  • Keep the money accessible when needed.
  • Replenish the fund after using it for a genuine emergency.

5. Manage Debt Before It Limits Your Future

Debt can reduce the amount of money available for saving and investing. High-interest credit card balances and expensive personal loans may be particularly challenging if they continue to grow.

List your outstanding loans, interest rates, EMIs and repayment dates. Consider prioritising high-interest debt while maintaining essential payments and an appropriate emergency reserve.

Borrowing should be evaluated according to affordability, the purpose of the loan, its cost and its impact on future financial goals. Avoid taking additional debt simply to maintain a lifestyle you cannot comfortably afford.

6. Protect Your Financial Future with Insurance

Financial planning is not complete without considering risks that could affect your family, income or savings. Insurance can help manage specified financial losses, subject to the policy’s terms and exclusions.

  • Health Insurance: Helps cover eligible medical expenses according to the policy.
  • Life Insurance: May provide financial protection to dependants if the insured person dies.
  • Business Insurance: Can address selected business risks, depending on the cover.
  • Asset Protection: Home, vehicle and other relevant insurance can help manage specified risks.

Choose coverage after reviewing your existing policies, dependants, liabilities and financial responsibilities. Insurance requirements vary from person to person.

7. Start Investing According to Your Financial Goals

Saving helps preserve money for future needs, while investing may help build wealth over time. The appropriate investment approach depends on your time horizon, risk tolerance, liquidity requirements and financial circumstances.

  • Mutual Funds: Provide access to professionally managed investment portfolios, with risks depending on the fund.
  • Stocks: Offer ownership in companies but can experience substantial price fluctuations.
  • Fixed Deposits: Offer interest according to the product’s terms and applicable conditions.
  • Bonds: May provide interest income but carry credit, interest-rate and liquidity risks.
  • Exchange-Traded Funds (ETFs): Provide exposure to an index, asset or basket of securities according to their objectives.
  • Retirement Investments: Suitable retirement-oriented products can be considered according to eligibility, tax treatment and individual needs.

No investment product is suitable for everyone. Diversification can help manage concentration risk, but it cannot eliminate losses. Avoid choosing investments only because of recent returns or claims of quick profits.

8. Use SIPs to Build an Investing Habit

A Systematic Investment Plan (SIP) allows you to invest a fixed amount regularly in a mutual fund. It can help create an investing routine that aligns with your monthly income.

For example, you might start with an affordable monthly contribution and review whether it can be increased as your income grows. The contribution should remain consistent with your emergency savings, debt obligations and other financial priorities.

Remember:

A SIP is a method of investing, not a guarantee of returns. The value of a mutual fund investment can rise or fall, and your financial goal may not be achieved.

9. Plan for Major Life Goals

Financial freedom becomes easier to organise when your money is linked to specific goals instead of being invested without a clear purpose.

  • Child Education: Estimate future education costs and start planning early.
  • Home Purchase: Calculate the down payment, loan affordability and related expenses.
  • Retirement: Estimate future living expenses, inflation and expected retirement income.
  • Business Growth: Maintain suitable working capital while separating personal and business finances.
  • Travel and Lifestyle: Create separate savings targets for planned discretionary spending.

Assign each goal a target amount and time horizon. This can help you decide how much to save and which investment risks may be appropriate for that goal.

10. Understand the Impact of Inflation

Inflation reduces the purchasing power of money over time. An amount that comfortably covers your expenses today may not cover the same expenses many years from now.

When planning for education, retirement or other long-term needs, consider how costs may change over time. Review your targets periodically rather than assuming that today’s expenses will remain unchanged.

Investment returns are uncertain, so avoid relying on a single projected return to determine whether your future goals are achievable.

11. Build a Retirement Roadmap

Retirement planning involves estimating how much money you may need when regular employment or business income reduces or stops.

  • Estimate the age at which you want to retire.
  • Calculate expected essential and lifestyle expenses.
  • Consider inflation and healthcare costs.
  • Review existing retirement savings and other assets.
  • Account for possible pensions or other dependable income sources.
  • Review your plan as your circumstances and assumptions change.

A retirement plan should consider both the accumulation phase, when you build assets, and the withdrawal phase, when you use those assets to support your expenses.

12. Avoid Common Financial Planning Mistakes

  • Investing Without Goals: Understand the purpose and time horizon of each investment.
  • Ignoring Emergency Savings: Avoid leaving yourself unprepared for unexpected expenses.
  • Taking Excessive Risk: Do not invest money in unsuitable products simply to seek higher returns.
  • Ignoring Insurance: Review potential financial risks to yourself and your dependants.
  • Following Market Rumours: Base financial decisions on reliable information and your own circumstances.
  • Delaying Planning: Start with manageable steps instead of waiting for the perfect time.
  • Never Reviewing Your Portfolio: Reassess your investments when goals, finances or circumstances change.

13. Your 90-Day Financial Freedom Action Plan

Days 1–30: Understand

  • Calculate your income, expenses, assets and liabilities.
  • Review your existing insurance policies and investments.
  • Identify your three most important financial goals.

Days 31–60: Organise

  • Create a monthly budget.
  • Set an emergency fund target.
  • Prepare a debt repayment plan where needed.
  • Estimate how much you can allocate to each goal.

Days 61–90: Take Action

  • Set up a practical savings routine.
  • Review suitable investment options based on your risk profile.
  • Document your financial goals and target dates.
  • Schedule regular reviews of your financial plan.

14. Review Your Financial Freedom Progress

Financial freedom is a continuing process rather than a one-time achievement. Review your financial position periodically and make adjustments when your income, expenses, responsibilities or goals change.

  • Is your savings rate sustainable?
  • Are you making progress towards your financial goals?
  • Do you have adequate emergency savings?
  • Are your debt levels manageable?
  • Does your insurance reflect your current needs?
  • Are your investments appropriate for your time horizon and risk tolerance?
  • Are your future targets realistic after considering inflation?

Conclusion: Start Your Financial Freedom Journey Today

Financial freedom is built through informed decisions, consistent habits and a financial plan that reflects your own circumstances. You do not need to achieve every goal immediately. Begin by understanding your current position, addressing important risks, managing debt and creating a realistic savings and investment routine.

The objective is not simply to accumulate assets. It is to build a financial foundation that helps you manage responsibilities, prepare for the future and make life decisions with greater financial confidence.

πŸ’Ό Start Planning Your Financial Future

Understand your existing investments, financial goals, insurance needs and future responsibilities. A structured financial review can help you identify areas to assess as you work towards your financial goals.

Visit InvestSathi.in to learn more about financial planning and investment education.


Disclaimer: This article is for educational and informational purposes only. It is not investment advice or a recommendation to buy, sell or hold any financial product or security. Investments involve risks, including possible loss of capital. Mutual funds and equity investments are subject to market risks. Fixed deposits, bonds and insurance products are subject to their respective terms, conditions and risks. Financial decisions should consider your goals, risk tolerance, investment horizon, liquidity requirements, taxation and applicable costs. Consult an appropriately qualified financial professional for guidance specific to your circumstances.
How to Become a Crorepati: A Practical Guide to Wealth Creation in India (2026)

Posted on October 25, 2026 by admin

How to Become a Crorepati – Wealth Creation Through Smart Savings, Investing and Long-Term Financial Planning

“`html

πŸ’° How to Become a Crorepati: A Practical Guide to Wealth Creation in India (2026)

Becoming a crorepati is a financial goal for many Indians. However, building a corpus of β‚Ή1 crore is not simply about earning more money. It involves managing expenses, saving consistently, investing according to your financial goals and allowing time for your investments to grow.

Whether you are a salaried professional, business owner or first-time investor, understanding the principles of wealth creation can help you develop a structured financial plan. There is no guaranteed shortcut to becoming a crorepati, but disciplined financial habits can help you work towards this goal.

πŸ“š Read the Complete Guide: How to Become a Crorepati

1. What Does It Mean to Become a Crorepati?

A crorepati is generally understood as someone whose wealth or assets are worth at least β‚Ή1 crore. However, there is an important difference between having β‚Ή1 crore in assets and having β‚Ή1 crore in net worth.

Net worth is calculated by subtracting your total liabilities from your total assets.

Simple Example:

Total assets: β‚Ή1.20 crore
Outstanding loans: β‚Ή20 lakh
Net worth: β‚Ή1 crore

Your financial goal should consider your liabilities, liquidity needs and long-term purchasing power, not just the amount displayed in an investment account.

2. Set a Clear Financial Goal

Before investing, decide what becoming a crorepati means for you. Your target amount and timeline will influence how much you need to save and invest.

  • Define your target: Decide whether your goal is β‚Ή1 crore in investments or β‚Ή1 crore in total net worth.
  • Set a timeline: Choose a realistic target date based on your income and current savings.
  • Calculate your starting point: Include existing investments and savings that are genuinely available for the goal.
  • Consider inflation: β‚Ή1 crore in the future will not have the same purchasing power as β‚Ή1 crore today.
  • Review your progress: Revisit your plan when your income, expenses or responsibilities change.

3. Start Saving Before Increasing Your Lifestyle

One of the practical steps towards wealth creation is controlling the gap between your income and expenses. When income increases, increasing every expense immediately can make long-term wealth creation difficult.

Track your monthly income, household expenses, EMIs, insurance premiums and discretionary spending. Then decide how much you can consistently allocate towards savings and investments.

Example:

Monthly take-home income: β‚Ή80,000
Monthly expenses: β‚Ή55,000
Potential monthly surplus: β‚Ή25,000

This surplus can be allocated among emergency savings, debt repayment and investments according to your financial priorities.

The example is illustrative. Your appropriate savings amount depends on your family responsibilities, existing debt, income stability and essential expenses.

4. Understand the Power of Compounding

Compounding occurs when investment returns remain invested and may themselves generate returns over time. The effect can become more significant over longer periods, although actual investment returns fluctuate and are not guaranteed.

For example, an investment that earns a positive return may grow through both the original capital and accumulated returns. However, market-linked investments can also lose value, and the sequence of returns affects the outcome.

Starting early can provide more time for compounding, but investors should not choose an investment solely because it has a high projected return.

5. How Much SIP Is Needed to Reach β‚Ή1 Crore?

A Systematic Investment Plan (SIP) allows an investor to invest a fixed amount regularly in a mutual fund. The amount required to reach β‚Ή1 crore depends on the monthly contribution, investment period and actual returns.

The following table provides illustrative estimates using a hypothetical 10% annual return, assumed to compound monthly. It assumes end-of-month investments, no starting balance and no increase in the SIP amount.

Investment Period Approx. Monthly SIP Total Contributions
10 years β‚Ή48,800 β‚Ή58.6 lakh
15 years β‚Ή24,100 β‚Ή43.4 lakh
20 years β‚Ή13,200 β‚Ή31.7 lakh
25 years β‚Ή7,500 β‚Ή22.5 lakh

Figures are rounded estimates based on a mathematical illustration, not a forecast. Actual returns may be higher or lower, and the target may not be achieved. Taxes, fund expenses and other costs are excluded.

Important: A 10% return is an assumption for calculation purposes, not a guaranteed or expected return. Mutual funds are subject to market risks.

6. Choose Investments According to Your Goals

Different financial products serve different purposes. Your choices should reflect your investment horizon, risk tolerance, liquidity needs and financial situation.

  • Mutual Funds: Offer access to professionally managed portfolios. Market-linked funds can fluctuate in value.
  • Stocks: Provide direct ownership in companies but require an understanding of company-specific and market risks.
  • Fixed Deposits: Can provide a predetermined interest rate for a specified tenure, subject to the product’s terms and applicable conditions.
  • Bonds: May provide interest payments, but carry risks such as credit risk, interest-rate risk and liquidity risk.
  • Exchange-Traded Funds: Provide exposure to a basket of securities or an index, depending on the fund’s objective.
  • Insurance: Helps address specified financial risks. Protection needs should be considered separately from investment goals.

No single product is suitable for every investor. Diversification across appropriate asset classes may help manage some risks, but it cannot eliminate investment losses.

7. Crorepati Through SIP vs Lump-Sum Investing

Feature SIP Lump Sum
Contribution Regular instalments One-time investment
Cash Flow Can align with monthly income Requires available capital
Market Exposure Money enters over time Entire amount is invested at once
Risk Depends on underlying investments Depends on underlying investments

Neither method guarantees better results in every market condition. The appropriate approach depends on your available capital, investment horizon, risk tolerance and overall financial plan.

8. Increase Your Investment as Your Income Grows

If your income rises over time, consider increasing your savings and investments instead of allowing expenses to rise at the same pace.

A step-up SIP increases the regular investment amount periodically. For example, an investor may decide to increase their monthly SIP by 5% or 10% annually if income and financial commitments allow.

A higher contribution can help build the invested corpus faster, but the final result still depends on contributions, investment performance, fees and the time invested.

9. Avoid Common Wealth-Building Mistakes

  • Chasing Quick Profits: Avoid decisions based on unrealistic promises or fear of missing out.
  • Ignoring Emergency Savings: Unexpected expenses can force you to sell investments at an unfavourable time.
  • Taking Excessive Debt: High-interest debt can reduce the money available for long-term goals.
  • Concentrating Investments: Relying heavily on a single stock or sector can increase portfolio risk.
  • Ignoring Insurance Needs: An unexpected financial event can disrupt a family’s wealth-building plan.
  • Stopping Investments Due to Market Headlines: Review your goals and portfolio rather than reacting impulsively to every market movement.
  • Ignoring Inflation and Taxes: Consider purchasing power and the effect of applicable taxes and costs.

10. Build an Emergency Fund Before Taking More Risk

An emergency fund can help cover unexpected expenses such as medical costs, job loss or urgent repairs without immediately relying on loans or selling long-term investments.

Many households use three to six months of essential expenses as an initial reference point. The appropriate amount can be higher or lower depending on income stability, dependants, health coverage and other responsibilities.

Emergency savings should generally be accessible and held in options consistent with your liquidity and capital-preservation needs.

11. Review Your Financial Plan Regularly

Wealth creation is an ongoing process. Review your financial position periodically and whenever major life events occur.

  • Check whether your savings rate remains realistic.
  • Review investment performance in the context of your goals and suitable benchmarks.
  • Assess asset allocation and concentration risk.
  • Review outstanding loans and insurance coverage.
  • Update goals when family or career circumstances change.
  • Check whether your target remains realistic after accounting for inflation.

12. A Practical Crorepati Planning Checklist

β˜‘ Define your β‚Ή1 crore goal and target date.

β˜‘ Calculate your current net worth.

β˜‘ Track income, expenses and outstanding loans.

β˜‘ Build an appropriate emergency fund.

β˜‘ Review your insurance and protection needs.

β˜‘ Choose investments based on your goals and risk profile.

β˜‘ Automate regular savings where practical.

β˜‘ Increase contributions when your finances permit.

β˜‘ Diversify appropriately and avoid unrealistic return promises.

β˜‘ Review your plan periodically.

13. Can Everyone Become a Crorepati?

Reaching a β‚Ή1 crore financial target depends on several factors, including income, expenses, savings capacity, investment period, market performance, inflation and financial obligations.

Some people may reach their goal sooner because they have a higher income, existing assets or a longer investment period. Others may need more time or a different target. A realistic plan should reflect your individual circumstances rather than comparisons with other people.

The key is to focus on sustainable financial habits, informed investment decisions and consistent progress instead of searching for a guaranteed shortcut.

πŸ’Ό Start Planning Your Financial Future

Understand your existing investments, financial goals, investment horizon and risk profile. A structured financial review can help you identify areas to assess as you work towards your long-term goals.

Visit InvestSathi.in to learn more about financial planning and investment education.


Disclaimer: This article is for educational and informational purposes only. It is not investment advice or a recommendation to buy, sell or hold any financial product or security. Illustrative calculations are based on assumptions and do not represent guaranteed or expected returns. Mutual fund and equity investments are subject to market risks, including possible loss of capital. Fixed deposits and bonds also carry risks according to their terms and issuer. Investment decisions should consider financial goals, risk tolerance, investment horizon, liquidity requirements, diversification, taxation and applicable costs. Consult an appropriately qualified financial professional for guidance specific to your circumstances.
“`

**SEO Title:** How to Become a Crorepati in India (2026): SIP, Savings & Investment Guide

**Meta Description:** Learn how to become a crorepati in India through financial planning, disciplined savings, SIP investing, diversification and long-term wealth-building strategies.

**Suggested URL Slug:** `how-to-become-a-crorepati`

**Focus Keyword:** How to Become a Crorepati

**Related Keywords:** Crorepati planning, β‚Ή1 crore investment goal, SIP calculator, wealth creation in India, financial planning, long-term investing.

**Featured Image Text:** `HOW TO BECOME A CROREPATI` β€” *Build Wealth with Planning, Discipline & Time*

Blue Chip Stocks Explained (2026)

Posted on October 17, 2026 by admin

Blue Chip Stocks Explained – Benefits, Risks and Investment Guide for 2026

“`html

πŸ“˜ Blue Chip Stocks Explained: A Simple Guide for Investors (2026)

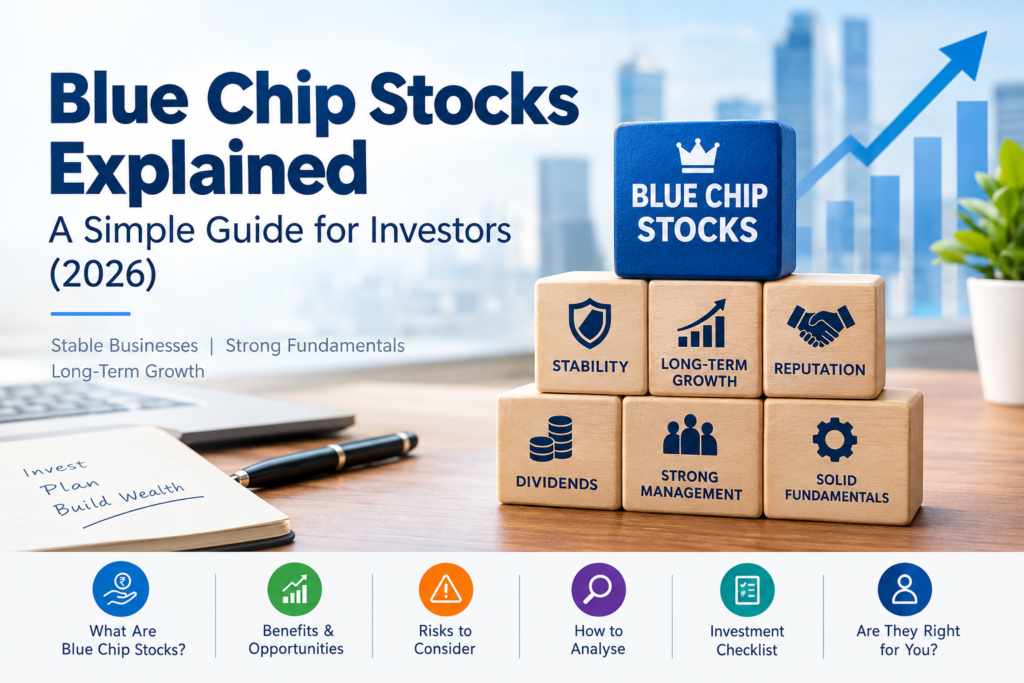
Blue chip stocks are shares of well-established companies that generally have a strong market presence, established business models and a track record of operating through different market conditions. Investors often research these companies when building a long-term stock portfolio.

Understanding company fundamentals, financial performance, valuation, business risks and growth prospects can help investors evaluate whether a blue chip stock fits their financial goals, investment horizon and risk profile.

πŸ“š Read the Complete Guide: Blue Chip Stocks Explained

1. What Are Blue Chip Stocks?

Blue chip stocks are shares of established companies that are generally recognised for their market presence, business reputation, established operations and financial track record.

These companies may operate in sectors such as banking, information technology, consumer goods, energy, healthcare and infrastructure.

Key Point: Blue chip stocks are not risk-free. Their share prices can fall, and past business success does not guarantee future performance or returns.

2. What Are the Characteristics of Blue Chip Stocks?

  • Established Business: The company generally has an established business model and operating history.
  • Market Reputation: It may have a recognised brand and a significant presence in its industry.
  • Financial Performance: Investors examine profitability, cash flows, debt and balance-sheet strength.
  • Experienced Management: Corporate governance and management decisions are important factors.
  • Market Liquidity: Many large established stocks have significant trading activity, although liquidity varies.
  • Dividend History: Some blue chip companies pay dividends, but payments are not guaranteed.

3. Examples of Blue Chip Stocks in India

Investors researching established Indian companies may come across examples such as:

  • Reliance Industries: Energy, retail and digital services.
  • HDFC Bank: Banking and financial services.
  • ICICI Bank: Banking and financial services.
  • Infosys: Information technology services.
  • Tata Consultancy Services (TCS): IT services and consulting.
  • ITC: Consumer products and other businesses.
  • Larsen & Toubro (L&T): Engineering and infrastructure.

These are illustrative examples, not a ranking or a recommendation to buy these stocks. Their financial performance, valuation and investment suitability can change over time.

4. How Do Blue Chip Stocks Work?

When you buy shares of a company, you acquire an ownership interest in that business. Your investment value changes with the market price of the shares.

Investors may potentially earn returns through capital appreciation and dividends, if declared by the company.

Simple Example:

Suppose you purchase 10 shares at β‚Ή1,000 per share.

Initial Investment = 10 Γ— β‚Ή1,000 = β‚Ή10,000

If the share price rises to β‚Ή1,200, the holding value becomes β‚Ή12,000.

Unrealised Gain = β‚Ή12,000 βˆ’ β‚Ή10,000 = β‚Ή2,000, or 20%, before applicable costs and taxes.

If the share price falls, the value of your investment may decline.

5. Blue Chip Stocks vs Mid Cap vs Small Cap Stocks

Feature Blue Chip Mid Cap Small Cap
Business Profile Generally established Medium-sized company Smaller listed company
Growth Potential Depends on business prospects Can offer growth opportunities Can offer growth opportunities
Volatility Can still be volatile May experience higher volatility May experience higher volatility
Risk Market and company-specific risks Market and business risks Market, business and liquidity risks

Blue chip is a market description rather than a formal market-cap classification. Not every large-cap stock necessarily meets every investor’s definition of a blue chip company.

6. Benefits of Blue Chip Stocks

  • Established Companies: Investors can study a longer operating history.
  • Potential Long-Term Growth: Shareholders may benefit if the company’s business and earnings grow.
  • Potential Dividend Income: Some companies distribute dividends to eligible shareholders.
  • Public Information: Financial statements and company disclosures can help investors conduct research.
  • Portfolio Building: Blue chip stocks may form part of a diversified equity portfolio.

7. Risks of Investing in Blue Chip Stocks

Even established companies can face financial difficulties, competition, regulatory changes and declining demand.

  • Market Risk: Share prices may fall during market corrections.
  • Valuation Risk: An expensive stock may deliver disappointing returns even when the business remains strong.
  • Business Risk: Competition and changing industry conditions can affect profits.
  • Management Risk: Poor decisions or weak corporate governance may affect shareholder value.
  • Concentration Risk: Holding only a few stocks can expose a portfolio to company-specific risks.
  • Dividend Risk: Dividends may be reduced or discontinued.
Important: A well-known company is not automatically a good investment at every price. Evaluate its fundamentals, valuation and risks before making an investment decision.

8. How to Analyse a Blue Chip Stock

Investors can review the following factors when researching an individual company:

  • Revenue Growth: Examine the company’s sales trends over time.
  • Profit Growth: Review earnings and operating margins.
  • Debt: Assess borrowing levels and interest obligations.
  • Cash Flow: Understand how much cash the business generates.
  • Return Ratios: Review ROE and ROCE in the context of the industry.
  • Valuation: Examine P/E, P/B and other relevant measures against growth prospects and comparable companies.
  • Corporate Governance: Review management quality and company disclosures.
  • Industry Outlook: Understand competition and long-term business opportunities.

9. Blue Chip Stocks vs Index Funds

A blue chip stock represents ownership in an individual company, while an index fund seeks to track a particular market index by investing according to its methodology.

Feature Blue Chip Stock Index Fund
Investment Individual company shares Tracks a specified index
Diversification Depends on the number of holdings Generally holds multiple index constituents
Research Company-specific research Index composition, costs and tracking
Risk Company-specific and market risks Market and index concentration risks

Both approaches carry investment risks. The appropriate choice depends on the investor’s financial goals, risk tolerance, investment knowledge and overall portfolio.

10. Who May Consider Blue Chip Stocks?

Blue chip stocks may be considered by investors who understand equity-market risks and want exposure to established businesses as part of a long-term investment strategy.

Suitability depends on financial goals, investment horizon, liquidity requirements, risk profile, valuation and diversification. An established company’s shares may not be suitable for every investor.

11. Blue Chip Stock Investment Checklist

β˜‘ Understand the company’s business model

β˜‘ Review revenue and profit growth

β˜‘ Check debt and cash flows

β˜‘ Analyse company valuation

β˜‘ Evaluate management and corporate governance

β˜‘ Understand industry and market risks

β˜‘ Avoid concentrating investments in a few stocks

β˜‘ Consider financial goals and risk tolerance

β˜‘ Review your portfolio periodically

12. Are Blue Chip Stocks Suitable for Long-Term Investors?

Blue chip stocks may play a role in a long-term equity portfolio, but holding a stock for many years does not guarantee a profit.

Investors should periodically review company fundamentals, valuation and portfolio allocation to determine whether their investments continue to align with their financial goals.

πŸ’Ό Want to Review Your Investment Portfolio?

Get a structured review of your existing investments and understand how your portfolio aligns with your financial goals, investment horizon and risk profile.


Disclaimer: This content is for educational and informational purposes only and should not be construed as investment advice, a recommendation to buy or sell any security, or a guarantee of returns. Company examples are illustrative and are not investment recommendations. Equity investments are subject to market risks, including possible loss of capital. Investors should consider their financial goals, risk profile, investment horizon, liquidity requirements, diversification and applicable taxation before making investment decisions. Please consult an appropriately qualified financial professional for advice specific to your circumstances.

“`1px solid #ddd;”>Index, fund costs and tracking

Dividend Investing Guide

Posted on October 4, 2026 by admin

Index Investing Explained: A Simple Guide for Investors (2026)

“`html

πŸ’° Dividend Investing Guide: A Simple Guide for Investors (2026)

Dividend investing is an investment approach where investors consider companies that distribute a portion of their profits to shareholders in the form of dividends. Dividend-paying stocks may provide investors with potential income along with the possibility of capital appreciation.

Understanding dividends, dividend yield, payout ratios, company fundamentals and risks can help investors evaluate whether dividend investing fits their financial goals, investment horizon and risk profile.

πŸ“š Read the Complete Guide: Dividend Investing Explained

1. What Is a Dividend?

A dividend is a distribution made by a company to its shareholders, generally from profits or distributable reserves, subject to applicable laws and company decisions.

Key Point: A dividend is not guaranteed. Companies may increase, reduce, suspend or discontinue dividend payments depending on their financial position, business needs and applicable policies.

2. What Is Dividend Investing?

Dividend investing involves considering shares of companies that have a history or potential of distributing dividends to shareholders.

Investors may consider both the dividend income and the possibility of long-term capital appreciation when evaluating a dividend-paying company.

However, a high dividend yield by itself does not necessarily indicate that a stock is attractive. Investors should also examine the company’s earnings, cash flows, debt, business model and future prospects.

3. How Does Dividend Investing Work?

When a company declares a dividend, eligible shareholders may receive the dividend according to the company’s announced terms and applicable record-date requirements.

Simple Example:
Suppose an investor owns 100 shares of a company and the company declares a dividend of β‚Ή10 per share. The declared dividend amount would be β‚Ή1,000 before considering applicable taxes and other factors.

4. What Is Dividend Yield?

Dividend Yield is a commonly used measure that compares the dividend paid or expected dividend with the share price.

Dividend Yield Formula:

Dividend Yield = Annual Dividend Per Share Γ· Current Market Price Γ— 100

For example, if a company pays β‚Ή20 annual dividend per share and its share price is β‚Ή500:

Dividend Yield = β‚Ή20 Γ· β‚Ή500 Γ— 100 = 4%

Dividend yield can change when the share price changes, even if the company’s dividend remains unchanged.

5. Important Factors to Check Before Investing

  • Dividend History: Review the company’s historical dividend payments and consistency.
  • Dividend Yield: Compare the dividend yield with the company’s fundamentals and sector context.
  • Earnings: Check whether the company’s earnings support the dividend.
  • Cash Flow: Strong and sustainable cash flows can be important when evaluating dividend-paying companies.
  • Debt: High debt levels may affect the company’s ability to distribute dividends.
  • Dividend Payout Ratio: Consider how much of the company’s earnings are being distributed as dividends.
  • Business Quality: Evaluate the company’s competitive position, business model and long-term prospects.

6. What Is Dividend Payout Ratio?

The Dividend Payout Ratio indicates the proportion of earnings that a company distributes as dividends.

Basic Formula:

Dividend Payout Ratio = Dividend Per Share Γ· Earnings Per Share Γ— 100

A very high payout ratio may require additional investigation because the company may have less earnings available for reinvestment, debt reduction or business expansion.

7. Dividend Investing vs Growth Investing

Feature Dividend Investing Growth Investing
Primary Focus Dividend income and business quality Potential business and earnings growth
Income May provide dividend income Income may not be the primary objective
Return Source Dividends + potential capital appreciation Primarily potential capital appreciation
Risk Depends on company and market conditions Depends on company growth expectations and market conditions

8. Benefits of Dividend Investing

  • Potential Income: Dividend-paying investments may provide periodic income.
  • Long-Term Wealth Creation: Reinvesting dividends may contribute to long-term compounding.
  • Business Quality: Dividend analysis can encourage investors to study a company’s profitability and cash flows.
  • Portfolio Income: Dividend-paying investments may be considered as one component of an income-oriented portfolio.
  • Total Return: Investors can evaluate both dividend income and potential capital appreciation.

9. Risks of Dividend Investing

Dividend investing does not eliminate equity-market risk. A dividend-paying stock can decline significantly in value.

  • Dividend Cut Risk: Companies can reduce or stop dividends.
  • Market Risk: Share prices can rise or fall depending on market conditions.
  • Business Risk: Weak earnings or cash flows can affect dividend sustainability.
  • Concentration Risk: Investing heavily in a small number of dividend-paying companies can reduce diversification.
  • High-Yield Trap: An unusually high dividend yield may result from a falling share price and should be investigated carefully.
  • Taxation: Dividend income may have applicable tax implications depending on the investor’s circumstances and prevailing tax rules.
Important: A high dividend yield does not automatically mean a stock is a good investment. Investors should evaluate dividend sustainability, business fundamentals, valuation and overall portfolio risk.

10. Dividend Reinvestment and Compounding

Investors who do not need immediate dividend income may consider reinvesting dividends into investments, subject to their financial goals and applicable rules.

Over a long investment horizon, reinvested income can potentially contribute to the compounding of wealth.

11. Who May Consider Dividend Investing?

Dividend-paying stocks may be considered by investors who are comfortable with equity-market risk and are looking for a combination of potential dividend income and long-term capital appreciation.

The suitability of dividend-oriented investments depends on factors such as the investor’s financial goals, risk profile, investment horizon, liquidity requirements, tax considerations and overall asset allocation.

12. Dividend Investing Checklist

β˜‘ Check the company’s dividend history

β˜‘ Review earnings and cash flows

β˜‘ Analyse dividend payout ratio

β˜‘ Check debt levels

β˜‘ Understand the business model

β˜‘ Avoid choosing a stock only because of high dividend yield

β˜‘ Consider valuation and overall portfolio diversification

β˜‘ Match the investment with your financial goals and risk profile

13. Is Dividend Investing Suitable for Long-Term Investors?

Dividend investing can form part of a long-term investment strategy, but dividend income should not be viewed as guaranteed.

Investors should periodically review the financial health of dividend-paying companies and whether the investment continues to align with their financial goals, risk profile and portfolio strategy.

πŸ’Ό Want to Review Your Investment Portfolio?

Get a structured review of your existing investments and understand how your portfolio aligns with your financial goals, investment horizon and risk profile.


Disclaimer: This content is for educational and informational purposes only and should not be construed as investment advice, a recommendation, or a guarantee of returns. Dividend payments are not guaranteed and may be reduced or discontinued. Equity investments are subject to market risks. Investors should consider their financial goals, risk profile, investment horizon, liquidity requirements and applicable taxation before making investment decisions. Please consult a qualified financial professional for advice specific to your circumstances.

“`

Index Investing Explained: A Simple Guide for Investors (2026)

Posted on September 26, 2026 by admin

Index Investing Explained: A Simple Guide for Investors (2026)

“`html

πŸ“ˆ Index Investing Explained: A Simple Guide for Investors (2026)

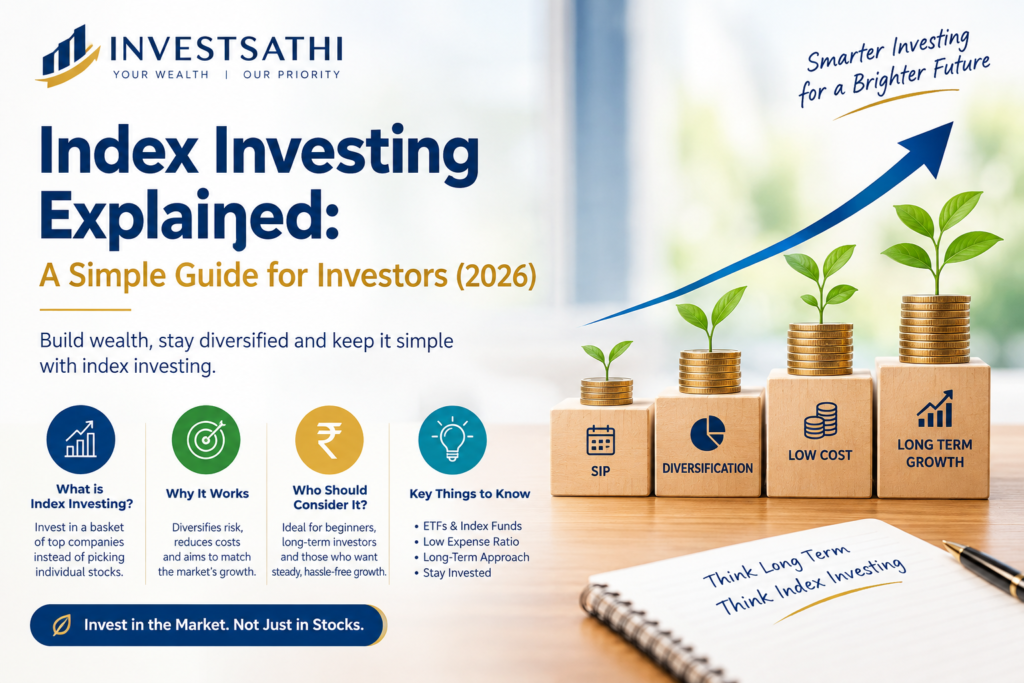
Index investing is an investment approach where investors aim to track the performance of a particular market index instead of trying to select individual stocks or actively outperform the market.

Index investing can be accessed through products such as index mutual funds and exchange-traded funds (ETFs). Understanding how these products work can help investors evaluate whether index investing fits their financial goals, investment horizon and risk profile.

πŸ“š Read the Complete Guide: Index Investing Explained

1. What Is an Index?

A stock market index is a group of selected securities designed to represent a particular segment or portion of the market. An index tracks the performance of its constituent securities according to a defined methodology.

Key Point: An index is a market indicator. Investors cannot directly invest in an index, but they can invest through products designed to track it.

2. What Is Index Investing?

Index investing means investing in a fund or ETF that aims to replicate the performance of a specific market index.

For example, an index fund may seek to track a broad-market index by holding securities in proportions similar to the index methodology.

The objective is generally to provide returns that broadly correspond to the performance of the underlying index, before expenses and tracking differences.

3. How Does Index Investing Work?

An index fund or ETF typically invests in securities that form part of its underlying index. The fund follows the index methodology rather than relying primarily on a fund manager to select individual securities with the objective of outperforming the index.

Simple Example:
If an index contains 50 companies, an index-tracking fund may hold those companies according to the weight assigned by the index methodology.

4. Index Funds vs Active Mutual Funds

Feature Index Fund Active Fund
Approach Tracks an index Manager selects investments
Objective Replicate index performance Seek to outperform a benchmark
Portfolio Changes Generally based on index changes Based on investment decisions
Risk Depends on the underlying index Depends on the fund’s portfolio and strategy

5. What Are the Benefits of Index Investing?

  • Diversification: One index-tracking product can provide exposure to multiple securities.
  • Simple Approach: Investors do not need to select every individual stock themselves.
  • Transparent Strategy: The underlying index and its methodology are generally publicly available.
  • Market Exposure: Investors can obtain exposure to a particular market segment through an index-tracking product.
  • Cost Consideration: Passive funds may have lower operating expenses than some actively managed funds, although costs vary across products.

6. What Are the Risks of Index Investing?

Index investing does not eliminate investment risk. The value of an index fund or ETF can fall when the underlying securities decline in value.

  • Market Risk: The investment value can rise or fall with the underlying market.
  • Tracking Difference: Fund performance may differ from the index because of expenses, cash holdings, transaction costs and other factors.
  • Concentration Risk: Some indices may have significant exposure to particular sectors or companies.
  • Index-Specific Risk: The risk profile depends on the securities and methodology of the underlying index.
Important: Index investing is not risk-free. Past performance of an index or index-tracking product does not guarantee future returns.

7. Index Mutual Funds vs ETFs

Both index mutual funds and ETFs can be designed to track an index, but they operate differently.

Feature Index Mutual Fund ETF
Trading Bought or redeemed through the mutual fund mechanism Traded on a stock exchange
Price Based on applicable NAV Market price during exchange trading
Demat Account Generally not required for direct mutual fund transactions Generally required for exchange trading

8. Who May Consider Index Investing?

Index investing may be considered by investors who want diversified exposure to a particular market index and prefer a passive investment approach.

The suitability of an index fund or ETF depends on factors such as the investor’s financial goals, time horizon, risk profile, liquidity requirements and overall asset allocation.

9. Is Index Investing Suitable for Long-Term Investors?

Index investing can be used as part of a long-term investment strategy. However, the appropriate index and investment product depend on the investor’s circumstances and the objective of the investment.

Investors should understand what an index represents before investing and periodically review whether the investment continues to align with their financial goals.

πŸ’Ό Want to Understand Your Investment Portfolio?

Get a structured review of your existing investments and understand how your portfolio aligns with your financial goals, investment horizon and risk profile.


Disclaimer: This content is for educational and informational purposes only and should not be construed as investment advice, a recommendation, or a guarantee of returns. Gold prices can be volatile and may fall as well as rise. Investors should consider their financial goals, risk profile, investment horizon, liquidity requirements and applicable taxation before making investment decisions. Please consult a qualified financial professional for advice specific to your circumstances.