Retirement Income Planning

Posted on September 8, 2026 by admin

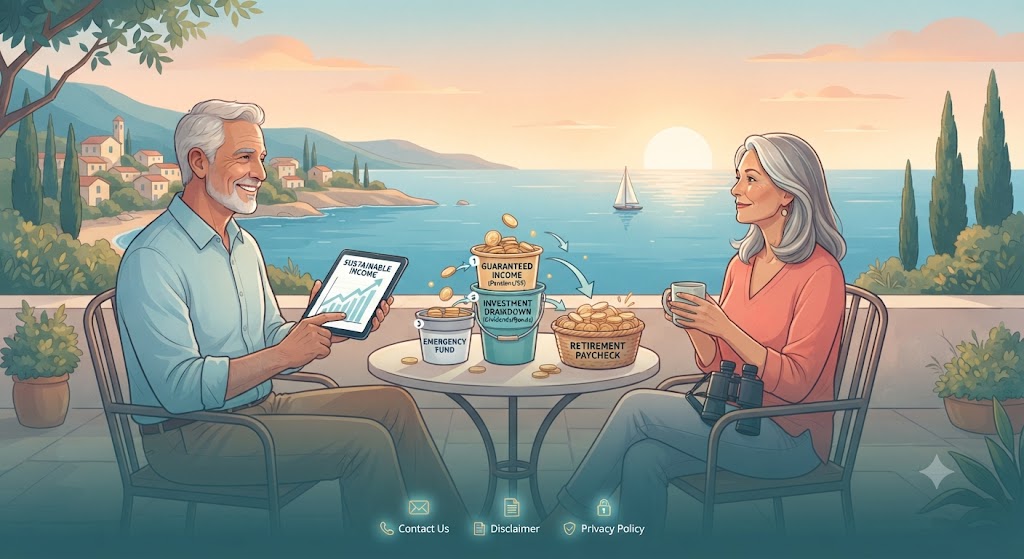
A professional financial chart illustrating retirement income planning, showing steady income streams versus expenses over time.


Retirement Income Planning | The Freedom Blueprint


Retirement Income Planning

Transitioning from accumulating wealth to securing a dependable, sustainable paycheck for life.

For decades, your primary financial focus was accumulation—saving, investing, and watching your nest egg grow. The moment you step into retirement, the game completely changes. The core objective shifts from growth to distribution: turning your accumulated assets into a reliable income stream that will never run out.

1. Map Your Essential vs. Discretionary Expenses

Before withdrawing a single dollar, you need absolute clarity on what retirement actually costs.

  • Essential Baseline: Cover non-negotiables like housing, food, healthcare, utilities, and insurance using guaranteed income sources (pensions, social security, or annuities).
  • Discretionary Fun: Travel, hobbies, and luxury spending can fluctuate depending on market performance and lifestyle choices.

2. Master the Withdrawal Hierarchy (Tax Efficiency)

How you pull money out of your accounts dictates how much you actually get to keep. Smart tax-bracket management can stretch your portfolio by years.

Typically, retirees draw from taxable brokerage accounts first, let tax-deferred accounts (like traditional 401ks/IRAs) grow or use strategic Roth conversions, and pull from tax-free accounts (like Roth IRAs) last.

The Safe Withdrawal Guideline

The traditional rule of thumb suggests withdrawing around 4% of your initial portfolio balance in year one, adjusted annually for inflation. However, modern dynamic withdrawal strategies adjust based on market conditions to prevent early depletion.

3. Build a Multi-Bucket Cash Flow Strategy

Don’t keep all your retirement assets in one vulnerable pool. Structure your funds into temporal buckets:

  1. The Cash Bucket (Years 1–2): Kept in high-yield savings or short-term instruments to fund immediate living expenses without forced selling during market downturns.
  2. The Income Bucket (Years 3–7): Placed in conservative fixed-income assets, bonds, or dividend portfolios to generate steady yields.
  3. The Growth Bucket (Years 8+): Invested in equities and broad-market index funds to outpace inflation and fund the later stages of retirement.

4. Factor in Healthcare and Longevity Risk

People are living longer, healthier lives, which means your retirement plan needs to account for a 30-year time horizon. Couple that with rising medical and long-term care costs, and maintaining a healthcare contingency fund becomes non-negotiable.

Final Thoughts

Retirement income planning isn’t a one-time event; it’s a dynamic system that requires annual check-ins. By structuring your cash flow, managing taxes intelligently, and protecting against market shocks, you ensure true financial peace of mind.

© 2026 Financial Freedom Blog. All rights reserved.


Wealth Building in Your 50s

Posted on by admin

An empowering graphic about wealth building in your 50s, highlighting financial growth, investments, and retirement preparation.


Wealth Building in Your 50s | The Peak Acceleration Blueprint


Wealth Building in Your 50s

The home stretch: Maximizing retirement catch-up contributions, shedding debt, and fine-tuning your exit strategy.

Your 50s are a critical financial bridge. Retirement is no longer a distant concept on the horizon—it’s coming into sharp focus. This decade is all about aggressive final sprints, maximum tax advantages, and shifting from pure accumulation to strategic preservation.

1. Supercharge with Catch-Up Contributions

Government regulations often allow individuals aged 50 and older to contribute extra funds to retirement accounts beyond standard limits.

  • Retirement Accounts: Max out higher annual contribution thresholds for workplace plans (like 401k/403b) and individual IRAs.
  • Empty Nest Dividend: With children often finishing college or moving out, redirect former child-reared expenses straight into your investment portfolio.

2. Relentless Debt Elimination

Entering retirement with heavy debt acts as an anchor on your cash flow. Your goal in your 50s should be absolute financial liberation.

Focus heavily on paying off your primary mortgage or restructuring high-cost liabilities so that your fixed monthly overhead drops significantly before you stop working.

The 50s Milestone Check

Financial experts often recommend having roughly 6 times your annual salary saved by age 50. If you feel behind, use your peak earning capacity and catch-up rules to aggressively bridge the gap over the next 10 to 15 years.

3. Shift from Growth to Preservation & Cash Flow

While you still need growth to fight inflation, you can no longer afford a massive market downturn right before retirement.

  1. The Glide Path: Gradually shift a portion of your portfolio into safer fixed-income assets or dividend-paying stocks to create steady cash flow.
  2. Healthcare Planning: Factor future medical and long-term care costs into your asset projections. Health expenses often make up a large portion of retirement outlays.
  3. Dry Powder: Keep 1–2 years of living expenses in stable, liquid accounts so you aren’t forced to sell stocks during a market correction.

4. Run a Retirement Dry Run

Test-drive your future retirement budget for 3 to 6 months. Live exclusively on the estimated income your portfolio and social security/pension will generate. This reveals hidden spending habits and ensures your plan is realistic.

Final Thoughts

Your 50s require focus, discipline, and intentional planning. By clearing debt, maximizing catch-up limits, and protecting your downside, you pave the way for a secure, stress-free retirement.

© 2026 Financial Freedom Blog. All rights reserved.


Wealth Building in Your 40s

Posted on by admin

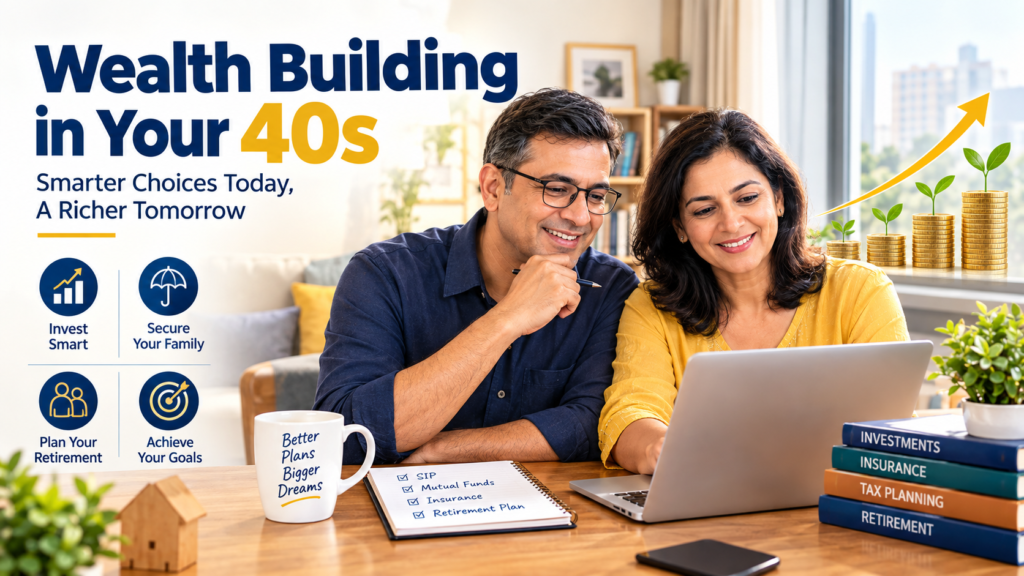
A motivational graphic focused on wealth building in your 40s, highlighting strategic investing, career peak earning years, and financial milestones.


Wealth Building in Your 40s | The Mid-Career Blueprint


Wealth Building in Your 40s

The mid-career power decade to maximize earnings, optimize investments, and secure your financial peak.

Your 40s are often your highest-earning decade, but they also bring unique financial complexities—from peak career responsibilities to raising kids, funding education, and thinking seriously about retirement. It’s the ultimate pivot point for aggressive wealth optimization.

1. Maximize Peak Earning Power

By your 40s, you possess specialized skills and industry experience. This is the time to actively command market value.

  • Career Leverage: Negotiate promotions, pivot into higher-paying leadership roles, or scale a side hustle into a sustainable second stream of income.
  • Avoid Mid-Life Lifestyle Creep: As income peaks, resist the urge to buy larger luxury assets (like oversized homes or expensive cars) that stall net worth growth.

2. Catch-Up Contributions and Tax Strategy

Time is still on your side—with 20+ years until standard retirement, you have a massive runway. However, tax efficiency now matters more than ever.

Take full advantage of catch-up contributions if available through retirement accounts, and look closely at asset location (placing tax-heavy assets in tax-advantaged accounts).

The Mid-Career Milestone Rule

Financial planners generally suggest having roughly 3 times your annual salary saved by age 40. If you are behind, don’t panic—your higher earning capacity in your 40s allows you to aggressively accelerate contributions to close the gap.

3. Balance Growth with Portfolio Protection

You can’t afford to take reckless risks like a 22-year-old, but you can’t afford to be too conservative either, since inflation will eat your savings over a 30-year retirement.

  1. Maintain Equity Exposure: Keep a healthy mix of growth assets (like broad-market index funds) to outpace inflation.
  2. Rebalance Periodically: Review your asset allocation once a year to ensure your portfolio doesn’t drift too heavily into high-risk or low-yield buckets.
  3. Risk Management: Ensure you have robust umbrella insurance, term life insurance, and solid estate planning (wills and trusts) in place to protect your family.

4. Plan for Major Future Expenses

Your 40s frequently coincide with heavy capital outlays: children’s college tuition or helping aging parents. Separate these goals from your core retirement fund so dipping into them doesn’t derail your golden years.

Final Thoughts

Your 40s are the engine room of lifelong financial freedom. By marrying peak income with disciplined investments and intentional tax planning, you set the stage for an extraordinary second half of life.

© 2026 Financial Freedom Blog. All rights reserved.


Wealth Building in Your 20s

Posted on by admin

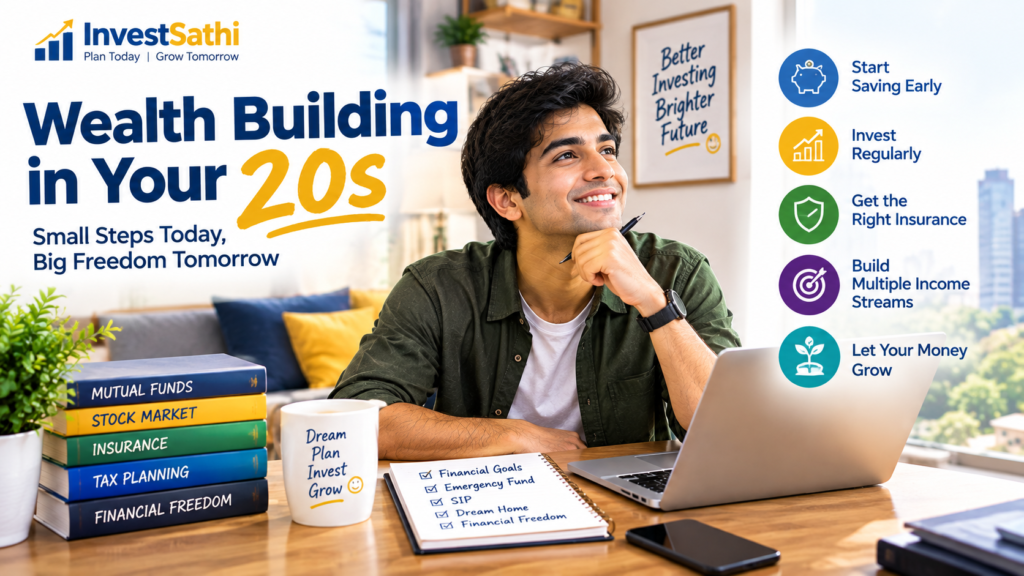
A vibrant graphic about wealth building in your 20s, highlighting early investing, compound interest, and laying a strong financial foundation.


Wealth Building in Your 20s | The Ultimate Guide


Wealth Building in Your 20s

The foundational blueprint to set yourself up for lifelong financial independence.

Your 20s are less about having millions in the bank and more about building the architecture that makes wealth inevitable later in life. Thanks to compound interest, time is your single greatest asset.

1. Build Your Financial Safety Net

Before you chase high investment returns, you need a defense system. Without it, a single emergency can force you into high-interest debt.

  • The Emergency Fund: Save 3 to 6 months of essential living expenses in a high-yield savings account.
  • Insurance Essentials: Secure health insurance early. Relying solely on employer-provided cover is often risky.

2. Destroy High-Interest Debt

Carrying credit card debt or personal loans at 18% to 25% interest rates completely neutralizes any gains you make in the stock market. Attack toxic debt aggressively using the debt avalanche (highest interest first) or debt snowball (smallest balance first) method.

The Power of Starting Early

If you invest $100 a month starting at age 22, compounded at a historical average return, you can accumulate over $1.3 million by age 65. Wait until age 32 to start that exact same habit, and that final number drops by more than half.

3. Master the Core Investment Hierarchy

Keep your strategy boring and automated. Complexity rarely equals better returns.

  1. Employer Match: If your job offers a retirement match (like a 401(k)), contribute enough to get 100% of it. It’s literal free money.
  2. Low-Cost Index Funds: Broad-market index funds or ETFs minimize fees and diversify your portfolio instantly across hundreds of top companies.
  3. Consistency Over Timing: Set up automatic transfers on payday so that investing happens before you have a chance to spend the cash.

4. Defend Against Lifestyle Inflation

As you progress in your career, your salary will naturally increase. The trap most twenty-somethings fall into is upgrading their apartment, car, and dining habits at the exact same rate.

Instead, practice the 50% rule for raises: whenever you get a raise or bonus, commit to saving or investing at least half of the increase while using the rest to upgrade your lifestyle.

Final Thoughts

Your financial journey will constantly evolve, but momentum starts right now. Focus on building repeatable habits, protecting your downside, and letting time do the heavy lifting.

© 2026 Financial Freedom Blog. All rights reserved.


Home Buying Financial Planning: A Complete Guide to Buying Your Dream Home

Posted on September 4, 2026 by admin

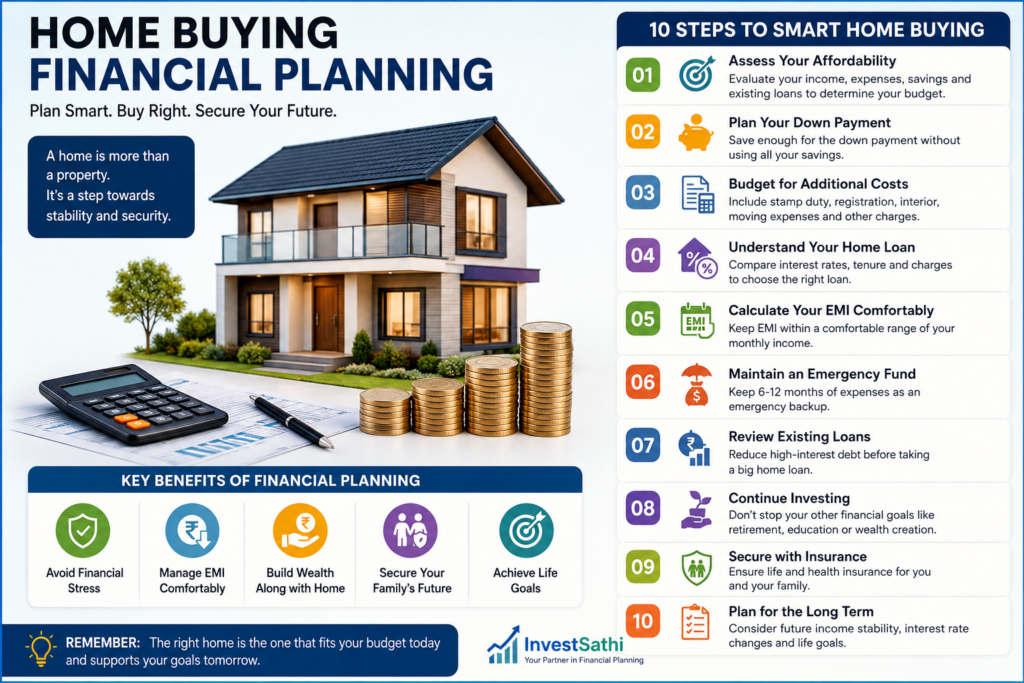
: An infographic titled "Home Buying Financial Planning" featuring a modern house illustration, a 10-step guide for home buyers, and key benefits.

🏠 Home Buying Financial Planning: A Complete Guide to Buying Your Dream Home

Buying a home is one of the biggest financial decisions most people make. A home provides security and stability, but purchasing one without proper financial planning can put significant pressure on your monthly budget.

A well-planned home-buying strategy should cover the down payment, home loan, registration and other purchase costs, monthly EMI, emergency fund and your long-term financial goals.

What Is Home Buying Financial Planning?

Home buying financial planning is the process of determining how much home you can realistically afford and preparing your finances for the purchase without compromising your other important financial goals.

Key Principle:
The right home is not simply the home you can get a loan for. It is the home you can comfortably afford while continuing to manage your other financial responsibilities.

Why Financial Planning Is Important Before Buying a Home

  • Helps determine an affordable property budget.
  • Helps prepare for the down payment.
  • Helps estimate the actual cost of buying a property.
  • Helps keep the home loan EMI manageable.
  • Reduces the risk of excessive borrowing.
  • Protects your emergency fund and other financial goals.

Step 1: Determine How Much Home You Can Afford

Before searching for a property, evaluate your income, regular expenses, existing EMIs, savings and future financial commitments.

Do not determine your property budget only by looking at the maximum loan amount a lender may offer. Your personal affordability should be the starting point.

Step 2: Plan Your Down Payment

A home purchase generally requires the buyer to contribute part of the purchase cost from their own funds. The exact amount depends on the property, lender, loan structure and applicable rules.

Start building your down-payment fund well in advance instead of relying entirely on borrowed money.

Important:
Do not use every rupee of your savings for the down payment. Keep an appropriate emergency reserve and account for other purchase-related expenses.

Step 3: Budget for Additional Home-Buying Costs

The property’s quoted price may not represent the total amount you need to arrange. Depending on the transaction, there can be additional expenses.

Expense Planning Requirement
Down Payment Arrange from your own funds
Stamp Duty & Registration Budget according to applicable local charges
Loan Processing & Related Charges Check lender-specific charges
Interior & Furnishing Estimate separately
Moving Expenses Keep a separate provision
Maintenance / Society Charges Consider ongoing costs

Step 4: Understand Your Home Loan EMI

A home loan can make purchasing a property more manageable, but the EMI becomes a long-term financial commitment.

Before taking a loan, consider the loan amount, interest rate, tenure, processing charges, prepayment conditions and total repayment obligation.

Example:
If you borrow ₹40 lakh for your home, the actual repayment amount will depend on the interest rate and loan tenure. A longer tenure may reduce the monthly EMI but can increase the total interest paid over the life of the loan.

Step 5: Maintain an Emergency Fund

One of the biggest mistakes home buyers make is using all their savings for the property purchase and leaving no cash reserve for emergencies.

Before finalizing the purchase, make sure you have an appropriate emergency fund based on your income, expenses, job stability and family responsibilities.

Step 6: Consider Your Existing Loans

If you already have personal loans, car loans, credit-card balances or other significant liabilities, carefully assess how a new home loan will affect your overall monthly cash flow.

Reducing expensive debt before taking a large long-term loan may improve your financial flexibility.

Step 7: Continue Investing for Other Goals

Buying a home should not automatically mean stopping every other investment.

You may still have important goals such as:

  • Emergency fund
  • Child’s education
  • Retirement
  • Insurance protection
  • Marriage planning
  • Long-term wealth creation

Try to create a balance between your home purchase and these long-term objectives.

Step 8: Start a Home Purchase Fund

If you plan to purchase a home several years from now, create a dedicated home-buying fund.

Regular savings or investments can help you build the required down payment over time. The investment choice should depend on the time available, your risk profile and when the money will be required.

Step 9: Plan for Future Interest Rate Changes

If you choose a floating-rate home loan, your EMI or loan tenure may change when interest rates change, depending on the loan terms.

Therefore, avoid stretching your monthly budget to the maximum limit. Keeping some financial flexibility can make it easier to handle changes in borrowing costs.

Step 10: Check Your Financial Readiness

Before booking a property, ask yourself:

  • Do I have sufficient funds for the down payment?
  • Have I budgeted for registration and other purchase expenses?
  • Can I comfortably manage the expected EMI?
  • Do I have an emergency fund?
  • Do I have adequate insurance protection?
  • Can I continue my important investments?
  • Will the purchase affect my other financial goals?

Home Buying vs Renting: Questions to Consider

Buying a home is not always the only financially sensible option. Your decision should depend on your location, expected stay, income stability, property prices, rent, loan cost and personal preferences.

Buying May Suit You When Renting May Suit You When
You plan to stay for a long period You may relocate frequently
You have stable income Income or location is uncertain
You have sufficient down payment You want greater financial flexibility
The EMI fits comfortably within your budget Buying would create excessive financial pressure

Common Home Buying Mistakes

Mistake Better Approach
Buying beyond your affordability Set a realistic property budget
Using all savings for down payment Maintain an emergency reserve
Ignoring additional costs Prepare a complete purchase budget
Focusing only on EMI Consider total loan repayment cost
Stopping all investments Balance home purchase with other goals

Home Buying Financial Planning Checklist

  • ✔ Define your property requirement
  • ✔ Determine an affordable purchase budget
  • ✔ Build your down-payment fund
  • ✔ Estimate registration and other purchase costs
  • ✔ Compare suitable home-loan options
  • ✔ Calculate the expected EMI
  • ✔ Maintain an emergency fund
  • ✔ Review existing loans and liabilities
  • ✔ Maintain adequate insurance protection
  • ✔ Continue planning for other financial goals
  • ✔ Review your overall financial plan before purchasing

Final Thoughts

Buying a home can be a major step toward financial stability, but it should be approached with careful planning. The goal is not simply to own a property — it is to own a home without putting your overall financial future under unnecessary pressure.

Start early, build your down payment, understand the total cost of ownership, keep your EMI manageable and continue working toward your other important financial goals.

Plan Your Home. Protect Your Future.

Buy a home that fits your life — and a financial plan that protects your future.

InvestSathi – Your Partner in Financial Planning


Disclaimer: The information provided is for educational purposes only and should not be considered financial, legal, tax or investment advice. Home loan interest rates, charges, eligibility criteria and applicable property-related costs may vary by lender, location and individual circumstances. Investment returns are market-linked and not guaranteed. Consult appropriate professionals before making major financial decisions.