Large Cap vs Mid Cap vs Small Cap: What Is the Difference? (2026)

Posted on September 24, 2026 by admin

📊 Large Cap vs Mid Cap vs Small Cap: What Is the Difference? (2026)

When investing in equity mutual funds or stocks, investors often come across terms such as Large Cap, Mid Cap and Small Cap. These categories broadly represent companies based on their market capitalisation and can have different risk, growth and volatility characteristics.

Understanding the differences between Large Cap, Mid Cap and Small Cap can help investors evaluate equity investments according to their financial goals, investment horizon and risk profile.

📚 Read the Complete Guide: Large Cap vs Mid Cap vs Small Cap

1. What Is Market Capitalisation?

Market capitalisation represents the market value of a company’s outstanding shares. It is generally calculated by multiplying the company’s share price by its total outstanding shares.

Key Point: Large Cap, Mid Cap and Small Cap classifications are based on market capitalisation and are commonly used to understand the size segment of companies.

2. What Is a Large Cap Company?

Large Cap companies are companies that rank among the largest companies in the Indian equity market based on market capitalisation, according to the applicable regulatory classification.

These companies are generally more established and may have a longer operating history. However, company size does not eliminate market risk, and the share prices of large companies can also rise or fall significantly.

3. What Is a Mid Cap Company?

Mid Cap companies represent the middle segment of companies based on market capitalisation. They may include businesses that have already achieved a meaningful scale but still have opportunities for expansion.


Disclaimer: This content is for educational and informational purposes only and should not be construed as investment advice, a recommendation, or a guarantee of returns. Gold prices can be volatile and may fall as well as rise. Investors should consider their financial goals, risk profile, investment horizon, liquidity requirements and applicable taxation before making investment decisions. Please consult a qualified financial professional for advice specific to your circumstances.

Gold ETF vs Sovereign Gold Bond – Investment Comparison

Posted on September 23, 2026 by admin

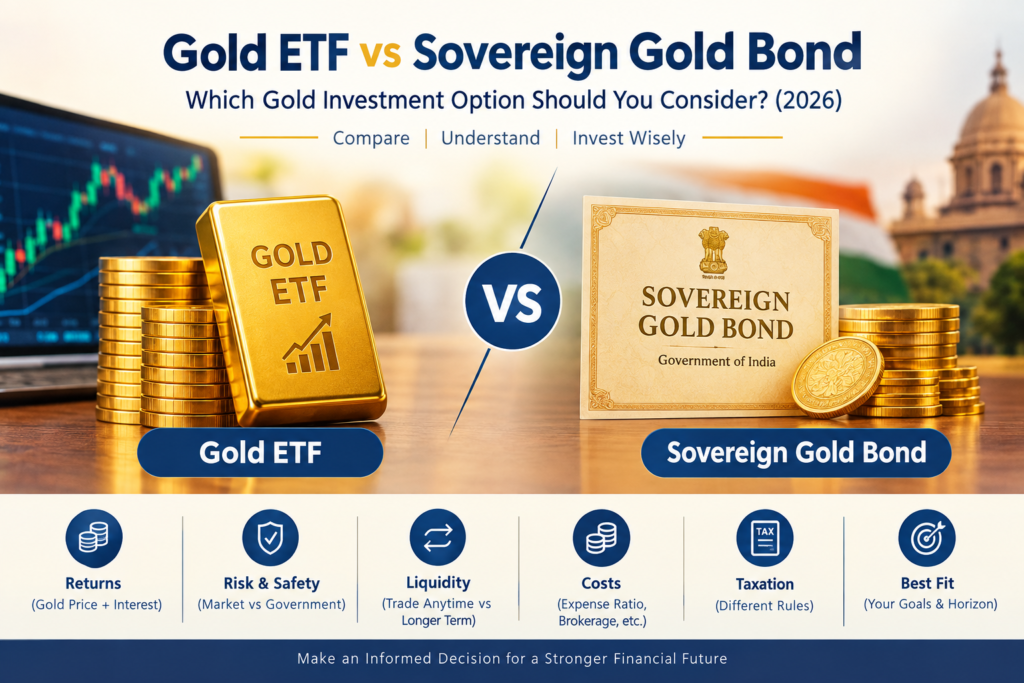
Gold ETF vs Sovereign Gold Bond comparison showing key differences in liquidity, costs, taxation, risk and investment suitability

🪙 Gold ETF vs Sovereign Gold Bond: Which Gold Investment Option Should You Consider? (2026)

Gold has traditionally been considered an important asset for diversification and wealth preservation. Today, investors can gain exposure to gold through multiple options, including physical gold, Gold ETFs and Sovereign Gold Bonds (SGBs).

Among these options, Gold ETFs and Sovereign Gold Bonds have different structures, costs, liquidity features and tax considerations. Understanding these differences can help investors evaluate which option fits their financial goals, investment horizon and liquidity requirements.

📚 Read the Complete Guide: Gold ETF vs Sovereign Gold Bond

1. What Is a Gold ETF?

A Gold ETF (Exchange-Traded Fund) is a market-linked investment product designed to provide investors with exposure to the price of gold. Gold ETFs are traded on stock exchanges and can generally be bought or sold during market hours through a Demat and trading account.

Instead of storing physical gold at home, investors can obtain gold-price exposure through ETF units. The value of a Gold ETF generally moves in line with domestic gold prices, subject to expenses, tracking differences and market conditions.

Key Point: Gold ETFs provide a convenient way to obtain gold-price exposure without directly purchasing and storing physical gold.

2. What Is a Sovereign Gold Bond (SGB)?

A Sovereign Gold Bond (SGB) is a government security denominated in grams of gold. SGBs were introduced as an alternative to holding physical gold and are issued by the Reserve Bank of India on behalf of the Government of India.

The return from an SGB can consist of changes in the applicable gold price along with the fixed interest component specified in the particular issue’s terms and conditions.

SGBs have a specified maturity period and provisions for premature redemption subject to applicable rules. Therefore, they are structurally different from Gold ETFs.


3. Gold ETF vs Sovereign Gold Bond: Key Differences

Parameter Gold ETF Sovereign Gold Bond
Investment Type Exchange-traded fund providing gold-price exposure. Government security linked to the price of gold.
How It Is Bought Through a Demat and trading account on the stock exchange. During applicable SGB issue windows or through permitted secondary-market routes.
Liquidity Can generally be traded during market hours, subject to market liquidity. Has a longer-term structure; secondary-market liquidity may vary.
Interest No fixed interest payment. Eligible bonds carry the fixed interest specified in their issue terms.
Storage No physical storage required. No physical gold storage required.
Price Movement Market price may differ from underlying gold value due to market conditions. Value is linked to the applicable gold price and may trade at a premium or discount in the secondary market.
Investment Horizon Can be suitable where exchange-based liquidity is important. Has a defined maturity structure and may suit investors with a longer investment horizon.

4. Advantages of Gold ETFs

  • Easy Market Access: Gold ETFs can generally be bought and sold through a stock exchange during market hours.
  • No Physical Storage: Investors do not need to store gold jewellery, coins or bars.
  • Portfolio Diversification: Gold can be used as one component of a diversified asset-allocation strategy.
  • Market-Based Pricing: ETF units are traded on the exchange and their market prices are visible during trading hours.
  • Flexible Investment: Investors can purchase ETF units according to their available investment amount, subject to the unit price and trading conditions.

5. Advantages and Features of Sovereign Gold Bonds

  • Government Security: SGBs are issued by the Government of India and administered through the RBI, subject to the terms of the specific issue.
  • Gold-Linked Value: The value of the bond is linked to the applicable gold price.
  • Interest Component: Eligible SGBs carry the fixed interest specified in their issue terms.
  • No Physical Gold: Investors do not have to worry about storing physical gold.
  • Long-Term Structure: SGBs have a specified maturity period, making their structure different from exchange-traded Gold ETFs.

6. Gold ETF vs SGB: What Factors Should You Compare?

There is no single gold investment product that fits every investor. Before investing, consider the following factors:

Investor Requirement What to Consider
Liquidity Consider how easily you may need to buy or sell the investment and the available market liquidity.
Investment Horizon Consider whether your investment horizon matches the product’s structure and redemption provisions.
Costs Compare fund expenses, brokerage, bid-ask spreads and other applicable costs.
Taxation Tax treatment can differ between Gold ETFs and SGBs and may depend on the applicable tax rules and transaction method.
Portfolio Role Consider how gold fits into your overall asset allocation instead of evaluating gold in isolation.

7. Taxation: Why Investors Should Check the Latest Rules

Tax treatment is an important consideration when comparing Gold ETFs and Sovereign Gold Bonds. The applicable tax rules can depend on the investment product, holding period, transfer or redemption method and the tax regime applicable to the investor.

SGB taxation may also differ depending on whether the bond is held until maturity, redeemed through a permitted premature redemption mechanism or sold in the secondary market. Gold ETF taxation can similarly depend on the applicable capital-gains rules.

Important: Tax laws and SGB rules can change. Investors should verify the latest applicable rules before making an investment or redemption decision.

8. Common Mistakes to Avoid When Investing in Gold

  • Investing Only Because Gold Prices Are Rising: Avoid making asset-allocation decisions solely on recent price performance.
  • Ignoring Liquidity: Understand how and where the investment can be sold before investing.
  • Ignoring Costs: Consider expense ratios, brokerage, spreads and other applicable charges.
  • Ignoring Taxation: Understand the tax implications before buying or selling.
  • Over-Concentration: Gold is generally considered one component of a diversified portfolio rather than a complete investment strategy.
  • Not Matching the Product With the Goal: Your investment horizon and liquidity needs should be considered before selecting the product.

9. Gold ETF or SGB: What Should You Evaluate?

Gold ETFs and Sovereign Gold Bonds are different investment structures. The appropriate choice depends on factors such as your investment horizon, liquidity requirement, access to the secondary market, costs, taxation and overall asset allocation.

Instead of asking only “Which is better?”, investors should consider:

  • How long do I plan to remain invested?
  • How easily might I need to exit?
  • What costs will apply?
  • How will the investment be taxed in my situation?
  • What percentage of my overall portfolio should be allocated to gold?

InvestSathi Approach: Gold should be evaluated as part of an overall financial plan and asset-allocation strategy rather than as a standalone investment decision.


10. Gold Investment and Financial Planning

A well-structured financial plan considers multiple asset classes according to an investor’s goals, time horizon, risk profile, liquidity requirements and existing investments.

Before adding gold to your portfolio, review your existing investments and determine whether gold has a meaningful role in your overall asset allocation. Regular portfolio reviews can also help identify concentration and allocation changes over time.


Disclaimer: This content is for educational and informational purposes only and should not be construed as investment advice, a recommendation, or a guarantee of returns. Gold prices can be volatile and may fall as well as rise. Investors should consider their financial goals, risk profile, investment horizon, liquidity requirements and applicable taxation before making investment decisions. Please consult a qualified financial professional for advice specific to your circumstances.

How to Start Investing in Stocks & ETFs: A Beginner’s Guide

Posted on September 21, 2026 by admin

How to Start Investing in Stocks and ETFs for Beginners

📈 How to Start Investing in Stocks & ETFs Explained: A Comprehensive Beginner Guide (2026)

Entering the stock market is one of the most effective ways to grow your savings and build long-term wealth. However, for beginners, navigating between buying individual stocks and investing in Exchange-Traded Funds (ETFs) can feel overwhelming.

This detailed, beginner-friendly guide walks you through the fundamentals of stock investing, how ETFs work, and the exact strategies you need to build a diversified and balanced portfolio.

📚 Read the Complete In-Depth Guide on Stocks & ETFs

1. How to Start Investing in Stocks: Step-by-Step Framework

Successful stock market participation requires a structured strategy rather than random guesses or hot market tips. Follow these key steps to begin your investing journey:

  1. Define Your Financial Goals: Determine why you are investing—whether it’s for retirement, buying a home, or creating an emergency corpus.
  2. Assess Your Risk Tolerance: Understand how much market volatility you can emotionally and financially handle.
  3. Open Brokerage Accounts: Set up a Demat and Trading account with a trusted, SEBI-registered stockbroker.
  4. Establish a Budget: Decide on a fixed monthly or lump-sum amount that you can invest consistently without affecting daily living expenses.
  5. Conduct Fundamental Research: Look at business models, management quality, and financial reports before picking any asset.
Pro Tip for Beginners: Never invest emergency funds or borrowed money into the stock market. Only put in capital that you can comfortably commit for the long haul (3 to 5+ years).

2. What Is an ETF (Exchange-Traded Fund)?

An Exchange-Traded Fund (ETF) is an investment fund traded on stock exchanges, much like individual stocks. It holds a basket of assets—such as stocks, bonds, or commodities—designed to track an underlying index like the Nifty 50 or S&P 500.

When you purchase a single unit of an ETF, you instantly gain fractional ownership in all the companies or securities included in that basket, offering instant market diversification.

ETF Feature What It Means for Investors
Instant Diversification Spreads risk across dozens or hundreds of stocks in a single transaction.
Real-Time Trading Can be bought or sold throughout regular market trading hours at live market prices.
Cost-Efficiency Generally features lower expense ratios compared to actively managed mutual funds.

3. Why Beginners Should Consider ETFs

For individuals just starting out, analyzing individual corporate balance sheets can be time-consuming and prone to human error. ETFs provide distinct advantages:

  • Mitigates Single-Stock Risk: If one company in the ETF performs poorly, other companies in the fund can offset the impact.
  • Passive Management: Eliminates the stress of tracking daily news cycles for individual companies.
  • Broad Market Exposure: Allows you to invest directly in top-tier market indexes without needing massive capital to buy shares of every single component company.

4. Detailed Comparison: Individual Stocks vs. ETFs

Parameter Individual Stocks ETFs (Exchange-Traded Funds)
Ownership Scope Direct ownership of shares in a specific company. Indirect ownership of a diversified basket of assets.
Risk Profile Higher volatility and company-specific risk. Balanced volatility due to built-in diversification.
Time Commitment Requires extensive research, quarterly earnings review, and constant monitoring. Low maintenance; ideal for passive, long-term investors.
Growth Potential Potential for high outperformance, but carries higher downside risk. Tracks broader market performance with steady, predictable alignment.

5. Essential Research Framework for Selecting Stocks

If you choose to buy individual stocks alongside ETFs, always evaluate companies based on these core financial metrics:

  • Revenue & Profit Trends: Consistent, year-over-year revenue growth points to a healthy business model.
  • Debt-to-Equity Ratio: Lower debt ensures the company can weather economic downturns easily.
  • Management Integrity: Review corporate governance records, promoter holdings, and past execution track records.
  • Valuation Metrics: Look at ratios like Price-to-Earnings (P/E) to check if the stock is reasonably priced or overvalued.

6. Common Investment Mistakes Beginners Must Avoid

  • Chasing Social Media Tips: Buying assets purely based on unverified tips or market hype.
  • Panic Selling: Exiting positions prematurely during temporary market corrections.
  • Over-Concentration: Putting all your money into a single stock or sector.
  • Neglecting Costs: Ignoring brokerage fees, expense ratios, and tax implications on short-term gains.
Important Warning: All stock market investments are subject to market risks. Past returns do not guarantee future performance. Ensure your asset allocation matches your overall risk appetite.

Disclaimer: This content is for educational and informational purposes only and should not be construed as professional financial or investment advice. Consult a certified financial planner before executing any financial decisions.

Stock Market Basics Stock Market for Beginners

Posted on by admin

Stock Market Basics – Stock Market for Beginners, featuring a financial market chart, candlestick graph, Indian rupee symbol, and beginner-friendly investing concept.

📈 Stock Market Basics: Stock Market for Beginners (2026)

The stock market can be a powerful way to participate in the growth of businesses and build long-term wealth. However, for beginners, terms such as shares, stocks, demat accounts, trading accounts, NSE, BSE, market capitalization and risk can initially seem confusing.

This beginner-friendly guide explains the basics of the stock market in simple language and helps you understand how stock investing works, how to get started, and what factors you should consider before investing.

📚 Read the Complete Stock Market Beginner Guide

1. What Is the Stock Market?

The stock market is a marketplace where shares of publicly listed companies can be bought and sold. When you purchase shares of a company, you become a shareholder and own a small portion of that company.

Companies can raise capital by issuing shares to investors. Investors may benefit if the value of their investments increases or if the company distributes dividends, although neither outcome is guaranteed.

Simple Example:
If a company has 10 lakh shares and you own 1,000 shares, you own a small portion of that company. The value of your investment will generally change as the market price of the shares changes.

2. What Is a Share?

A share represents a unit of ownership in a company. Companies issue shares to raise capital, and these shares can be traded on a stock exchange after listing.

For example, if you buy 50 shares of a listed company, you own 50 shares of that company. The market value of your investment depends on the current market price of those shares.


3. How Does the Stock Market Work?

Stock prices are influenced by demand and supply in the market. When more investors want to buy a particular stock than sell it, its price may rise. When selling pressure is stronger, the price may fall.

Stock prices can also be affected by factors such as company performance, earnings, economic conditions, interest rates, industry developments, investor expectations and market sentiment.

Factor Possible Impact
Company Earnings Can influence investor expectations and valuation
Economic Conditions Can affect businesses and overall market sentiment
Interest Rates Can influence borrowing costs and investment decisions
Demand and Supply Directly influences market prices

4. What Is a Demat Account?

A Demat account is used to hold securities such as shares in electronic form. When you purchase shares, they are generally credited to your Demat account after settlement.

5. What Is a Trading Account?

A trading account allows you to place buy and sell orders for securities through a stockbroker. In simple terms, the trading account is used for transactions, while the Demat account is used to hold securities electronically.

Account Main Purpose
Demat Account Holds securities electronically
Trading Account Used to buy and sell securities

6. What Are NSE and BSE?

NSE (National Stock Exchange) and BSE (BSE Ltd.) are major stock exchanges in India where securities listed on the exchanges can be traded.

The Nifty 50 is a major index associated with NSE, while the Sensex is a major index associated with BSE. Stock market indices are used to represent the performance of a selected group of stocks.

Important: An index is not the same as an individual stock. It represents a basket or group of securities selected according to the index methodology.

7. Types of Stocks Based on Market Capitalization

Companies are often classified according to their market capitalization. For beginners, understanding large-cap, mid-cap and small-cap companies can help provide basic context when researching stocks.

Category General Description
Large Cap Generally represents larger and more established companies
Mid Cap Generally represents companies between large-cap and small-cap segments
Small Cap Generally represents smaller companies with potentially different growth and risk characteristics

8. What Is Stock Market Risk?

Stock market investments are subject to market risk. Stock prices can rise or fall, sometimes significantly, and an investor can lose part or all of the money invested in a particular stock.

Risk can arise from company-specific factors as well as broader economic, industry and market conditions.

Remember: Past performance does not guarantee future results. Avoid making investment decisions only because a stock has performed well in the past.

9. Investing vs Trading

Investing and trading are different approaches to participating in the stock market.

Investing Trading
Usually focuses on a longer time horizon Usually focuses on shorter-term price movements
Often involves studying business fundamentals May involve technical analysis and market movements
Focus may be on long-term wealth creation Focus may be on shorter-term opportunities and risk management

10. How to Start Investing in Stocks

If you are a beginner, consider following a structured process instead of investing based on market tips or emotions.

  1. Set clear financial goals.
  2. Understand your risk tolerance.
  3. Open a Demat and trading account with a suitable intermediary.
  4. Learn the basics of the companies you are considering.
  5. Review financial statements and business fundamentals.
  6. Understand valuation and the risks involved.
  7. Avoid investing money that you may need for immediate expenses.
  8. Review your portfolio periodically.

11. How to Research a Stock?

Before investing in an individual stock, investors can review several factors to understand the company and its financial position.

Area to Research What to Look At
Business What the company does and how it generates revenue
Revenue & Profit Growth, profitability and consistency
Debt Debt levels and ability to manage obligations
Valuation Whether the market price appears reasonable relative to relevant financial metrics
Management Quality, track record and corporate governance information
Industry Competition, regulation and industry trends

12. Common Stock Market Mistakes Beginners Should Avoid

  • Investing only because someone recommended a stock.
  • Expecting guaranteed returns.
  • Investing without understanding the business.
  • Putting all your money into one stock.
  • Making decisions based on fear or greed.
  • Ignoring portfolio diversification.
  • Using money required for short-term financial needs.
  • Following social media tips without independent research.
  • Ignoring the level of risk involved.
  • Trading frequently without understanding the associated risks and costs.

13. How Much Should a Beginner Invest?

There is no single investment amount that is suitable for every investor. The appropriate amount depends on your income, expenses, emergency savings, financial goals, liabilities, time horizon and risk tolerance.

Beginner Tip: Start with an amount you can comfortably invest without affecting your essential expenses and financial commitments.

14. Simple Stock Market Beginner Checklist

Checklist Completed?
I understand what a share is ☐
I understand Demat and trading accounts ☐
I understand that stock prices can fall ☐
I have defined my financial goals ☐
I have considered my risk tolerance ☐
I have researched the investment before buying ☐

15. Frequently Asked Questions

Q1. Can beginners invest in the stock market?
Yes. Beginners can participate in the stock market after understanding how investing works, opening the required accounts and considering their financial goals and risk tolerance.

Q2. Is stock market investment risk-free?
No. Stock market investments are subject to market risk and the value of investments can rise or fall.

Q3. What is the difference between a stock and a share?
The terms are often used interchangeably. A share generally refers to a unit of ownership in a company, while stock can refer more broadly to ownership in one or more companies.

Q4. What is a Demat account?
A Demat account is used to hold securities in electronic form.

Q5. What is a trading account?
A trading account is used to place buy and sell orders for securities through a stockbroker.

📋 Book Free Financial Planning Consultation

Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial, investment, or insurance advice. Insurance products are subject to terms, conditions, exclusions, and underwriting guidelines. Please read the relevant policy documents carefully before purchasing any insurance product.

“`

Financial Goal Setting Guide

Posted on by admin

Person planning financial goals using a digital tablet dashboard and writing a financial roadmap in a notebook.

# How to Master Your Money: The Ultimate Financial Goal Setting Guide

*Published by [Your Name] | Personal Finance*

Setting financial goals is the compass that guides you through the vast landscape of economic choices. Without a clear roadmap, it’s easy to wander aimlessly and wonder where your paycheck went at the end of every month.

In this comprehensive guide, we’ll walk through a step-by-step framework to define, track, and crush your money goals this year.

—

## Step 1: Establish Your Financial Baseline

Before you can plan where you’re going, you need to know where you stand. Pull your last 3 months of bank statements and credit card bills to calculate your precise financial baseline:

* **Total Assets:** Cash, savings accounts, investments, and valuable property.
* **Total Liabilities:** Credit card debt, student loans, car notes, and mortgages.
* **Net Worth:** Total Assets minus Total Liabilities.
* **Monthly Cash Flow:** Your average take-home income minus fixed/variable expenses.

> **Pro Tip:** Don’t guess your baseline numbers. Using real data prevents your savings targets from collapsing in month two.

—

## Step 2: Use the SMART Framework

Vague goals like *”I want to save more money”* rarely work. Transform your aspirations using the **SMART** criteria:

| Letter | Criteria | Example Application |
| :— | :— | :— |
| **S** | Specific | “I want to build an emergency fund.” $\rightarrow$ “Save for a house down payment.” |
| **M** | Measurable | Target an exact amount (e.g., $10,000). |
| **A** | Achievable | Ensure it fits your monthly surplus capability. |
| **R** | Relevant | Aligns with your core values and long-term vision. |
| **T** | Time-bound | Set a strict deadline (e.g., By December 31). |

—

## Step 3: Prioritize Core Financial Buckets

Not all financial goals carry equal weight. Structure your targets sequentially in order of impact:

1. **The Emergency Safety Net:** Aim to secure 3 to 6 months of essential living expenses.
2. **High-Interest Debt Payoff:** Attack toxic debt (like credit cards over 15% APR) using the avalanche or snowball method.
3. **Wealth Building & Retirement:** Consistently direct automated contributions toward tax-advantaged accounts or portfolios.

—

## Step 4: Build Your Execution Plan

A goal without a schedule is just a wish. Lock these recurring review checkpoints into your calendar:

* **Weekly Actions:** Review and categorize transactions; monitor daily discretionary spending.
* **Monthly Actions:** Evaluate savings transfers, review debt milestones, and check buffer limits.
* **Quarterly Actions:** Rebalance investments, review credit scores, and adjust timelines if life changes occur.

—

### Final Thoughts

Financial freedom doesn’t happen overnight, but it *does* happen by design. Pick **one** primary goal from this guide to focus on today, automate your savings process, and watch your momentum compound over time!

***

*What is your number one financial goal for this year? Let us know in the comments below!*