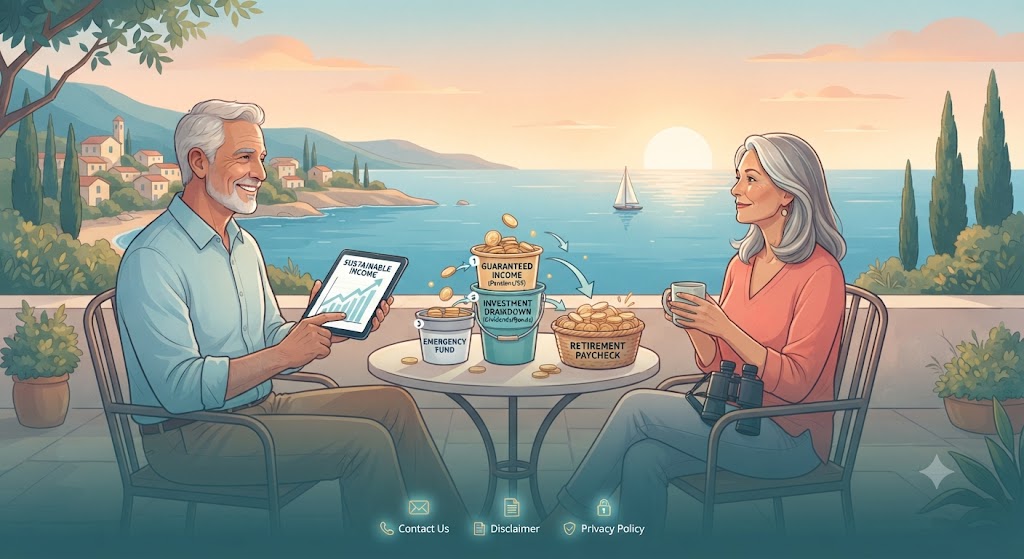
Retirement Income Planning
Transitioning from accumulating wealth to securing a dependable, sustainable paycheck for life.
For decades, your primary financial focus was accumulation—saving, investing, and watching your nest egg grow. The moment you step into retirement, the game completely changes. The core objective shifts from growth to distribution: turning your accumulated assets into a reliable income stream that will never run out.
1. Map Your Essential vs. Discretionary Expenses
Before withdrawing a single dollar, you need absolute clarity on what retirement actually costs.
- Essential Baseline: Cover non-negotiables like housing, food, healthcare, utilities, and insurance using guaranteed income sources (pensions, social security, or annuities).
- Discretionary Fun: Travel, hobbies, and luxury spending can fluctuate depending on market performance and lifestyle choices.
2. Master the Withdrawal Hierarchy (Tax Efficiency)
How you pull money out of your accounts dictates how much you actually get to keep. Smart tax-bracket management can stretch your portfolio by years.
Typically, retirees draw from taxable brokerage accounts first, let tax-deferred accounts (like traditional 401ks/IRAs) grow or use strategic Roth conversions, and pull from tax-free accounts (like Roth IRAs) last.
The Safe Withdrawal Guideline
The traditional rule of thumb suggests withdrawing around 4% of your initial portfolio balance in year one, adjusted annually for inflation. However, modern dynamic withdrawal strategies adjust based on market conditions to prevent early depletion.
3. Build a Multi-Bucket Cash Flow Strategy
Don’t keep all your retirement assets in one vulnerable pool. Structure your funds into temporal buckets:
- The Cash Bucket (Years 1–2): Kept in high-yield savings or short-term instruments to fund immediate living expenses without forced selling during market downturns.
- The Income Bucket (Years 3–7): Placed in conservative fixed-income assets, bonds, or dividend portfolios to generate steady yields.
- The Growth Bucket (Years 8+): Invested in equities and broad-market index funds to outpace inflation and fund the later stages of retirement.
4. Factor in Healthcare and Longevity Risk
People are living longer, healthier lives, which means your retirement plan needs to account for a 30-year time horizon. Couple that with rising medical and long-term care costs, and maintaining a healthcare contingency fund becomes non-negotiable.
Final Thoughts
Retirement income planning isn’t a one-time event; it’s a dynamic system that requires annual check-ins. By structuring your cash flow, managing taxes intelligently, and protecting against market shocks, you ensure true financial peace of mind.