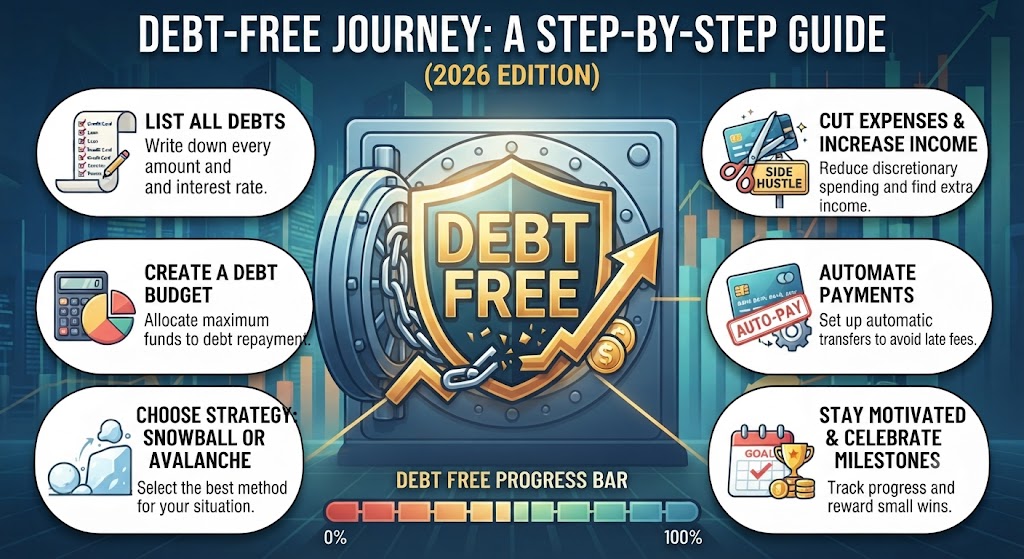
🚀 Debt-Free Journey: A Step-by-Step Guide to Becoming Debt Free (2026)
Debt-free hona sirf loans khatam karne ka goal nahi hai. Yeh ek disciplined financial journey hai jisme aap apni income, expenses, EMIs, savings aur financial goals ko better tarike se manage karte hain.
Agar aap multiple loans, credit card outstanding ya high-interest debt ke pressure mein hain, toh ek structured Debt-Free Journey aapko repayment ko systematically plan karne mein help kar sakti hai.
📖 Read Complete Debt-Free Journey Guide
What Does Being Debt Free Mean?
Debt free ka simple meaning hai ki aapke upar koi outstanding loan ya debt obligation nahi hai. Lekin debt-free journey ka objective sirf loan close karna nahi, balki future mein unnecessary debt dependency ko reduce karna bhi hai.
- 💳 High-interest debt ko reduce karna
- 🏦 Loan obligations ko systematically manage karna
- 💰 Monthly cash flow improve karna
- 🚨 Emergency fund build karna
- 📈 Future savings aur investments ke liye capacity create karna
🎯 Debt-Free Goal = Lower Debt + Better Cash Flow + Stronger Financial Discipline
Step 1 – Apne Saare Debts Ki List Banayein
Debt-free journey ka first step hai ki aapko exactly pata ho ki aap par kitna debt outstanding hai.
| Debt Type | Outstanding | Interest Rate | Monthly EMI |
|---|---|---|---|
| Home Loan | ₹____ | ____% | ₹____ |
| Personal Loan | ₹____ | ____% | ₹____ |
| Credit Card | ₹____ | ____% | ₹____ |
| Other Debt | ₹____ | ____% | ₹____ |
Step 2 – Calculate Your Total Debt
Sabhi outstanding balances ko add karke apna total debt calculate karein.
🧮 Total Debt = All Outstanding Loan & Credit Balances
Total debt ka clear picture milne ke baad repayment journey ko measurable banana easier ho jata hai.
Step 3 – High-Interest Debt Ko Priority Dein
Sabhi debts ki interest cost same nahi hoti. High-interest debt repayment ko priority dena overall borrowing cost ko reduce karne mein helpful ho sakta hai.
- 💳 Credit card outstanding
- 🏦 High-interest personal loans
- 💰 Other expensive unsecured debt
💡 Highest-Cost Debt Ko Identify Karna Debt-Free Journey Ka Important Step Hai.
Step 4 – Debt Snowball vs Debt Avalanche
Debt repayment ke liye do commonly discussed approaches hain: Debt Snowball aur Debt Avalanche.
| Debt Snowball | Debt Avalanche |
|---|---|
| Smallest balance ko pehle target karta hai | Highest interest rate wale debt ko pehle target karta hai |
| Quick wins motivation de sakte hain | Interest cost reduce karne par focus karta hai |
| Behavioural motivation useful ho sakti hai | Mathematically lower interest cost possible ho sakti hai |
Kaunsa method better hai, yeh aapke debt structure, financial behaviour aur personal preference par depend kar sakta hai.
Step 5 – Monthly Debt Repayment Budget Banayein
Apni monthly income aur essential expenses ko review karke decide karein ki debt repayment ke liye realistically kitna additional amount allocate kiya ja sakta hai.
| Monthly Income | Essential Expenses | Existing EMI | Extra Debt Payment |
|---|---|---|---|
| ₹80,000 | ₹40,000 | ₹20,000 | ₹10,000 |
| ₹1,00,000 | ₹50,000 | ₹25,000 | ₹15,000 |
Note: Above examples are illustrative only. Actual debt repayment capacity depends on individual income, expenses and liabilities.
Step 6 – Unnecessary Expenses Reduce Karein
Debt repayment period ke dauran temporary expense control aapko additional repayment capacity create karne mein help kar sakta hai.
- 🍽️ Frequent dining out reduce karein
- 🛍️ Impulse shopping avoid karein
- 📱 Unused subscriptions cancel karein
- ✈️ Non-essential travel postpone karein
- 🎬 Unnecessary entertainment spending review karein
- 💳 New credit card balances avoid karein
💰 Temporary Lifestyle Control Can Create Permanent Financial Progress.
Step 7 – New Debt Lena Avoid Karein
Existing debt repay karte waqt unnecessary new borrowing debt-free journey ko slow kar sakti hai.
- ❌ Unnecessary EMI purchases avoid karein
- ❌ Credit card balance unnecessarily carry na karein
- ❌ Lifestyle upgrades ke liye expensive loans avoid karein
- ❌ Existing debt ko hide karne ke liye repeated borrowing na karein
Step 8 – Emergency Fund Bhi Maintain Karein
Debt repay karte waqt emergency fund ko completely ignore karna risky ho sakta hai. Unexpected expense aane par savings na hone se dobara expensive debt lena pad sakta hai.
Isliye debt repayment ke saath ek suitable emergency reserve build karna bhi financial planning ka important part ho sakta hai.
🚨 Emergency Fund = Protection Against New Debt
Step 9 – Extra Income Ka Smart Use Karein
Salary ke alawa bonus, incentives, freelance income ya other additional cash flow milne par uska ek portion debt repayment ke liye allocate kiya ja sakta hai.
- 💼 Bonus
- 💰 Performance Incentives
- 📈 Additional Business Income
- 🎁 Cash Gifts / Windfalls
- 💼 Side Income
Additional income ka complete amount debt repayment mein dena necessary nahi hai. Apni financial priorities ke according allocation decide karein.
Debt-Free Journey Example
Suppose kisi person par total ₹3,00,000 ka high-cost debt hai aur woh monthly ₹15,000 repayment ke liye allocate karta hai. Simple calculation ke basis par ₹3,00,000 ÷ ₹15,000 = 20 months hota hai.
🧮 Simple Estimate: ₹3,00,000 ÷ ₹15,000 = 20 Months
Important: Actual repayment period interest, EMI structure, fees, prepayments and loan terms ke according different ho sakta hai. Yeh example sirf basic calculation samjhane ke liye hai.
What to Do After Becoming Debt Free?
Debt khatam hone ke baad financial journey stop nahi honi chahiye. Ab wahi monthly cash flow future financial goals ki taraf redirect kiya ja sakta hai.
- 🚨 Emergency Fund strengthen karein
- 🎓 Children’s Education Planning karein
- 🏖️ Retirement Planning start/increase karein
- 🏠 Other Financial Goals ke liye save karein
- 📈 Suitable long-term investments consider karein
- 🛡️ Adequate insurance protection review karein
Common Debt-Free Journey Mistakes
- ❌ Sirf minimum EMI payment par depend karna
- ❌ High-interest debt ko ignore karna
- ❌ New unnecessary loans lena
- ❌ Emergency fund completely ignore karna
- ❌ Expenses track na karna
- ❌ Bonus aur extra income ko completely spend kar dena
- ❌ Debt close hone ke baad lifestyle expenses unnecessarily increase karna
Frequently Asked Questions
Q1. Debt-free hone ka best way kya hai?
Apne saare debts list karein, interest rates aur outstanding balances identify karein, repayment strategy choose karein aur monthly budget ke through systematic repayment karein.
Q2. Pehle kaunsa loan repay karna chahiye?
High-interest debt ko priority dena interest cost reduce karne mein helpful ho sakta hai. Lekin overall strategy individual circumstances par depend karti hai.
Q3. Kya emergency fund banate hue debt repay karna chahiye?
Emergency fund aur debt repayment dono important hain. Exact allocation aapki income stability, debt cost aur financial circumstances par depend karega.
Q4. Kya debt repayment ke liye investments sell karne chahiye?
Har situation mein investments sell karna appropriate nahi hota. Tax impact, exit cost, investment purpose, debt interest cost aur overall financial plan ko consider karke decision lena chahiye.
Q5. Debt-free hone ke baad kya karna chahiye?
Debt repayment ke baad freed-up cash flow ko emergency fund, insurance protection aur long-term financial goals jaise retirement, education aur other investments ki taraf redirect kiya ja sakta hai.
Key Takeaway
📊 Know Your Debt + 💳 Prioritise Repayment + 💰 Control Expenses + 🚨 Build Emergency Fund
Debt-free journey ek overnight process nahi hai. Consistent repayment, disciplined spending aur clear financial goals ke through aap gradually stronger financial position build kar sakte hain.
Start Your Debt-Free Journey
Har person ki income, loans, interest rates, EMIs, family responsibilities, savings aur financial goals different hote hain. Isliye ek personalised debt-management strategy zyada useful ho sakti hai.
InvestSathi ke saath apni income, liabilities, savings aur financial goals ko review karke ek structured personal finance strategy par guidance lein.
Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial, investment, tax, loan, or insurance advice. Debt repayment strategies depend on individual circumstances, loan terms, interest rates, repayment capacity, liquidity needs and financial goals. Please review applicable loan terms carefully and consider appropriate professional advice before making financial decisions.