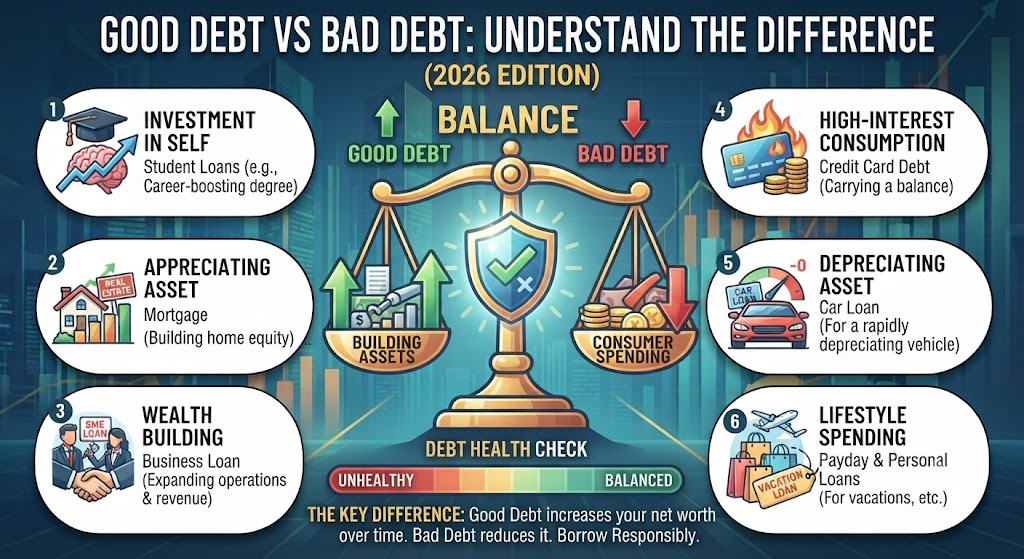
💳 Good Debt vs Bad Debt: Understand the Difference (2026 Guide)
Debt ko generally bad financial habit samjha jata hai, lekin har debt necessarily bad nahi hota. Kuch loans aapko productive asset ya long-term financial goal achieve karne mein help kar sakte hain, jabki kuch high-cost debt aapki financial progress ko negatively impact kar sakte hain.
Good Debt vs Bad Debt ko samajhna important hai, kyunki loan lene se pehle sirf EMI nahi, balki interest cost, purpose, repayment capacity aur overall financial impact ko bhi consider karna chahiye.
📖 Read Complete Good Debt vs Bad Debt Guide
What is Good Debt?
Good debt generally woh borrowing hoti hai jiska purpose long-term financial value create karna ya important productive goal ko finance karna ho. Lekin koi bhi loan automatically “good” nahi hota — affordability aur terms bhi important hain.
- 🏠 Home Loan – Suitable circumstances mein home purchase ko finance karne ke liye
- 🎓 Education Loan – Career aur earning potential improve karne ke liye education finance karna
- 💼 Business Loan – Productive business activity ya expansion ke liye
- 📈 Certain Asset-Financing Loans – Aise assets ke liye jo long-term value create kar sakte hain
💡 Good Debt Ka Matlab “Free Money” Nahi Hai — Repayment Capacity Aur Total Cost Hamesha Check Karein.
What is Bad Debt?
Bad debt generally woh borrowing hoti hai jo unnecessary consumption ko finance karti hai, high interest cost create karti hai ya repayment ke pressure ko unnecessarily increase karti hai.
- 💳 High-interest credit card debt
- 🛍️ Unnecessary shopping ke liye loans
- 📱 Lifestyle upgrades jo affordability se bahar hon
- ✈️ Unnecessary vacations ko debt se finance karna
- 🚗 Unaffordable vehicle financing
- 🔄 Ek loan repay karne ke liye repeatedly expensive debt lena
⚠️ High Interest + Unnecessary Spending + Low Repayment Capacity = Debt Risk
Good Debt vs Bad Debt – Quick Comparison
| Good Debt | Bad Debt |
|---|---|
| Potentially productive purpose | Primarily unnecessary consumption |
| May support long-term goals | May delay financial goals |
| Terms and affordability are assessed | Often expensive or poorly planned borrowing |
| Repayment is planned | Repayment may create financial stress |
| Can be part of a broader financial plan | Can reduce savings and investment capacity |
Examples of Good Debt
🏠 1. Home Loan
Home loan ek long-term financial commitment hota hai. Agar property purchase financially affordable hai aur EMI comfortably manage ho sakti hai, toh home loan ek productive financial decision ho sakta hai.
Lekin sirf property kharidna hi loan ko “good debt” nahi banata. High EMI, excessive borrowing ya unaffordable property financial stress create kar sakti hai.
🎓 2. Education Loan
Quality education ya professional qualification future earning potential improve kar sakti hai. Isliye suitable education financing ko long-term investment in earning capacity ke perspective se dekha ja sakta hai.
💼 3. Business Loan
Business loan ka purpose agar productive expansion, equipment, working capital ya revenue-generating activity ko support karna hai, toh borrowing business growth mein useful ho sakti hai.
Examples of Bad Debt
💳 1. High-Interest Credit Card Debt
Credit card ka convenience useful ho sakta hai, lekin outstanding balance par high interest financial burden create kar sakta hai. Minimum payment karte rehna debt ko long period tak carry kar sakta hai.
🛍️ 2. Unnecessary Shopping on EMI
Sirf isliye expensive product purchase karna ki EMI affordable dikh rahi hai, overall financial cost ko ignore kar sakta hai.
🚗 3. Unaffordable Vehicle Loan
Vehicle loan tab financial pressure create kar sakta hai jab EMI ke saath fuel, insurance, maintenance aur depreciation ko bhi comfortably manage karna difficult ho.
Not All Debt Fits Into Only Two Categories
Debt ko sirf “good” ya “bad” label karna hamesha sufficient nahi hota. Ek hi type ka loan different individuals ke liye different financial impact create kar sakta hai.
| Factor | Why It Matters |
|---|---|
| Interest Rate | Higher interest increases total borrowing cost |
| Loan Tenure | Longer tenure can affect total interest cost |
| Purpose | Productive and consumption borrowing have different outcomes |
| Repayment Capacity | EMI should fit comfortably within the overall budget |
| Income Stability | Unstable income can make fixed repayments more difficult |
How to Decide Whether a Loan is Worth Taking?
- Purpose Check Karein: Loan kis purpose ke liye liya ja raha hai?
- Total Cost Calculate Karein: Sirf EMI nahi, total repayment aur interest cost dekhein.
- Repayment Capacity Check Karein: EMI aapke monthly budget mein comfortably fit hoti hai ya nahi?
- Emergency Fund Consider Karein: Loan lene ke baad bhi adequate emergency reserve maintain ho paayega ya nahi?
- Other Debts Review Karein: Existing loans aur credit card obligations ko bhi consider karein.
- Alternative Compare Karein: Purchase postpone karna, save karna ya lower-cost option choose karna better hai ya nahi?
🎯 Before Taking Debt: Purpose + Cost + EMI + Repayment Capacity + Financial Goals
How Bad Debt Can Affect Your Financial Goals
High-cost debt ka impact sirf interest payment tak limited nahi hota. Excessive debt aapki monthly cash flow aur future savings capacity ko bhi reduce kar sakta hai.
- 📉 Monthly savings reduce ho sakti hain
- 💰 Investment capacity decrease ho sakti hai
- 🚨 Emergency fund build karna difficult ho sakta hai
- 🎓 Children’s education goals delay ho sakte hain
- 🏖️ Retirement planning impact ho sakti hai
- 😟 Financial stress increase ho sakta hai
How to Manage Existing Bad Debt?
- All Debts List Karein: Outstanding amount, interest rate aur EMI note karein.
- High-Cost Debt Identify Karein: Expensive debt ko priority se review karein.
- Unnecessary Borrowing Stop Karein: Jab tak existing debt manageable level par na aaye, unnecessary new borrowing avoid karein.
- Budget Tighten Karein: Temporary unnecessary expenses reduce karke repayment capacity improve karein.
- Extra Cash Flow Use Karein: Bonus ya additional income ko debt reduction ke liye consider kiya ja sakta hai.
- Debt Consolidation Carefully Evaluate Karein: Agar appropriate ho, lower-cost restructuring options ko compare karein.
Good Debt vs Bad Debt – Simple Rule
💡 Good Debt: Borrowing That Supports a Meaningful Financial Goal
⚠️ Bad Debt: Borrowing That Creates Unnecessary Cost and Financial Stress
Frequently Asked Questions
Q1. Kya har loan bad debt hota hai?
Nahi. Loan ka purpose, cost, repayment capacity aur overall financial impact determine karta hai ki borrowing financially suitable hai ya nahi.
Q2. Kya home loan good debt hai?
Home loan suitable circumstances mein productive borrowing ho sakta hai, lekin affordability, interest cost, tenure aur overall financial situation ko consider karna important hai.
Q3. Kya credit card bad debt hai?
Credit card khud automatically bad debt nahi hai. Lekin high-interest revolving balance ko carry karna expensive debt create kar sakta hai.
Q4. Kya education loan good debt hai?
Education loan potentially productive borrowing ho sakta hai agar education future career aur earning potential ko meaningfully support karti ho aur repayment financially manageable ho.
Q5. Kya personal loan good debt ho sakta hai?
Personal loan ka classification purpose aur cost par depend karta hai. Necessary financial need aur affordable repayment structure ka evaluation karna important hai.
Q6. Debt lene se pehle sabse important kya check karna chahiye?
Loan purpose, interest rate, total repayment cost, tenure, EMI, existing obligations aur repayment capacity ko carefully review karna chahiye.
Key Takeaway
🏠 Productive Debt + 💳 Controlled Borrowing + 📊 Smart Repayment = Better Financial Management
Debt ko sirf good ya bad label se judge karne ke bajay uska purpose, total cost, repayment capacity aur impact on your financial goals ko evaluate karna chahiye.
Create Your Personal Debt Management Plan
Har person ki income, existing loans, EMIs, family responsibilities, savings aur financial goals different hote hain. Isliye debt repayment aur overall financial planning ke liye personalised strategy zyada useful ho sakti hai.
InvestSathi ke saath apni income, liabilities, savings aur financial goals ko review karke ek structured personal finance strategy par guidance lein.
Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial, investment, tax, loan, or insurance advice. Whether a debt is suitable depends on individual circumstances, loan terms, interest costs, repayment capacity, financial goals and other obligations. Please carefully review applicable loan terms and seek appropriate professional advice before taking financial decisions.