“`html
🛡️ Emergency Fund vs Insurance: What Do You Need First? (2026 Guide)
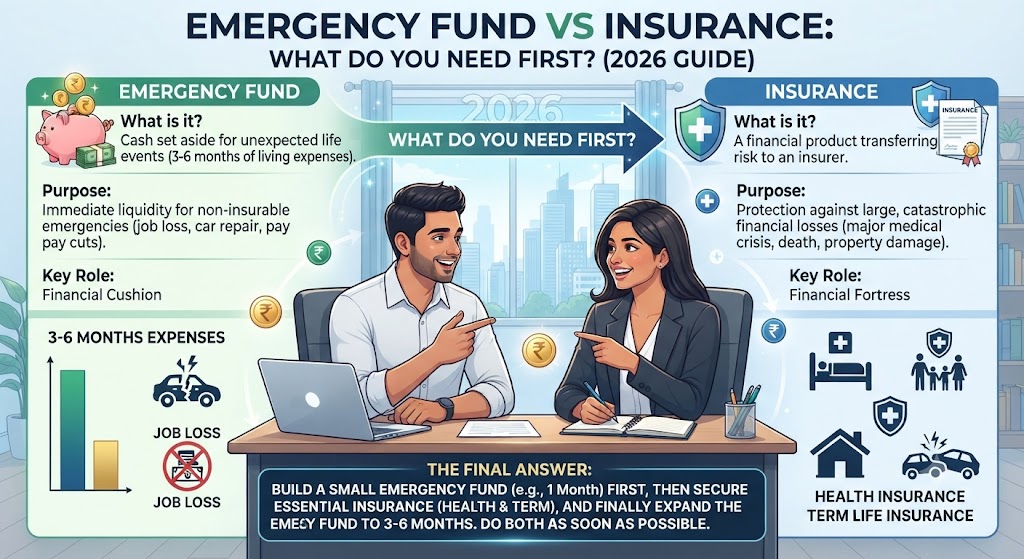
Financial planning mein Emergency Fund aur Insurance dono bahut important hain, lekin dono ka purpose alag hota hai. Emergency Fund aapko achanak aane wale chhote-bade financial emergencies se bachata hai, jabki Insurance bade financial risks se aapke parivar ko protect karta hai.
Lekin sawal yeh hai — pehle Emergency Fund banana chahiye ya Insurance lena chahiye? Is guide mein hum samjhenge ki Emergency Fund aur Insurance mein kya difference hai, kitna fund rakhna chahiye aur kis situation mein kiski priority honi chahiye.
📖 Read Complete Emergency Fund vs Insurance Guide
Emergency Fund Kya Hota Hai?
Emergency Fund ek aisa easily accessible financial reserve hota hai jo unexpected situations mein kaam aata hai. Jaise job loss, sudden medical expenses, urgent home repair ya income interruption.
Aam taur par emergency fund mein 3 se 6 months ke essential household expenses ke barabar amount rakhna useful maana jata hai. Self-employed individuals ya irregular income wale logon ko apni situation ke hisaab se isse zyada reserve rakhne ki zarurat ho sakti hai.
💡 Golden Rule: Emergency Fund ka purpose investment return kamana nahi, balki zarurat ke waqt paisa available rakhna hai.
Insurance Kya Karta Hai?
Insurance ka primary purpose aise financial risks ko transfer karna hai jo aapki savings ko bahut bada financial loss pahucha sakte hain.
- ❤️ Life Insurance: Policyholder ki death ki situation mein family ko financial protection provide kar sakta hai.
- 🏥 Health Insurance: Hospitalisation aur covered medical expenses ke financial impact ko reduce kar sakta hai.
- 🚗 Motor Insurance: Vehicle-related covered risks ke against protection provide karta hai.
- 🏢 Business Insurance: Business se jude selected risks ko manage karne mein help karta hai.
Emergency Fund vs Insurance
| Feature | Emergency Fund | Insurance |
|---|---|---|
| Main Purpose | Unexpected expenses ko manage karna | Large financial risks se protection |
| Example | Job loss, urgent repair, short-term expense | Death, hospitalisation, covered major risks |
| Money Access | Generally easily accessible hona chahiye | Policy terms aur claim conditions ke according |
| Recommended Approach | 3–6 months essential expenses ka reserve | Risk aur financial responsibilities ke according adequate cover |
Emergency Fund Kitna Hona Chahiye?
Emergency Fund calculate karne ke liye sabse pehle apne essential monthly expenses identify karein. Ismein rent/EMI, food, utilities, school fees, insurance premiums aur other essential commitments ko include kiya ja sakta hai.
| Monthly Essential Expenses | 3 Months | 6 Months |
|---|---|---|
| ₹30,000 | ₹90,000 | ₹1.80 Lakhs |
| ₹50,000 | ₹1.50 Lakhs | ₹3 Lakhs |
| ₹75,000 | ₹2.25 Lakhs | ₹4.50 Lakhs |
| ₹1,00,000 | ₹3 Lakhs | ₹6 Lakhs |
Pehle Emergency Fund Ya Insurance?
Aksar log sochte hain ki pehle emergency fund complete karne ke baad insurance lena chahiye. Lekin life aur health risks ka wait nahi kiya ja sakta.
✅ Practical Approach:
- Sabse pehle essential insurance protection ko ignore na karein.
- Life insurance ki zarurat hai toh adequate term cover consider karein.
- Health insurance ko bhi financial protection ka important part samjhein.
- Saath hi gradually 3–6 months ka Emergency Fund build karein.
- Emergency Fund ko gradually increase karein jaise income aur family responsibilities badhti hain.
Example: ₹60,000 Monthly Expenses Wala Family
Maan lijiye kisi family ke essential monthly expenses ₹60,000 hain. 6 months ka emergency reserve approximately ₹3.60 Lakhs ho sakta hai.
Lekin agar family ke earning member ke saath koi major life event ho jaye, toh ₹3.60 lakh ka emergency fund long-term family income replacement ke liye sufficient nahi hoga. Isi wajah se Emergency Fund aur Insurance ek-doosre ke alternatives nahi hain.
🛡️ Emergency Fund handles short-term financial shocks.
❤️ Insurance protects against major financial risks.
Common Mistakes to Avoid
- ❌ Sirf savings ko insurance ka replacement samajhna.
- ❌ Sirf insurance hone ki wajah se emergency fund ignore karna.
- ❌ Emergency Fund ko high-risk investments mein rakhna.
- ❌ Life insurance ka cover sirf premium affordability ke basis par decide karna.
- ❌ Health insurance ke importance ko ignore karna.
- ❌ Family responsibilities badhne ke baad financial protection review na karna.
Frequently Asked Questions
Q1. Kya Emergency Fund aur Insurance same cheez hain?
Nahi. Emergency Fund aapke paas available financial reserve hota hai, jabki Insurance specified risks ke against financial protection provide karta hai.
Q2. Emergency Fund kahan rakhna chahiye?
Emergency Fund ka focus liquidity aur capital safety par hona chahiye. Aise options choose karein jahan zarurat ke waqt paisa relatively easily available ho.
Q3. Kya Emergency Fund hone ke baad Life Insurance ki zarurat nahi hai?
Aisa nahi hai. Emergency Fund short-term financial needs ko manage karta hai, jabki adequate life insurance family ke long-term financial protection mein help karta hai.
Q4. Kya Health Insurance bhi zaroori hai?
Health-related expenses family finances par significant impact daal sakte hain. Isliye suitable health insurance ko overall financial protection planning ka important part consider kiya ja sakta hai.
Key Takeaway
💰 Emergency Fund + 🛡️ Insurance = Strong Financial Protection
Emergency Fund short-term emergencies ke liye aur Insurance major financial risks ke liye.
Get Your Financial Protection Plan Reviewed
Aapki income, monthly expenses, family responsibilities, loans aur financial goals ke according Emergency Fund aur Insurance ki requirement alag ho sakti hai.
InvestSathi ke saath apni financial protection needs ko review karein aur apne family goals ke according suitable planning par guidance lein.
Disclaimer: This article is for educational and informational purposes only and should not be considered professional financial, investment, or insurance advice. Insurance products are subject to terms, conditions, exclusions, and underwriting guidelines. Please read the relevant policy documents carefully before purchasing any insurance product.
“`